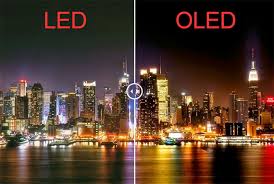
The rapid evolution of consumer electronics and commercial visual media has accelerated the demand for energy-efficient, high-resolution screens across various industry verticals. Central to this transformation is the display industry, where traditional lighting structures are steadily giving way to advanced light-emitting diode (LED) and organic light-emitting diode (OLED) architectures. The automotive, healthcare, retail, and entertainment sectors are heavily integrating these visual systems to improve user engagement and functional clarity. Flexible visual interfaces, ultra-high-definition television panels, and smart wearable accessories are serving as primary catalysts for this transition. As digital signage networks expand across smart cities and public transport hubs, visual hardware manufacturers are heavily investing in novel substrate materials to achieve greater energy efficiency and superior contrast ratios. To understand the complete commercial trajectory and competitive landscape, reviewing the LED And OLED Display Market analysis provides essential perspective on modern hardware adoption.
From an operational standpoint, the industry faces supply chain vulnerabilities regarding raw material procurement, specialized fabrication equipment, and complex organic compound synthesized layers. Despite high initial manufacturing overheads, organic diode panels continue to capture significant market interest in premium smartphone and television sectors due to their deep black levels, wide viewing angles, and thin profile characteristics. Meanwhile, micro-LED developments are emerging as a major technological bridge, combining the self-emissive advantages of organic layers with the durability and high brightness of inorganic materials. Group discussions surrounding this market often center on whether production costs can decline rapidly enough to democratize high-end panels across mid-tier consumer markets, or if older liquid crystal technologies will maintain dominance in cost-sensitive global regions through continuous incremental enhancements.
What is driving the primary demand for OLED technology in modern electronics?
The demand is primarily driven by the superior visual contrast, energy efficiency, ultra-thin physical profiles, and flexibility offered by self-emissive organic displays compared to conventional back-lit panels.
What are the main technical challenges facing wide-scale micro-LED adoption?
Key challenges include complex mass transfer fabrication processes, high manufacturing equipment costs, yield management issues, and the thermal stability of microscopic LED components.
➤➤➤Explore MRFR’s Related Ongoing Coverage In Semiconductor Industry:
Debt Collection Software Market
AI in Video Surveillance Market