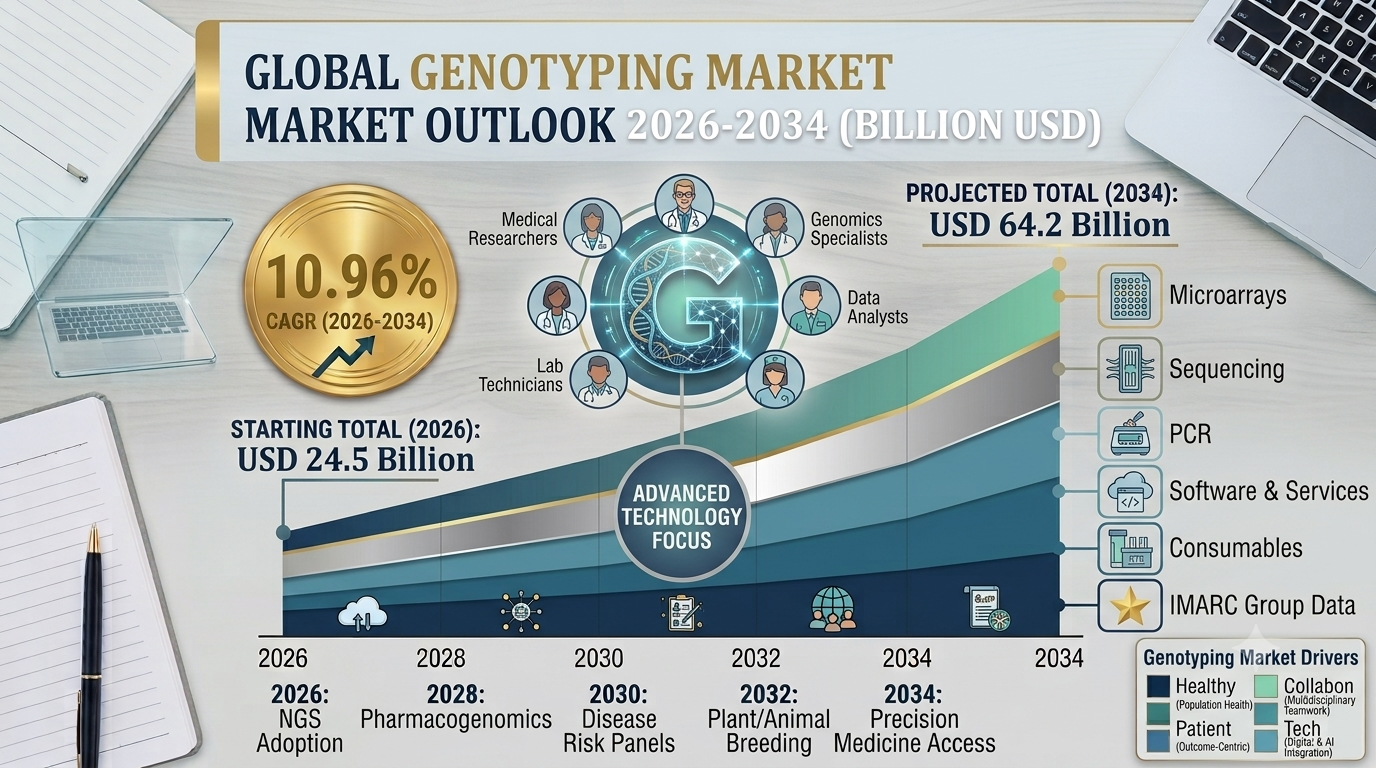
According to IMARC Group, the global genotyping market was valued at USD 24.5 Billion in 2025 and is projected to reach USD 64.2 Billion by 2034, expanding at a CAGR of 10.96% during 2026–2034. This exceptional genotyping market growth reflects soaring demand for precision diagnostics, expanding agricultural genomics applications, and the rapid integration of next-generation sequencing technologies into mainstream healthcare and research workflows.
Genotyping Industry Overview
The genotyping industry sits at the intersection of genomics, diagnostics, agriculture, and pharmaceutical research. Genotyping refers to determining differences in the genetic makeup of an individual by examining their DNA sequence and comparing it to another individual's or a reference sequence. Modern genotyping platforms have dramatically expanded the scope of what can be analyzed — from single-nucleotide polymorphisms (SNPs) to whole-genome variants — making the technology applicable across clinical, research, and consumer domains.
Key genotyping services and product categories include:
- Instruments: Sequencers, PCR machines, microarray scanners, and mass spectrometers
- Reagents and Kits: PCR reagents, genotyping arrays, sample preparation kits, and assay kits
- Software and Services: Bioinformatics platforms, data analysis tools, and genotyping-as-a-service offerings
These solutions serve a diverse ecosystem of end-users including pharmaceutical companies, clinical diagnostic laboratories, academic research institutions, agricultural biotech firms, and direct-to-consumer genetic testing companies.
Global Genotyping Market Size & Key Statistics
Below are the key Genotyping Market Size statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020–2025 |
| Forecast Period | 2026–2034 |
| Market Size in 2025 | USD 24.5 Billion |
| Market Forecast in 2034 | USD 64.2 Billion |
| Market Growth Rate (2026–2034) | 10.96% CAGR |
| Largest Region | North America (39.80% share) |
Request for a Sample Report for Detailed Market Insights Evaluation: https://www.imarcgroup.com/genotyping-market/requestsample
Key Genotyping Market Trends & Growth Drivers in 2026
Several powerful forces are shaping Genotyping Market Trends and fueling strong growth expectations across global healthcare and agricultural markets:
- Rising Adoption of Precision Medicine and Personalized Therapies
The global movement toward precision medicine has placed genotyping at the heart of modern healthcare. By identifying genetic variants that influence disease susceptibility and drug response, genotyping enables clinicians to tailor treatments to individual patients. As healthcare systems worldwide invest in genomic medicine frameworks, demand for genotyping platforms and services is accelerating rapidly.
- Integration of Next-Generation Sequencing (NGS) Technologies
Advanced NGS platforms are transforming the Genotyping Market by offering higher throughput, greater accuracy, and the ability to analyze thousands of genetic variants simultaneously. In September 2025, Illumina launched Illumina Protein Prep — an NGS-based proteomics assay capable of measuring 9,500 unique human protein targets, with Genomics England reporting a 7.5% increase in diagnostic yield for rare disease cases. Such innovations are continuously expanding the capabilities and commercial appeal of genotyping technologies.
- Expanding Applications in Agricultural Biotechnology
Genotyping has become indispensable in modern agriculture, enabling plant breeders and livestock managers to select superior genetic traits, improve crop yields, enhance disease resistance, and accelerate breeding cycles. The growing global focus on food security and sustainable agriculture is driving investment in agricultural genotyping, broadening the market well beyond its clinical origins.
- Rising Popularity of Direct-to-Consumer (DTC) Genetic Testing
Growing health consciousness and curiosity about ancestry, wellness, and genetic risk factors are fueling the DTC genetic testing segment. Consumers are increasingly purchasing at-home genotyping kits to gain insights into their predispositions for various conditions. This consumer-driven demand is creating new revenue streams for genotyping companies and broadening market accessibility.
- Healthcare Cost Pressures Driving Preventive Genomics
The estimated cost of chronic disease is expected to reach USD 47 Trillion worldwide by 2030, creating immense pressure on healthcare systems to invest in preventive strategies. Genotyping enables predictive risk profiling that allows early identification of disease predispositions before illnesses advance to costly late-stage treatments. Governments, insurers, and healthcare providers are increasingly integrating genotyping into precision medicine programs and wellness initiatives as cost-containment strategies.
- Government Healthcare Investments Fueling Genomics Expansion
National health policies worldwide are prioritizing genomics as part of broader healthcare modernization strategies. For example, the Indian government allocated Rs. 99,858 crore (USD 11.50 Billion) to the healthcare sector in the Union Budget 2025-26, with genomics and biotechnology development among the focus areas. Such public funding lowers barriers to genotyping adoption, fosters public-private collaboration, and accelerates infrastructure development across emerging markets.
- Growing Burden of Chronic and Complex Diseases
With 42% of Americans managing two or more chronic conditions and 12% living with at least five, there is a growing clinical need for personalized genomic services. Traditional treatment protocols fail to account for the genetic differences influencing drug efficacy and disease progression. Genotyping provides the clarity needed to optimize therapies for patients with complex health profiles, driving adoption across primary care and specialty clinics.
Key Genotyping Market Segmentation
By Product and Service
- Reagents and Kits – Largest Segment (~48.9% share in 2025)
Reagents and kits dominate the market due to their recurring demand — laboratories must continually procure them for each test conducted. The growing number of diagnostic centers, rising DTC genetic testing, and increased pharmacogenomics research are fueling higher kit consumption. Standardized, automation-compatible reagent systems have simplified genotyping and expanded accessibility across both advanced labs and smaller testing setups.
- Instruments
- Software and Services
By Technology
- Polymerase Chain Reaction (PCR) – Largest (~34.8% share in 2025)
PCR leads due to its long-established reliability, cost-effectiveness, and widespread adoption across clinical and research settings. The method's compatibility with diverse downstream applications, continuous technological refinement (real-time PCR, digital PCR), and cost-effectiveness in emerging economies ensure its dominant market position.
- Capillary Electrophoresis
- Microarray
- Sequencing
- Mass Spectrometry
- Others
By Application
- Diagnostics and Personalized Medicine – Largest (~33.8% share in 2025)
This segment leads the market as genotyping directly addresses the global rise in chronic and complex diseases where traditional treatments are often ineffective. Healthcare systems are investing in genomic testing for earlier diagnosis, better therapeutic alignment, and improved patient outcomes. Pharmaceutical companies leverage genotyping in clinical trials to stratify patients and develop precision therapies.
- Pharmacogenomics
- Agricultural Biotechnology
- Animal Genetics
- Others
By End User
- Pharmaceutical and Biopharmaceutical Companies – Major Segment
These companies utilize genotyping to identify genetic markers linked to drug response and disease susceptibility, enabling precision therapy design and clinical trial efficiency. Rising investment in personalized medicine is expanding demand for advanced genotyping platforms.
- Diagnostics and Research Laboratories
- Academic Institutes
- Others
Connect for Detailed Segmentation Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=5815&flag=C
Regional Genotyping Market Analysis
| Region | Key Highlights |
| North America – Largest (39.80%) | United States & Canada; advanced healthcare infrastructure, strong research funding, widespread personalized medicine adoption, leading biotech and pharma firms, robust reimbursement for genetic testing |
| Europe | Germany, France, UK, Italy, Spain, Russia; growing geriatric population driving demand, technological advances in high-throughput sequencing and microarrays, aging population fueling clinical trials and biobanking |
| Asia Pacific | China, Japan, India, South Korea, Australia; fast-expanding diagnostics laboratories, government healthcare investments, rising pharmaceutical industry, growing medical tourism, NGS platform adoption |
| Latin America | Brazil, Mexico; growing healthcare expenditure (Brazil's Unified Health System budget +6.2% in 2025), expanding laboratory modernization, broader access in urban healthcare settings |
| Middle East & Africa | UAE, Saudi Arabia, South Africa; rising cancer burden (27% of GCC's total cancer cases in Saudi Arabia), growing oncology genotyping, enhanced diagnostic technology access |
Leading Players in the Genotyping Industry
The global genotyping market features established genomics leaders and specialized diagnostics innovators competing on technological advancement, platform breadth, and strategic partnerships. Key companies covered in the IMARC Group report include:
- Agilent Technologies Inc.
- Bio-Rad Laboratories Inc.
- Danaher Corporation
- Eurofins Scientific SE
- F. Hoffmann-La Roche AG
- Illumina Inc.
- Laboratory Corporation of America Holdings
- Qiagen N.V.
- Standard BioTools Inc.
- Thermo Fisher Scientific Inc.
The report includes comprehensive competitive analysis covering market structure, player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant.
Latest Industry Developments
June 2025 – Mission Bio
Mission Bio unveiled a first-of-its-kind Single-Cell Genotype and Targeted Gene Expression solution through its Tapestri Platform, enabling simultaneous profiling of genotype and gene expression from over 10,000 single cells. This breakthrough offered new insights into tumor heterogeneity, therapeutic resistance, and T-cell dysfunction — advancing cancer drug clinical development.
June 2025 – Devyser
Devyser launched its Genomic Blood Typing assay as a global NGS-based solution that simplified genotyping by enabling comprehensive analysis of RBC, HPA, and HNA systems in one test. The solution empowered research labs and transfusion centers with high-resolution results and streamlined workflows for molecular blood group genotyping.
May 2025 – Almac Diagnostic Services
Almac Diagnostic Services launched the PNPLA3 Genotyping Kit to support liver disease research, enabling accurate genotyping of the PNPLA3 gene and aiding studies into MASH and MASLD. The kit offered ≥99% reproducibility from blood or buccal swabs, helping researchers explore genetic risk factors and disease severity.
March 2025 – Fujirebio Europe
Fujirebio Europe launched the INNO-LiPA® HCV 2.0 Genotyping assay, a line probe assay aiding personalized HCV therapy by identifying HCV genotypes 1 to 6 and subtypes 1a and 1b. The genotyping test was designed for in vitro diagnostics using human serum or EDTA plasma samples.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Technology, Healthcare, Agriculture, Life Sciences, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104