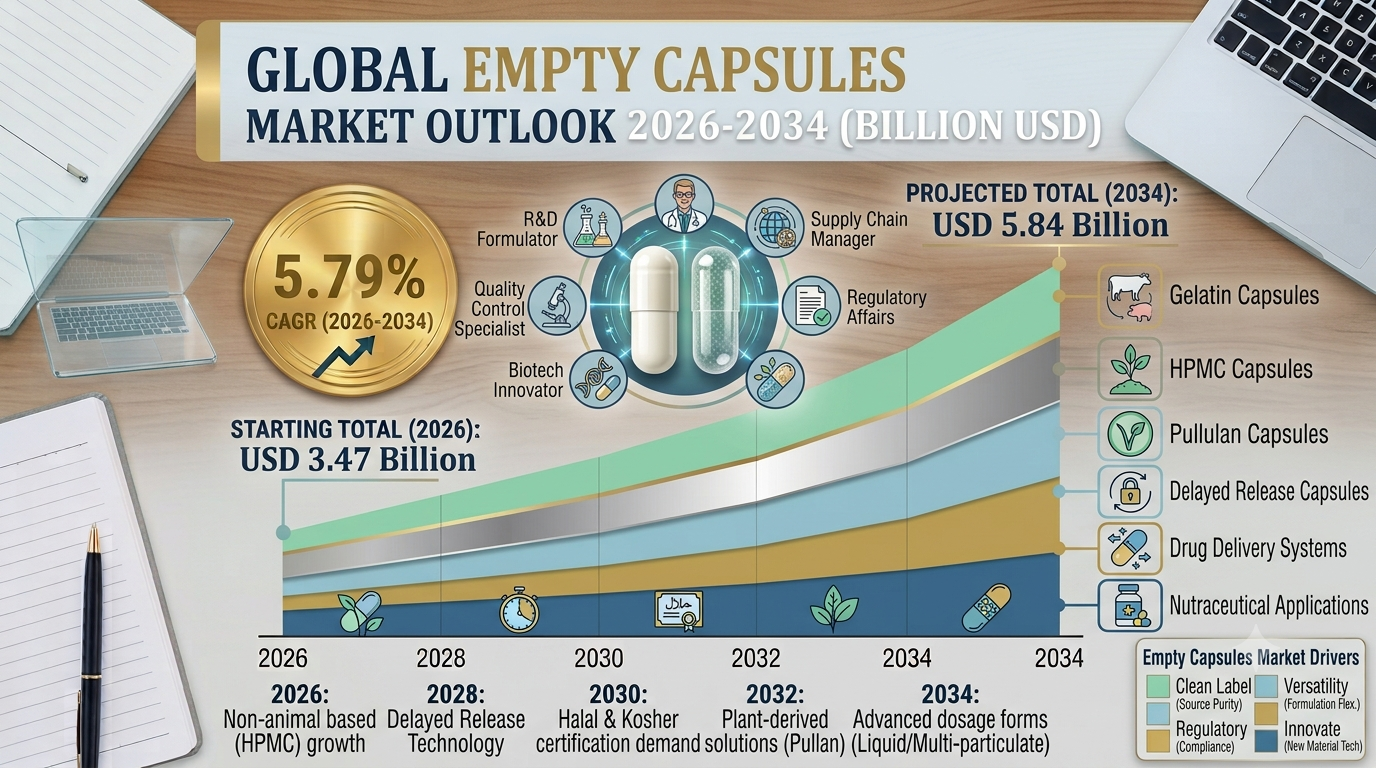
According to IMARC Group, the global empty capsules market size reached USD 3.47 Billion in 2025 and is projected to reach USD 5.84 Billion by 2034, expanding at a CAGR of 5.79% during 2026–2034. This robust empty capsules market growth reflects rising pharmaceutical production, booming nutraceutical consumption, vegetarian capsule innovation, and the expanding generic drug manufacturing base across global healthcare markets.
Empty Capsules Industry Overview
Empty capsules serve as the fundamental building blocks of modern drug delivery systems. They are manufactured in two primary formats hard two-piece capsules and soft-gel capsules from either animal-derived gelatin or plant-based materials such as hydroxypropyl methylcellulose (HPMC), pullulan, and starch. Their utility spans pharmaceutical drug formulation, dietary supplement encapsulation, and cosmetic ingredient delivery across global manufacturing facilities.
Key capsule types and functionalities include:
- By Type: Gelatin Capsules (73.4% market share, 2025) and Non-gelatin Capsules (26.6%)
- By Functionality: Immediate-release Capsules (50.2%), Sustained-release Capsules (29.1%), and Delayed-release Capsules (20.7%)
- By Raw Material: Pig Meat, Bovine Meat, Bone, Hydroxypropyl Methylcellulose (HPMC), and Others
- By End User: Pharmaceutical Industry, Nutraceutical Industry, Cosmetics Industry, and Others
Global Market Overview & Empty Capsules Market Size Statistics
Below are the key empty capsules market size statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020–2025 |
| Forecast Period | 2026–2034 |
| Market Size in 2025 | USD 3.47 Billion |
| Market Forecast in 2034 | USD 5.84 Billion |
| Market Growth Rate (2026–2034) | 5.79% CAGR |
| Largest Region | North America (34.5% share) |
| Leading Type | Gelatin Capsule (73.4%) |
| Leading Functionality | Immediate-release Capsules (50.2%) |
Request for a Sample Report for Detailed Market Insights Evaluation: https://www.imarcgroup.com/empty-capsules-market/requestsample
Key Market Drivers & Empty Capsules Market Trends in 2026
Several powerful forces are shaping Empty Capsules Market Trends and fueling consistent growth across global pharmaceutical and nutraceutical markets:
- Rising Global Pharmaceutical Production and Generic Drug Manufacturing
Global pharmaceutical production is expanding steadily, with generics manufacturing in India, China, and emerging markets driving bulk capsule demand. The WHO Essential Medicines program and patent cliffs on branded drugs continue to accelerate generic formulation activity, directly amplifying consumption of pharmaceutical-grade empty capsules worldwide.
- Expanding Nutraceutical and Dietary Supplement Market
Growing health awareness, increasing focus on preventive healthcare, and rising consumer interest in wellness products are driving demand for dietary supplements worldwide. The continued expansion of the nutraceutical industry has significantly increased the need for high-quality gelatin and non-gelatin empty capsules across major global markets.
- Innovation in Vegetarian and Plant-Based Capsule Materials
Growing consumer demand for vegan, vegetarian, kosher, and halal-certified products is accelerating adoption of HPMC, pullulan, and starch-based non-gelatin capsule materials. Regulatory approvals and clinical validation of plant-based capsules across major pharmaceutical markets are further expanding their addressable customer base globally.
- Increasing Prevalence of Chronic Diseases Requiring Oral Drug Delivery
Rising global incidence of diabetes, cardiovascular disease, hypertension, and oncological conditions is increasing the volume of oral medication prescriptions globally. Empty capsules serve as the preferred delivery format for powder-filled and modified-release pharmaceutical formulations targeting these high-prevalence therapeutic categories worldwide.
- Modified-Release and Specialty Capsule Technology Development
Modified-release capsule technologies — including delayed-release enteric coatings, sustained-release polymer systems, and two-compartment capsule-in-capsule designs — command significant price premiums. Growing clinical demand for targeted gastrointestinal delivery and chronotherapy creates high-value differentiation opportunities for leading manufacturers.
- AI-Enabled Quality Control Transforming Capsule Manufacturing
Artificial intelligence-assisted vision inspection and automated quality control systems are being deployed by leading capsule manufacturers to achieve near-zero defect rates. Companies like ACG and Lonza Group AG have pioneered AI-enabled inspection platforms, substantially improving throughput, defect detection, and pharmacopoeial compliance globally.
Key Market Segmentation
By Type
Gelatin Capsules – Largest Segment (73.4% share)
Gelatin Capsules command a 73.4% majority share in 2025, driven by their cost-effectiveness, widespread pharmacopoeial acceptance, and established manufacturing infrastructure. Animal-derived gelatin remains the dominant raw material for pharmaceutical-grade capsule shells, supported by mature supply chains and superior mechanical properties for high-speed filling operations globally.
Non-gelatin Capsules
Non-gelatin Capsules at 26.6% represent the fastest-growing type segment, driven by rising vegan and vegetarian consumer demand, halal and kosher certification requirements, and pharmaceutical producers requiring moisture-impermeable HPMC formats for sensitive biologics, probiotics, and moisture-reactive active pharmaceutical ingredients.
By Functionality
Immediate-release Capsules – Largest (50.2% share)
Immediate-release Capsules dominate functionality at 50.2% in 2025, reflecting the standard encapsulation format for most pharmaceutical and nutraceutical products requiring rapid dissolution and bioavailability. The segment is anchored by high-volume generic drug production and mass-market dietary supplement manufacturing across all global production regions.
Sustained-release and Delayed-release Capsules
Sustained-release Capsules at 29.1% serve pharmaceutical applications requiring extended therapeutic effect with reduced dosing frequency, particularly for cardiovascular, CNS, and pain management drugs. Delayed-release Capsules at 20.7% — growing at the fastest CAGR of ~8.05% — are driven by enteric drug delivery applications protecting acid-labile APIs and targeting intestinal absorption in gastroenterology and precision therapeutics.
By End User
Pharmaceutical Industry – Largest Segment
The pharmaceutical industry accounts for the largest end-user share due to its high-volume, regulated encapsulation requirements across branded and generic drug manufacturing. Stringent pharmacopoeial standards (USP, EP, JP) governing pharmaceutical-grade capsule quality ensure sustained procurement from premium capsule suppliers.
Nutraceutical Industry
The nutraceutical industry represents a rapidly expanding end-user segment, driven by rising consumer interest in dietary supplements, vitamins, and functional ingredients. Growing demand for clean-label and vegan-certified supplements is accelerating adoption of HPMC and pullulan-based capsule materials across this segment globally.
Regional Market Analysis
| Region | Share (2025) | Key Highlights |
| North America – Largest | 34.5% | United States & Canada; advanced pharmaceutical infrastructure, high nutraceutical consumption, strong generics market, leading supplement adoption |
| Europe | 27.8% | Germany, France, UK, Italy, Spain; mature pharmaceutical manufacturing, aging population, stringent quality standards, premium capsule demand |
| Asia Pacific | 24.6% | China, Japan, India, South Korea, Australia; fastest-growing region, expanding generic drug production, rising health awareness, growing pharma export volumes |
| Latin America | 7.4% | Brazil, Mexico; growing nutraceutical demand, expanding pharmaceutical manufacturing, rising healthcare investment |
| Middle East & Africa | 5.7% | UAE, Saudi Arabia, South Africa; increasing healthcare spending, growing pharmaceutical manufacturing, rising supplement consumption |
Connect for Detailed Segmentation Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=5187&flag=C
Leading Players in the Empty Capsules Industry
The global empty capsules market features a moderately concentrated competitive landscape, with multinational corporations commanding significant market shares alongside regional specialists and emerging Asian manufacturers. Key companies covered in the IMARC Group report include:
- ACG
- Bright Pharma Caps
- HealthCaps India
- Medicaps Limited
- Suheung Co., Ltd.
The report includes competitive analysis covering market structure, player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant.
Latest Industry Developments
October 2025 – ACG
ACG invested $200 million in establishing its first hard-shell capsule manufacturing operations in the United States, strengthening its presence in the North American pharmaceutical and nutraceutical markets. The phased investment will support the development of a new manufacturing facility in Atlanta, Georgia, focused on producing both gelatin and vegetarian (HPMC) capsules.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Technology, Construction, Healthcare, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104