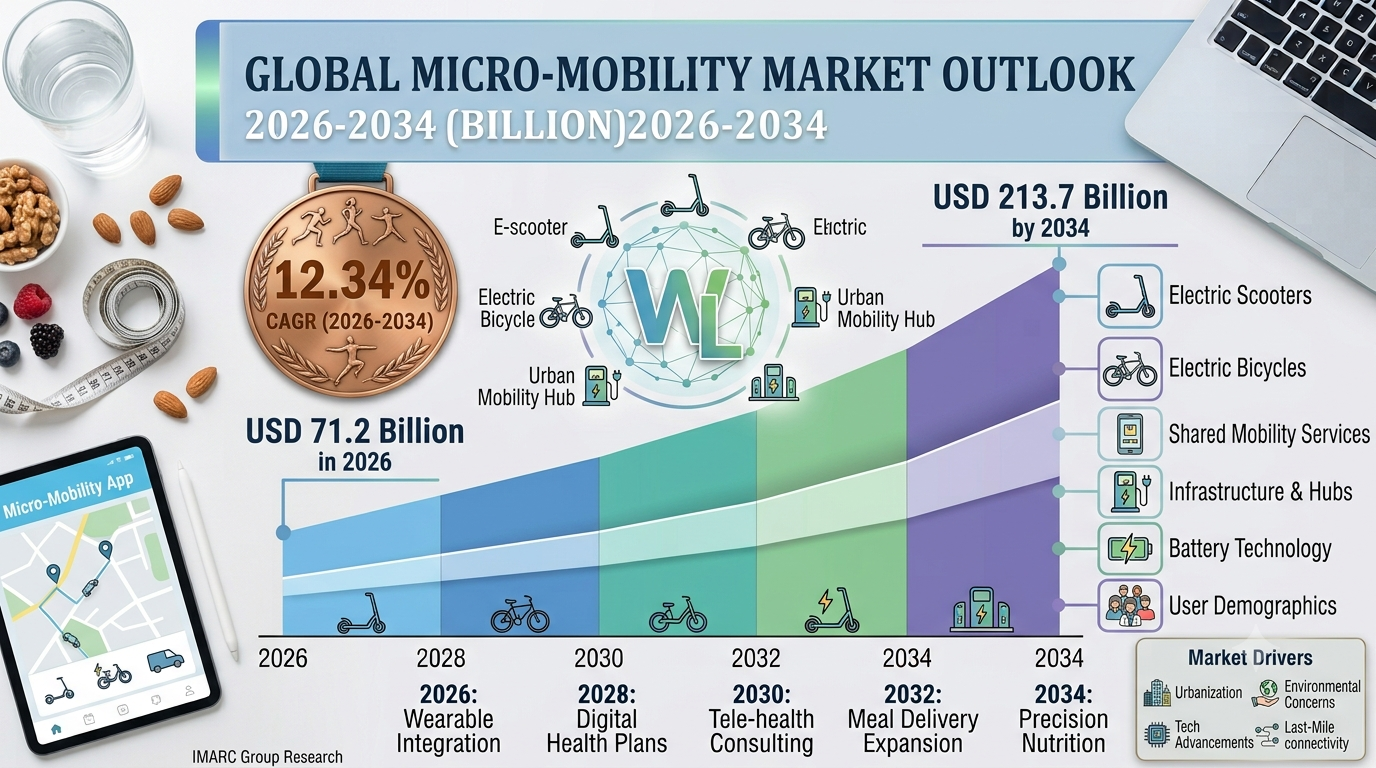
According to IMARC Group, the global micro-mobility market size was valued at USD 71.2 Billion in 2025 and is projected to reach USD 213.7 Billion by 2034, growing at a robust CAGR of 12.34% from 2026 to 2034. This explosive growth reflects converging forces: rampant urbanization, mounting environmental regulations, advances in battery technology, and an expanding ecosystem of shared mobility services across global cities.
Micro-Mobility Market Overview
The micro-mobility landscape encompasses a diverse range of compact, lightweight transport solutions designed for short-distance travel — typically under 10 kilometers. These include pedal bicycles, e-bikes, e-kick scooters, and emerging vehicle categories, deployed through both private ownership and shared mobility platforms.
The micro-mobility market trends point to an ecosystem rapidly evolving beyond simple rental fleets. Today's platforms are integrating GPS tracking, IoT connectivity, AI-powered navigation, and seamless app-based payment systems to deliver frictionless user experiences. As cities worldwide invest in dedicated cycling infrastructure, docking stations, and clean energy charging networks, the sector is positioning itself as a foundational pillar of sustainable urban mobility.
Key vehicle categories driving the market include:
- Bicycles – Traditional and smart-connected pedal bikes for eco-friendly commuting
- E-Bikes – Electrically-assisted bicycles extending range and accessibility
- E-Kick Scooters – Compact electric scooters ideal for last-mile urban connectivity
- Others – Emerging categories including e-mopeds, hoverboards, and electric unicycles
Global Micro-Mobility Market Size & Key Statistics
Below are key micro-mobility market statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020–2025 |
| Forecast Period | 2026–2034 |
| Market Size in 2025 | USD 71.2 Billion |
| Market Forecast in 2034 | USD 213.7 Billion |
| Market Growth Rate (2026–2034) | 12.34% CAGR |
| Largest Region | Asia Pacific (45.0% share) |
Request for a Sample Report for Detailed Micro-Mobility Market Share Evaluation: https://www.imarcgroup.com/micro-mobility-market/requestsample
Key Market Drivers & Micro-Mobility Market Trends in 2026
Several powerful forces are reshaping the global micro-mobility landscape and driving accelerating adoption across urban centers worldwide:
1. Rapid Urbanization and Traffic Congestion
The increasing rate of urbanization is a primary catalyst for micro-mobility adoption. According to the International Transport Forum, traffic congestion costs cities approximately 1–2% of their GDP annually. As urban populations grow, traditional car-centric transport becomes increasingly impractical — creating strong tailwinds for compact, agile micro-mobility solutions that offer faster, more efficient first-and-last-mile connectivity.
2. Sustainability and Environmental Concerns
Environmental awareness is fundamentally reshaping micro-mobility market trends. The European Environment Agency reports that transport contributes 25% of the EU's total greenhouse gas emissions. Electric micro-mobility vehicles produce zero operational emissions, making them a compelling alternative for environmentally conscious commuters and city planners targeting net-zero goals. Governments globally are incentivizing clean transport adoption, further accelerating micro-mobility market share expansion.
3. Technological Advancements in Battery and Connectivity
Ongoing innovation in battery technology is extending the range and improving performance of e-scooters and e-bikes, dramatically enhancing their real-world utility. Simultaneously, the integration of IoT devices, AI-powered navigation (such as Google's Project Green Light for traffic optimization), and 5G connectivity is enabling smarter, safer, and more efficient micro-mobility operations — raising the bar for user experience and fleet management alike.
4. Surge in Shared Mobility Platforms
The rise of app-based shared mobility services has democratized access to micro-mobility solutions. Platforms like Lime, Bird, Dott, and Beam Mobility are scaling fleets in major cities, offering affordable pay-per-ride and subscription models. This accessibility is attracting a wide demographic base — from daily commuters supplementing public transit to tourists seeking convenient city exploration options.
5. Regulatory Support and Infrastructure Investment
Governments and municipal authorities are increasingly enacting policies to support micro-mobility growth — establishing dedicated e-scooter and cycling corridors, building parking docks and charging infrastructure, and revising traffic regulations. In 2025, the U.S. Department of Transportation revealed $2.4 billion in new rail and sustainable transport projects, while the EU allocated EUR 500 million specifically for the micro-mobility ecosystem, reflecting the sector's growing strategic importance.
6. Rising Fuel Costs and Cost-Efficiency Demands
Escalating fuel prices are accelerating consumer migration toward cost-efficient mobility alternatives. E-bikes and e-scooters offer dramatically lower total costs of ownership compared to private vehicles, particularly in urban settings where trips are short and parking is expensive. The B2C ownership model is also gaining traction, as one-time device investment proves more economical than accumulated rental fees over time.
Key Micro-Mobility Market Segmentation
By Type
Bicycles – Largest Segment (85.0% share)
Bicycles dominate the type segment with an 85.0% share, driven by growing emphasis on sustainable, eco-friendly commuting. Technological advancements — including smart connectivity features and integrated sensors — are broadening bicycle appeal beyond traditional cyclists to tech-savvy urban commuters. Health consciousness, combined with low operational costs, continues to position bicycles as the cornerstone vehicle type within the micro-mobility ecosystem.
- E-Bikes – Fast-growing segment; enhanced range through electric assistance
- E-Kick Scooters – Urban last-mile staple; widely deployed through sharing platforms
- Others – Emerging alternative categories
By Propulsion Type
Electrically-Powered – Dominant (70.0% share)
Electrically-powered propulsion commands a 70.0% market share, fueled by environmental sustainability mandates and advances in battery technology. Electric micro-mobility devices align with urban clean air initiatives, offering zero operational emissions while providing cost-effective, low-maintenance transport solutions. Improved battery range and reduced charging times are removing previous barriers to adoption.
- Manual – Traditional pedal-powered options retaining a loyal user base
- Hybrid – Emerging flex-propulsion models for versatile commuting
By Sharing Type
Docked – Leading (54.5% share)
Docked sharing systems hold a 54.5% share, reflecting user preference for organized, predictable access to micro-mobility vehicles. Designated docking stations reduce parking clutter, ensure vehicle availability, and facilitate seamless integration with existing public transit networks — a key factor driving municipal partnerships and city-wide deployment programs.
- Dock-less – Flexible alternative; growing in cities prioritizing user convenience
By Age Group
15–34 Years – Dominant (65.0% share)
The 15–34 age group accounts for 65.0% of micro-mobility market share, reflecting this demographic's affinity for urban living, digital-first services, and sustainable transport choices. Tech-savvy and environmentally conscious, younger consumers are the primary adopters of app-based e-scooter and e-bike services — making this cohort central to platform growth strategies globally.
- 35–54 Years – Growing segment driven by commuting efficiency and wellness
- 55 and Above – Emerging adopters, particularly of e-bike assistance models
By Ownership
Business-to-Consumer (B2C) – Leading Ownership Model
The B2C model is gaining prominence as consumers seek personalized, always-available mobility. Private ownership eliminates recurring rental costs, offering long-term economic advantages, while providing users with full customization and maintenance control over their chosen device.
- Business-to-Business (B2B) – Fleet deployments for corporate campuses, logistics, and tourism
Regional Micro-Mobility Market Analysis
The Micro-Mobility Market Share varies meaningfully across global regions, each shaped by unique combinations of urban density, regulatory frameworks, and technological readiness:
| Region | Key Highlights |
| Asia Pacific – Largest (45.0%) | China, Japan, India, South Korea, Australia, Indonesia; rapid urbanization, high population density, government eco-transport policies, widespread smartphone adoption, surge in shared mobility |
| North America | United States & Canada; increased bike lane investment, multimodal commuting, government EV incentives, tech-savvy urban consumers, sustainable transport push |
| Europe | Germany, France, UK, Italy, Spain, Russia; 35% rise in micro-mobility registrations (2023), EUR 500M EU investment, strong cycling culture, policy support for clean urban transit |
| Latin America | Brazil, Mexico; Brazil sold 600,000+ e-bikes & scooters (2023), Tembici reported 250M+ bike journeys, government clean energy mandates, growing urban infrastructure |
| Middle East & Africa | UAE, Saudi Arabia, South Africa; e-scooter users in Saudi Arabia projected at 267,100 by 2029, Lime & Circ expanding, UAE sustainable urban mobility initiatives |
Connect for Detailed Segmentation Analysis: https://www.imarcgroup.com/request?type=report&id=7200&flag=C
Leading Players in the Micro-Mobility Market
The global micro-mobility competitive landscape is dynamic and rapidly evolving, with established transport technology companies and specialized mobility-as-a-service providers competing for urban market share. Key companies profiled in the IMARC Group report include:
- Accell Group N.V.
- Beam Mobility Holdings Pte. Ltd.
- Bird Rides Inc.
- CycleHop LLC
- Dott
- Lime (Neutron Holdings, Inc)
- Micro Mobility Systems AG
- Neuron Mobility
- Segway Discovery Inc.
The competitive analysis includes market structure mapping, player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant to help stakeholders understand the current dynamics shaping the Micro-Mobility Market Share.
Latest Industry Developments
October 2024 – TIER Mobility & Dott Merger
TIER merged with Dott to create a unified micromobility service operating under the Dott brand across 427 cities. The merger integrates 250,000 electric scooters and e-bikes into the Dott app, with full rebranding expected to complete by early 2025 — creating one of the largest micro-mobility footprints in Europe.
July 2024 – Neuron AI-Powered Safety Cameras
Neuron announced the installation of AI-powered cameras across its entire fleet of 1,250 e-scooters in Melbourne to detect footpath riding. The ScootSafe Vision system issues real-time warnings and can automatically adjust vehicle speed — a landmark development in smart fleet safety management.
June 2024 – Segway Care Commercial Launch
Segway introduced Segway Care Commercial, a new after-sale service for shared micro-mobility operators, offering an extended 12-month warranty covering key e-scooter and e-bike components — targeting improved total cost of ownership and fleet sustainability for sharing platform operators.
May 2023 – Bird Rides Inc. Expansion
Bird Rides Inc. announced service expansion into eight additional cities across the US, Canada, and Australia — broadening access to its e-scooter and e-bike fleet and reinforcing the global push toward sustainable, affordable urban micro-mobility solutions.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Technology, Automotive, Healthcare, Energy, Transportation and Logistics, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104