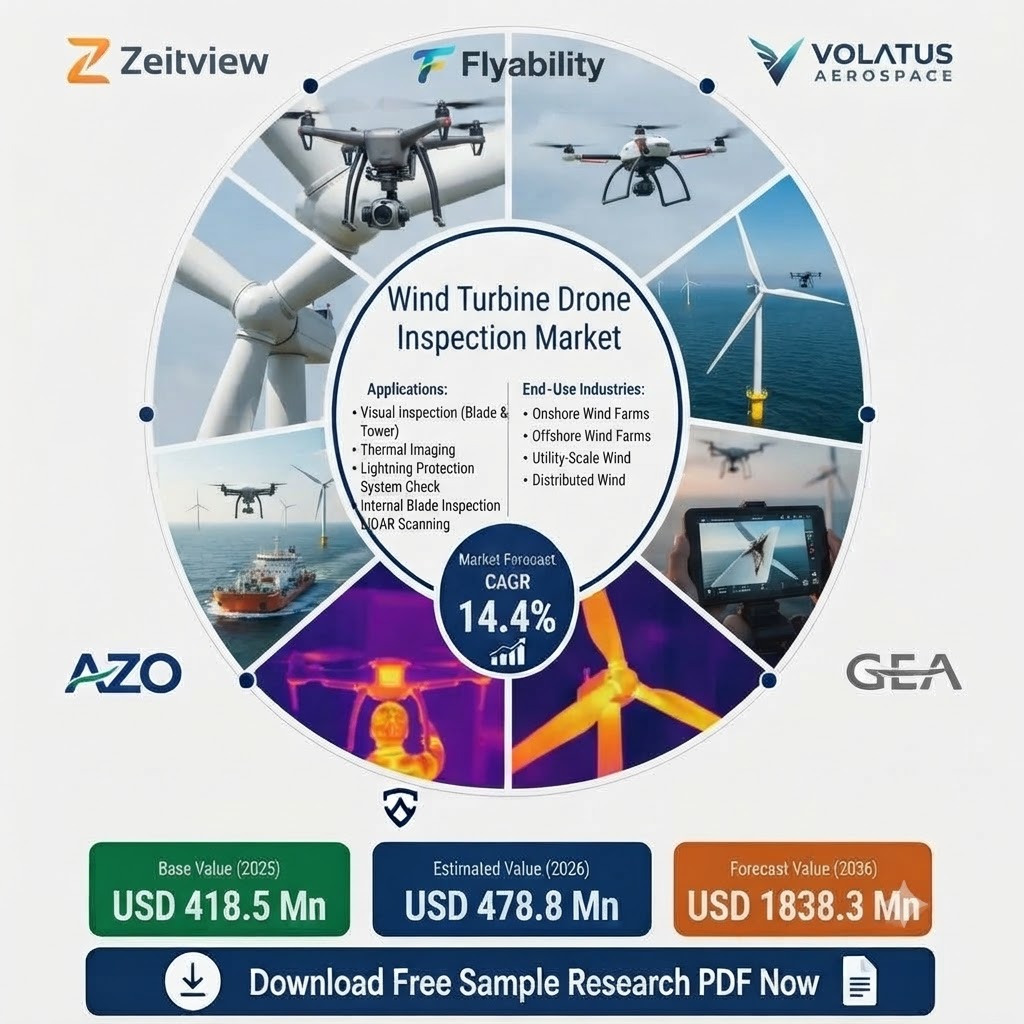
The Wind Turbine Drone Inspection Market is valued at USD 478.8 million in 2026 and is projected to reach USD 1,838.3 million by 2036, expanding at a 14.4% CAGR during the forecast period. The market is gaining momentum as wind-farm operators seek repeatable inspection methods that can assess turbine blades, nacelles, towers, and other structures while reducing reliance on difficult and time-intensive manual access. Fact.MR identifies an absolute opportunity of USD 1,359.5 million between 2026 and 2036.
Get detailed market forecasts, competitive benchmarking, and pricing trends: https://www.factmr.com/connectus/sample?flag=S&rep_id=8177
A major factor supporting adoption is the recurring need to monitor blades exposed to fatigue, erosion, weather-related damage, and lightning effects over long operating lives. Drone-based inspection enables operators to collect close-range visual and thermal information while technicians remain on the ground. The approach can also support faster maintenance planning by converting inspection imagery into structured defect records. As wind fleets expand, age, and undergo repowering, the number of turbines requiring periodic condition assessment is also increasing. Offshore wind development further strengthens demand because vessel access, technician transfers, and weather conditions can make conventional inspection more difficult and costly.
By product, Fixed Wing Drones hold the leading position, accounting for 65.4% of the market in 2026. Their longer flight endurance allows inspection teams to cover wider areas and multiple turbines with fewer launch and recovery cycles. This operating profile is particularly useful for distributed wind assets and broader site-level inspection programmes. By deployment, Onshore Wind Farms account for 46.3% of the market in 2026, supported by easier road access, simpler launch logistics, and the ability to conduct repeated inspection missions across operating fleets. Remotely Piloted systems lead the operation segment with a 55.2% share, while Blade Inspection represents 33.2% of application demand in 2026.
Germany is forecast to expand at a 13.1% CAGR through 2036. Its substantial onshore wind fleet, combined with repowering and additional capacity, creates a continuing requirement for turbine condition records. Germany had 68.1 GW of onshore wind capacity at the end of 2025, while offshore capacity reached 9.5 GW. This combination creates inspection demand from both existing assets and newly commissioned or repowered turbines.
The United Kingdom is expected to register a 12.3% CAGR through 2036, with offshore wind development providing an important source of future inspection demand. The country awarded 8.4 GW of offshore wind capacity through Contracts for Difference Allocation Round 7. As additional turbines enter operation, drone services can provide blade, nacelle, and structural assessments during suitable marine weather windows while reducing the need for direct work at height.
The USA records the highest listed country CAGR in the report at 13.9%. Its large operating wind fleet supports recurring blade condition checks, end-of-warranty assessments, and inspections associated with repowering. U.S. Department of Energy research into drone and autonomous-vision approaches for turbine blade inspection is also supporting the technical development of remote assessment workflows.
Competition spans inspection services, drone platforms, analytics, and maintenance-data workflows. Key companies profiled by Fact.MR include Zeitview, DroneDeploy, HUVRdata, Flyability, Volatus Aerospace Inc., and Percepto, alongside ABJ Drones, AeroDeploy, RES, AIRPIX, EagleNXT (senseFly), and other providers. Competitive differentiation increasingly depends on flight reliability, repeatable image capture, payload quality, defect analysis, and the ability to connect inspection findings with maintenance workflows.
With wind fleets expanding and offshore projects creating more difficult inspection environments, demand is expected to shift further toward recurring drone-enabled condition assessment rather than one-time aerial image capture. Providers that combine reliable flight operations with standardized defect reporting and maintenance-data integration are positioned to address the growing inspection requirements of wind-farm operators through 2036.
Top Trending Reports: