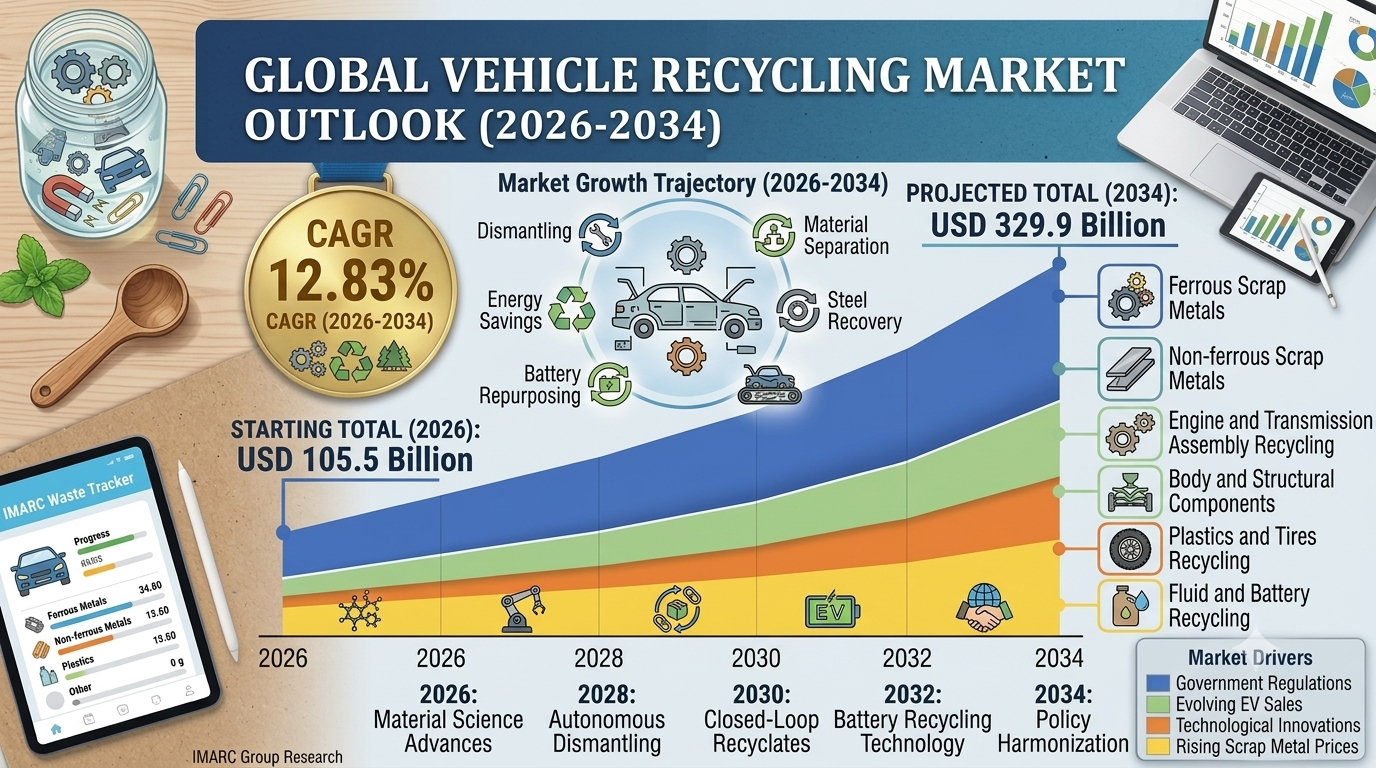
According to IMARC Group, the global vehicle recycling market size reached USD 105.5 Billion in 2025 and is projected to reach USD 329.9 Billion by 2034, expanding at a CAGR of 12.83% during 2026-2034. This robust vehicle recycling market trajectory reflects tightening end-of-life vehicle (ELV) regulations, rising demand for recycled steel and aluminum, rapid global vehicle fleet expansion, and the emergence of EV battery recycling as a high-value new revenue stream.
Vehicle Recycling Industry Overview
Vehicle recycling is the systematic disassembly of end-of-life automobiles to recover spare parts, metals, fluids, and other materials for reuse and remanufacturing. The process involves dismantling, de-pollution, crushing, shredding, and material recovery operations through which sheet metals, batteries, wheels, seats, and other components are retrieved and routed to appropriate downstream markets. Approximately 85% of vehicle components by weight are recyclable, with steel and non-ferrous metals constituting around 75% of total vehicle mass.
Vehicle recycling spans a broad continuum of activity:
- Dismantling and parts recovery: Licensed dismantlers extract reusable components ahead of shredding, supplying collision repair and aftermarket channels
- De-pollution and hazardous material handling: Removal of fluids, airbags, and batteries ahead of mechanical processing
- Shredding and metal separation: Industrial shredders and sensor-based sorting recover ferrous and non-ferrous metals at scale
- EV battery recycling: Hydrometallurgical and pyrometallurgical processing recovers lithium, cobalt, nickel, and manganese from end-of-life battery packs
- Aftermarket parts distribution: Digital platforms connect salvaged, certified parts with repair shops and consumers globally
Request a Sample Report for Detailed Vehicle Recycling Market Share Evaluation: https://www.imarcgroup.com/vehicle-recycling-market/requestsample
Global Vehicle Recycling Market Size & Key Statistics
Below are the key vehicle recycling market size statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020-2025 |
| Forecast Period | 2026-2034 |
| Vehicle Recycling Market Size in 2025 | USD 105.5 Billion |
| Market Forecast in 2034 | USD 329.9 Billion |
| Market Growth Rate (2026-2034) | 12.83% CAGR |
| Largest Region | North America (37.1% share, 2025) |
| Leading Type Segment | Passenger Cars Recycling (80.4% share, 2025) |
| Leading Material Segment | Steel (53.2% share, 2025) |
| Leading Application Segment | Aftermarket (95.1% share, 2025) |
Key Market Drivers & Vehicle Recycling Market Trends in 2026
Several powerful forces are shaping vehicle recycling market trends and fueling sustained growth expectations across the global automotive circular economy:
- Stringent ELV Regulations and Scrappage Policy Mandates
Governments across the European Union, Japan, South Korea, China, and India have enacted comprehensive end-of-life vehicle regulations mandating formal recycling and minimum recyclability thresholds. The EU ELV Directive requires 85% recyclability by weight, compelling automakers and dismantlers to invest in advanced recovery infrastructure.
- Rising Demand for Recycled Steel, Aluminum, and Non-Ferrous Metals
Escalating costs of virgin raw materials are incentivizing manufacturers to prioritize recycled feedstocks. Vehicle-derived recycled steel accounts for a substantial share of secondary steel inputs for automotive and construction manufacturers globally, reinforcing steady demand for organized dismantling and shredding capacity.
- EV Battery Recycling Boom Creating High-Value New Revenue Streams
More than 17 million electric vehicles were sold globally in 2024, generating a growing pipeline of end-of-life battery packs. EV batteries contain high-value metals, making EV recycling substantially more lucrative per unit than conventional internal-combustion vehicle processing, and is projected to grow at over 25% CAGR through 2034.
- Rapid Urbanization and Global Vehicle Fleet Expansion
The global car parc is estimated to reach approximately 1.644 billion vehicles in 2025, with emerging economies across Asia Pacific and Latin America seeing rapid motorization. This structural fleet growth directly expands the future ELV supply pipeline, underpinning long-term recycling volume growth across all major regions.
- Circular Economy Frameworks and Extended Producer Responsibility
Extended Producer Responsibility (EPR) mandates, now operative across more than 40 countries, are placing end-of-life management costs directly on vehicle manufacturers, incentivizing vehicles designed for higher recyclability. The EU's revised ELV Regulation targets 25% recycled content in new vehicles by 2030, creating unprecedented downstream demand for certified recycled automotive-grade materials.
- Digital Transformation of Aftermarket Parts Trading
Digital auction and marketplace platforms are expanding global buyer reach for certified salvage parts, improving price realization and inventory turnover for dismantlers. AI-powered computer vision systems are increasingly used to identify, condition-assess, and price recovered components in seconds rather than minutes.
- Advanced Material Separation and Shredding Technology
Next-generation separation technologies, including sensor-based optical sorting, laser ablation, and advanced eddy current systems, are enabling recyclers to achieve higher non-ferrous metal recovery rates from shredder output, with facilities adopting advanced separation technology reporting 15-25% improvements in revenue per ton of processed material.
Key Market Segmentation
By Type
Passenger Cars Recycling — Largest Segment: Passenger cars recycling dominates the type segment with an 80.4% share in 2025, driven by the overwhelming size of the global passenger vehicle fleet and the comparatively shorter average service life of passenger automobiles. India's end-of-life vehicle volumes alone are projected to grow from nearly 23 million in 2025 to around 50 million by 2030.
Commercial Vehicles Recycling: Commercial vehicles recycling accounts for 19.6% of market share, delivering disproportionately high metal recovery volumes per unit due to larger structural mass, making commercial ELVs particularly valuable inputs for secondary metal processors.
By Material
Steel — Largest Segment: Steel leads the material segment with a 53.2% share in 2025, reflecting its dominant role in vehicle body and chassis construction and its high recyclability relative to composite and polymer materials.
Aluminium, Rubber, Copper, Glass, Plastic, and Others: These materials collectively make up the balance of recovered vehicle mass, with aluminium recovery gaining importance as automakers increase lightweighting content in new vehicle design.
By Application
Aftermarket — Largest Segment: The aftermarket segment dominates application demand with a 95.1% share in 2025, reflecting massive global demand for cost-effective recycled spare parts offering 40-70% cost savings versus new OEM components.
OEMs: The OEMs segment accounts for 4.9% of the market but is the fastest-growing application, as the EU's End-of-Life Vehicle regulation — which includes a minimum 15% recycled content requirement within six years — creates structured, long-term procurement contracts between automakers and certified recycled material suppliers.
Regional Vehicle Recycling Market Analysis
| Region | Share (2025) | Key Growth Drivers | Major Companies |
| North America | 37.1% | Mature ELV infrastructure; large aging vehicle fleet; strong aftermarket demand | LKQ, Radius Recycling, Sims Limited |
| Asia Pacific | 28.6% | China & India scrappage policies; EV battery recycling surge; rapid fleet growth | Keiaisha Co., Toyota Metal |
| Europe | 22.4% | EU ELV Directive compliance; circular economy targets; advanced shredder residue recovery | INDRA, Hensel Recycling, Scholz, ASM Auto |
| Latin America | 7.3% | Growing vehicle parc; informal sector formalization; Brazil & Mexico policy development | Regional operators; Sims Limited |
| Middle East & Africa | 4.6% | Rising vehicle imports driving ELV volumes and circular economy policy adoption | Local dismantlers; emerging formal operators |
North America leads the global vehicle recycling market share at 37.1% in 2025, underpinned by the United States' highly organized network of licensed dismantlers and shredder operators, comprehensive ELV regulatory frameworks, and more than 290.9 million registered vehicles with an average age of 12.8 years.
Asia Pacific represents the fastest-growing regional market, driven by China's rapidly maturing ELV policy framework and a fleet exceeding 300 million registered vehicles, India's Vehicle Scrappage Policy catalyzing registered vehicle scrapping facility construction, and Japan and South Korea's advanced recycling technology deployment.
Connect for Detailed Vehicle Recycling Market Share Segmentation Analysis — Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=1907&flag=C
Leading Players in the Global Vehicle Recycling Industry
The global vehicle recycling market exhibits a moderately consolidated competitive structure, with the top players collectively accounting for approximately 35-40% of organized global recycling revenues in 2025. Key companies covered in the IMARC Group report include:
| Company | Brand / Core Assets | Competitive Strength |
| LKQ Corporation | LKQ / Euro Car Parts | North America's largest aftermarket parts supplier; global salvage network |
| Radius Recycling, Inc. | Radius Recycling / Pick-N-Pull | US scrap metal processing leader; significant ferrous & non-ferrous recovery |
| Sims Limited | Sims Limited | Global metals recycler; advanced ELV shredding and downstream processing |
| ASM Auto Recycling Ltd. | ASM Auto Recycling | UK-certified green dismantling, de-pollution, and parts re-use specialist |
| INDRA | INDRA Automobile Recycling | European ELV dismantling pioneer; France, Spain, Portugal network |
| Hensel Recycling Group | Hensel Recycling | German multi-material recycler; non-ferrous metal recovery specialist |
| EcoBat | EcoBat | One of the world's largest lead-acid battery recyclers; ELV battery specialist |
| Keiaisha Co. Ltd. | Keiaisha | Japan-based ELV specialist; advanced hazardous material removal technology |
| Scholz Recycling GmbH | Scholz | European multi-material recycler; automotive scrap processing & steel trading |
Latest Vehicle Recycling Market Industry Developments
November 2024 — Tata Motors and Tata International
Tata Motors and Tata International launched Re.Wi.Re, an advanced Registered Vehicle Scrapping Facility (RVSF) in Pune, reflecting the accelerating momentum behind organized vehicle recycling investment across emerging economies under India's Vehicle Scrappage Policy.
2024 — LKQ Corporation
LKQ North America partnered with Tractable to deploy AI-powered computer vision technology that analyzes vehicle damage and identifies reusable parts, helping accelerate and optimize salvage vehicle recycling and digital inventory accuracy.
FY2024 — Radius Recycling, Inc.
Radius Recycling commissioned a new advanced shredder line, increasing non-ferrous recovery capacity by approximately 15%, while expanding its Pick-N-Pull self-service parts stores in growing Sun Belt markets across the United States.
2024 — Sims Limited
Sims Limited advanced its digital trading platform for improved scrap procurement and sales, and invested in sensor-based non-ferrous sorting upgrades across multiple North American facilities to strengthen material recovery yields.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Automotive, Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104