Market Overview
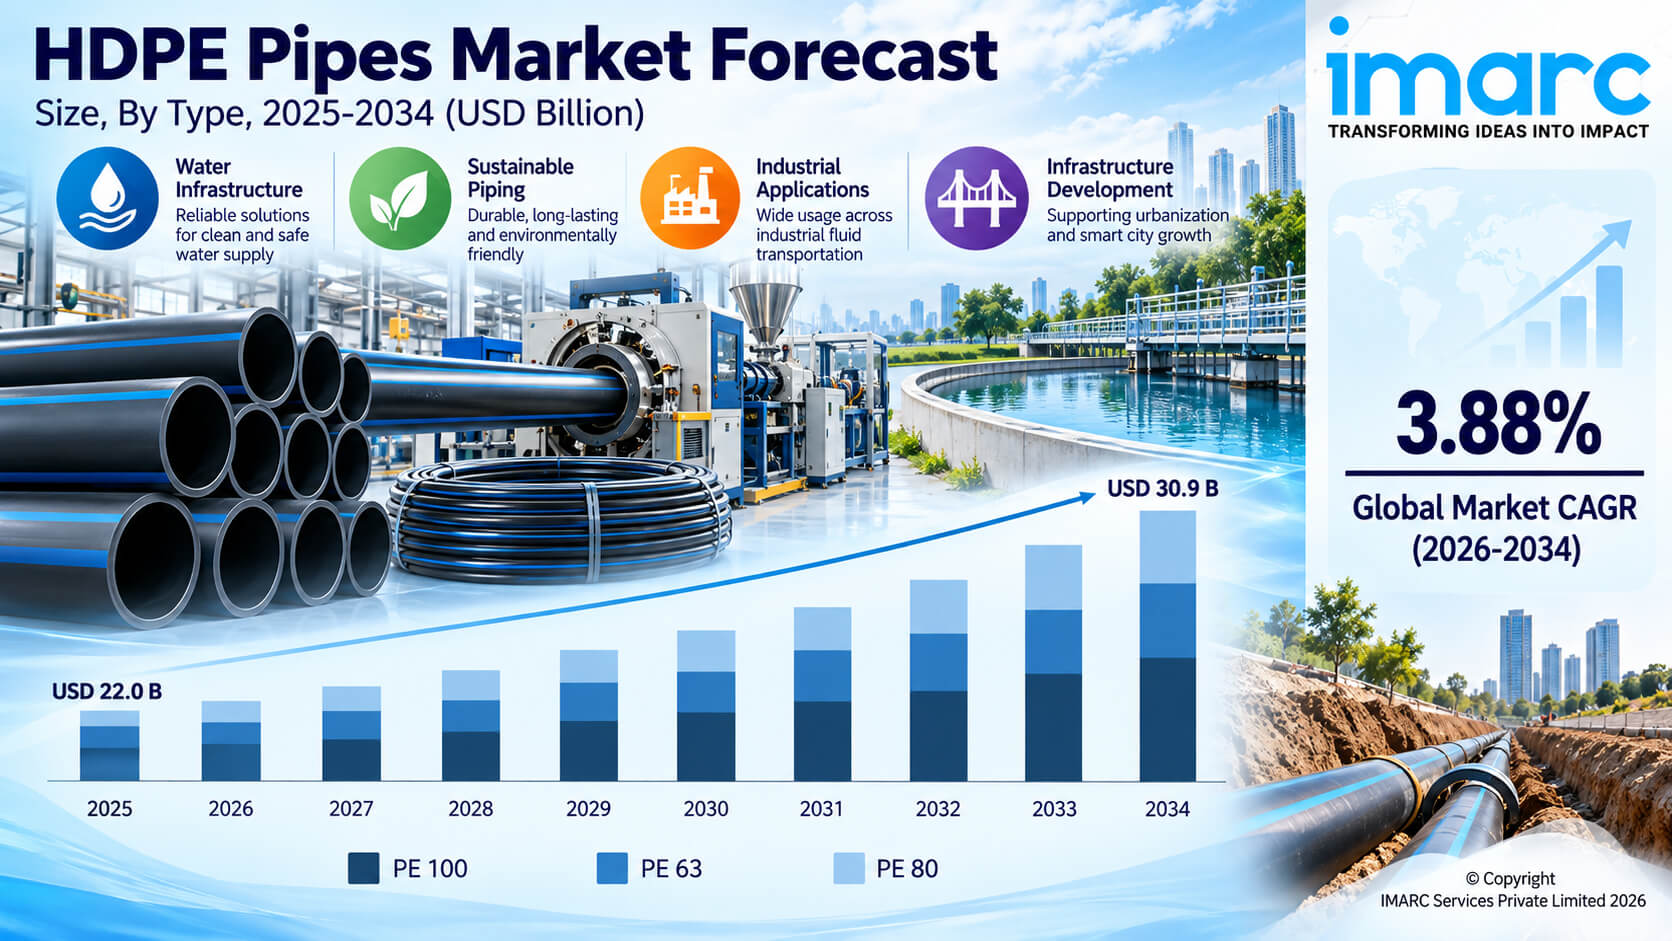
According to a research report by IMARC Group, the global HDPE pipes market size was valued at USD 22.0 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 30.9 Billion by 2034, exhibiting a growth rate (CAGR) of 3.88% during 2026-2034. Asia Pacific currently dominates the market, holding a significant market share of over 44.1% in 2025. This dominance can be attributed to rapid urbanization, large-scale infrastructure development, and extensive agricultural activities requiring efficient irrigation systems. Government investments in water supply, sewage networks, and industrial projects, particularly in China and India, drive high demand, supported by cost-effective manufacturing and expanding construction sectors.
HDPE Pipes Market Key At a Glance
-
Base Year: 2025
-
Historical Period: 2020–2025
-
Forecast Period: 2026–2034
-
Market Size (2025): USD 22.0 Billion
-
Market Forecast (2034): USD 30.9 Billion
-
CAGR (2026–2034): 3.88%
-
Leading Region: Asia Pacific
-
Asia Pacific Market Share (2025): Over 44.1%
-
Dominant Type: PE 100
-
Leading Application: Sewage System Pipe
Request for a Sample Report for Detailed Evaluation: https://www.imarcgroup.com/hdpe-pipes-market/requestsample
HDPE Pipes Market Report: Key Highlights
-
Market Size & Growth: The global HDPE pipes market was valued at USD 22.0 Billion in 2025 and is projected to reach USD 30.9 Billion by 2034, registering a CAGR of 3.88% during 2026–2034, according to IMARC Group.
-
Regional Leadership: Asia Pacific represents the largest regional market, accounting for over 44.1% of the market share in 2025, supported by rapid urbanization, infrastructure development, agricultural irrigation requirements, and government investments in water and sewage networks.
-
By Type: The market is segmented into PE 63, PE 80, and PE 100, with PE 100 representing the largest segment and accounting for around 68.6% of the market in 2025.
-
By Application: The market covers oil and gas pipes, agricultural irrigation pipes, water supply pipes, sewage system pipes, and others, with sewage system pipes representing the largest application segment and holding around 40.5% of the market in 2025.
-
Key Market Drivers: Rising investments in infrastructure development, increasing water conservation initiatives, expanding mining activities, growing agricultural irrigation requirements, and modernization of water and sewage networks.
-
Key Market Trends: Increasing adoption of durable and corrosion-resistant piping systems, growing investments in water infrastructure, rising demand for efficient irrigation solutions, expansion of mining activities, and increasing use of trenchless pipe-laying technologies.
-
Key Market Opportunities: Infrastructure modernization, sustainable water management, agricultural irrigation development, mining applications, renewable energy infrastructure, and the growing use of recycled plastics in pipe production.
-
Key Market Challenges: Meeting evolving infrastructure requirements while maintaining product quality, durability, cost efficiency, and environmental sustainability.
What Is Driving HDPE Pipes Market Growth in 2026?
Growing Investments in Infrastructure Development
Increasing investments in infrastructure development are positively influencing the growth of the global HDPE pipes market. Rising expenditure on transportation networks, water supply systems, wastewater and sewage infrastructure, and urban and rural development projects is generating substantial demand for durable, reliable, and cost-effective piping solutions.
HDPE piping offers several performance advantages, including high strength, corrosion and chemical resistance, flexibility, leak resistance, and extended service life. These properties make HDPE pipes particularly suitable for critical applications such as potable water distribution, irrigation, wastewater management, and underground utility networks. Growing investments in water infrastructure are further accelerating demand for HDPE water pipe systems, particularly in regions focused on expanding access to safe and reliable water supplies.
Government-led infrastructure initiatives are also creating favorable growth opportunities. For example, India's Jal Jeevan Mission (JJM), which aims to provide functional tap water connections to rural households, has significantly increased investment in rural water infrastructure. In March 2023, India's Ministry of Jal Shakti also highlighted plans to invest more than USD 240 billion in the water sector, underscoring the country's long-term focus on water resource development.
The ongoing expansion of water distribution networks, groundwater management programs, dam rehabilitation projects, irrigation systems, and sanitation infrastructure is therefore supporting the adoption of HDPE pipes and fittings across developing economies. In addition, the growing focus on specialized piping materials and applications, including polyurethane pipe solutions, is encouraging manufacturers to expand their product portfolios to address diverse infrastructure requirements.
Rising Number of Water Conservation Initiatives
The growing awareness about water scarcity and the increasing need for responsible water management practices are leading to higher investments in water infrastructure projects. Governments across various economies are implementing initiatives focused on water conservation, recycling, efficient distribution, and irrigation management, which is strengthening demand for HDPE piping solutions.
For instance, in May 2024, the U.S. Department of the Interior announced that the President's initiative would provide an initial USD 700 Million for long-term water conservation initiatives throughout the Lower Colorado River Basin. The investment is expected to support initiatives including desalination, groundwater banking, water recycling, canal lining, turf removal, advanced metering infrastructure, water distribution structures, and farm efficiency enhancements.
Similarly, in January 2023, the agricultural minister of Jharkhand, India, launched a major water conservation initiative involving the renovation of approximately 2,133 ponds and the construction of 2,795 percolation tanks across all 24 blocks. Such initiatives are increasing the need for reliable piping infrastructure for water distribution and management, thereby contributing to HDPE pipes market growth.
Increasing Mining Activities
The increasing mining activities are supporting the growth of the HDPE pipes market. HDPE pipes are increasingly used in mining operations due to their durability, corrosion resistance, flexibility, lightweight characteristics, and resistance to chemicals and abrasion.
HDPE pipes are suitable for several mining applications, including tailings management, mine drainage, and slurry conveyance. Their ability to withstand harsh operating environments and ground movement makes them an effective solution for mining infrastructure.
The ongoing expansion of mining exploration and extraction activities, particularly in resource-rich regions, is further creating demand for efficient and reliable piping systems. For example, in June 2024, Metallis Resources commenced its Phase 1 exploration campaign at the Greyhound property, a high-grade silver, gold, and antimony prospect in Idaho, United States. In addition, Deccan Gold Mines Ltd. received a Rs 60 Crore investment commitment in June 2024 to develop the Jonagiri Gold Project in India and the Altyn Tor Gold Project in Kyrgyzstan. The continued investment in mining projects is consequently supporting demand for HDPE pipes.
Rising Demand for Efficient Agricultural Irrigation Systems
The growing focus on agricultural productivity and efficient water utilization is creating additional demand for HDPE pipes. Developing economies are increasingly investing in irrigation infrastructure to improve water distribution and address drought-related challenges.
India's irrigation systems market is projected to grow at a CAGR of 10.9% from 2023 to 2028. The country has approximately 8.26 million hectares of irrigated crop area, representing the largest such area globally, while its 159.7 million hectares of arable land represents the second-largest globally. The Pradhan Mantri Krishi Sinchai Yojana (PMKSY) has allocated USD 7.7 Billion to develop irrigation infrastructure and improve drought resilience.
The increasing number of agricultural infrastructure projects is creating opportunities for HDPE pipes due to their flexibility, durability, lightweight characteristics, and resistance to corrosion. These properties make them suitable for irrigation networks across varying terrains and demanding agricultural environments.
HDPE Pipes Market Segmentation Analysis
By Type
-
PE 63
-
PE 80
-
PE 100
PE 100 represents the largest type segment in the global HDPE pipes market, accounting for around 68.6% of the market in 2025. PE 100 HDPE pipes are manufactured using PE 100-grade HDPE resin and are known for their high strength-to-density ratio, durability, and ability to withstand internal and external pressure.
These pipes are suitable for transporting different types of chemicals and fluids without significant degradation or contamination. Their lightweight characteristics make them easier to handle, transport, and install compared with many conventional pipe materials. In addition, their flexibility allows them to bend and adapt to varying terrain and ground movement, reducing the risk of damage during installation.
The increasing demand for high-performance piping systems across water distribution and infrastructure applications is supporting the leading position of PE 100 pipes. For instance, in March 2023, SCG Chemicals launched "SCGC PE100RC," a plastic resin designed for HDPE pipes used in water distribution infrastructure systems.
By Application
-
Oil and Gas Pipe
-
Agricultural Irrigation Pipe
-
Water Supply Pipe
-
Sewage System Pipe
-
Others
Sewage system pipes dominate the market, accounting for around 40.5% of the market in 2025. Their leading position can be attributed to their superior durability, corrosion resistance, and flexibility, which make HDPE pipes suitable for transporting wastewater under harsh conditions.
HDPE pipes can withstand ground movement and chemical exposure, supporting long-term performance in sewage infrastructure. Their leak-free joints can help reduce contamination risks and maintenance requirements. As urbanization increases and municipalities modernize aging drainage and sewage systems, demand for reliable wastewater infrastructure is rising.
The lightweight nature of HDPE pipes also simplifies transportation and installation, supporting their adoption in large-scale sewage projects. These characteristics collectively position sewage system pipes as the leading application segment in the global HDPE pipes market.
By Region
-
North America
-
United States
-
Canada
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Indonesia
-
Others
-
-
Europe
-
Germany
-
France
-
United Kingdom
-
Italy
-
Spain
-
Russia
-
Others
-
-
Latin America
-
Brazil
-
Mexico
-
Others
-
-
Middle East and Africa
Asia Pacific accounted for the largest market share of over 44.1% in 2025. The region's leading position is supported by increasing investments in infrastructure improvement and development, rapid urbanization, expanding construction activities, and growing demand for water and sewage infrastructure.
The increasing focus on improving existing sewage systems and gas distribution networks is also contributing to market growth. In addition, the demand for lightweight and cost-effective pipes that can be transported and installed efficiently is supporting the adoption of HDPE pipes.
Growing investments in water supply systems and agricultural irrigation infrastructure are further strengthening regional demand. For instance, in October 2023, Supreme Industries Ltd., a plastics product manufacturer based in India, acquired Parvati Agro Plast, a specialized PVC pipe manufacturer, to expand its portfolio of PVC-O pipes, HDPE pipes, rigid PVC pipes, and DWC pipes ranging from 20 to 500 mm in thickness.
Key Regional Insight: Asia Pacific's Strategic Position
Asia Pacific's leading position in the global HDPE pipes market is anchored in rapid urbanization, large-scale infrastructure development, expanding agricultural activities, and increasing government investments in water and sewage networks.
China and India represent important markets in the region due to their large populations, expanding construction sectors, and extensive infrastructure requirements. Growing demand for efficient irrigation systems, modernization of water supply networks, and improvements in sewage infrastructure are creating sustained opportunities for HDPE pipe manufacturers.
The region's cost-effective manufacturing capabilities and expanding industrial base further support its strategic position in the global market.
United States HDPE Pipes Market Analysis
In 2025, the United States accounted for 78.3% of the North American market. The country's HDPE pipes market is being supported by significant investments in infrastructure development, particularly in water and sewage systems.
Aging water and sewage pipelines are increasingly being replaced with HDPE pipes due to their durability and corrosion resistance. Infrastructure development projects are prioritizing sustainable and long-lasting materials, creating demand for HDPE piping solutions.
For instance, a series of bills passed by Congress are expected to direct more than USD 1.2 Trillion toward modernizing U.S. infrastructure between 2021 and 2030. Government-backed funding and public-private partnerships are also supporting infrastructure development across transportation and utility networks.
The flexibility and performance of HDPE pipes make them suitable for large-scale infrastructure projects, while environmental regulations and the need to reduce maintenance costs are further contributing to their adoption.
North America HDPE Pipes Market Analysis
The North American HDPE pipes market is driven by extensive infrastructure development, growing municipal investments in water and wastewater management, and increasing demand across agricultural and industrial sectors.
The region's emphasis on sustainable piping solutions has accelerated the adoption of HDPE pipes due to their corrosion resistance, durability, flexibility, and low maintenance requirements. The United States leads regional demand, supported by government funding for sewer rehabilitation and water supply upgrades.
Rising awareness of water conservation and efficient irrigation systems is also supporting demand. In the oil and gas sector, HDPE pipes are increasingly used due to their strength and flexibility. With continued efforts to replace aging metal pipelines, sewage and drainage applications remain important areas of demand.
For instance, in April 2025, Tianjin Jingtong Pipeline Technology Co., Ltd. successfully exported 10 x 40HQ containers of HDPE pipes to North America, reflecting continued expansion into international markets and sustained demand for HDPE piping solutions.
Asia Pacific HDPE Pipes Market Analysis
Asia Pacific is experiencing significant HDPE pipe adoption due to increasing investment in smart city projects and efforts to modernize urban infrastructure. According to the Ministry of Housing & Urban Affairs India, the Smart Cities Mission, involving 100 cities, had completed 7,380 out of 8,075 projects as of December 2024, with investments of approximately ₹1.47 lakh crore.
Governments and private entities are investing in upgrading sewage systems, gas distribution networks, water supply infrastructure, and other urban utilities. HDPE pipes offer lightweight, corrosion-resistant, and easy-to-install solutions for these applications.
The integration of smart technologies into urban infrastructure is also increasing demand for high-performance piping materials. As smart city projects expand across densely populated urban areas, the need for efficient and reliable pipeline infrastructure is expected to continue supporting HDPE pipe adoption.
Europe HDPE Pipes Market Analysis
Europe is increasingly adopting HDPE pipes in response to growing water conservation initiatives and the need to modernize water distribution infrastructure.
Under Cohesion Policy Programmes for 2021–2027, USD 18.25 Billion of investment is planned to support access to water and sustainable water management, including more than USD 14.26 Billion in EU funding. Environmental awareness and regulatory pressure to reduce water losses in distribution networks are encouraging the adoption of advanced piping solutions.
HDPE pipes are preferred for their leak-resistant joints and resistance to chemicals and environmental stress, making them suitable for water conservation applications. Governments and municipal authorities are replacing outdated water systems to improve efficiency and reduce maintenance requirements.
The growing deployment of rainwater harvesting and wastewater recycling systems is also supporting demand for HDPE pipes, while the region's focus on sustainable infrastructure and resource management is expected to support long-term adoption.
Latin America HDPE Pipes Market Analysis
Latin America is witnessing growing HDPE pipe adoption due to increasing mining activities across the region. The region accounts for approximately 48% of the world's copper reserves, 20% of global gold reserves, more than 60% of lithium reserves, and around 50% of silver reserves.
Mining operations require durable piping systems for transporting slurry, water, and chemicals. HDPE pipes are suitable for these applications due to their resistance to abrasion, corrosion, and environmental stress.
As mining exploration and extraction activities continue to expand, demand for reliable and low-maintenance piping systems is increasing. This is contributing to higher adoption of HDPE pipes across mining extraction and processing facilities.
Middle East and Africa HDPE Pipes Market Analysis
The Middle East and Africa are witnessing increased HDPE pipe adoption due to growing construction activities. Saudi Arabia, in particular, is experiencing significant construction sector expansion, with more than 5,200 projects underway and valued at approximately USD 819 Billion.
Expanding urban development and infrastructure projects require efficient piping systems for water supply, drainage, sewage, and gas distribution. HDPE pipes are favored for their strength, flexibility, lightweight characteristics, and ease of installation.
Their ability to withstand demanding environmental conditions further supports their application across construction projects. As urban development and infrastructure investments continue, demand for HDPE piping solutions is expected to increase across the region.
Competitive Landscape in the HDPE Pipes Industry
Leading HDPE pipe manufacturers are investing in research and development to create advanced products with improved strength, chemical resistance, abrasion resistance, and temperature tolerance. Companies are also maintaining strict quality control measures throughout manufacturing to comply with industry standards and meet customer requirements.
Market participants are expanding production capacity and distribution networks to serve growing demand across emerging and developed markets. The establishment of new manufacturing facilities and distribution centers is supporting broader geographic reach.
Mergers and acquisitions are also being adopted by leading companies to consolidate market positions, acquire new technologies, and enter new markets. In addition, manufacturers are increasingly adopting environmentally sustainable practices, reducing their carbon footprint, and incorporating recycled materials into their products in response to environmental regulations and customer preferences.
Key HDPE Pipes Market Players Include:
-
Advanced Drainage Systems
-
Apollo Pipes Ltd.
-
Atkore
-
Chevron Phillips Chemical Company LLC
-
China Lesso Group Holdings Limited
-
Jain Irrigation Systems Limited
-
JM Eagle Inc.
-
Lane Enterprises Inc.
-
Nan Ya Plastics Corporation
-
Prinsco, Inc.
-
PTT Global Chemical Public Company Limited
-
The Supreme Industries Ltd.
-
WL Plastics
Latest News and Developments:
-
November 2024: BASF introduced its new High-Density Polyethylene (HDPE) brand, Easiplas™, and marked key construction milestones at its HDPE plant within the Zhanjiang Verbund site, including the installation of major equipment such as a reactor and product purge bin.
-
November 2024: Fortress Investment Group acquired Infra Pipe Solutions (IPS), a North American manufacturer of HDPE pipes and structures. IPS is known for brands including Sclairpipe®, Weholite®, Endopure®, and Enduct®.
-
April 2024: AmeriTex Pipe & Products initiated construction of a new facility in Conroe, Texas, to expand its footprint in the HDPE and PP corrugated pipe market. The facility is designed to increase production capacity and logistical efficiency for stormwater and drainage systems.
Market Drivers, Challenges & Opportunities
Major Market Drivers:
-
Infrastructure Development: Rising investments in water supply, sewage, urban development, and other infrastructure projects are increasing demand for durable piping systems.
-
Water Conservation Initiatives: Growing concerns about water scarcity and the need for efficient water management are supporting investments in modern piping infrastructure.
-
Increasing Mining Activities: Expanding mining exploration and extraction projects are creating demand for corrosion-resistant and durable HDPE piping solutions.
-
Agricultural Irrigation Development: Increasing investments in irrigation infrastructure are supporting demand for flexible and efficient HDPE pipes.
-
Urbanization: Rapid urbanization is increasing the need for modern water distribution, sewage, drainage, and utility networks.
Key Challenges:
-
Infrastructure Requirements: Manufacturers need to continuously meet changing performance requirements across diverse water, industrial, agricultural, and infrastructure applications.
-
Sustainability Requirements: Increasing environmental regulations and demand for sustainable products require manufacturers to adopt recycled materials and environmentally responsible production practices.
-
Competitive Market Environment: Manufacturers face pressure to maintain product quality and technological performance while offering cost-effective solutions.
Emerging Opportunities:
-
Trenchless Pipe-Laying Technologies: The growing shift toward trenchless installation methods is encouraging the use of flexible and lightweight HDPE systems.
-
Sustainable Piping Solutions: Increasing government mandates promoting sustainable infrastructure and the use of recycled plastics are creating opportunities for environmentally focused HDPE products.
-
Water Infrastructure Modernization: Aging water and sewage networks across developed economies are creating significant replacement and rehabilitation opportunities.
-
Agricultural Irrigation: Expanding irrigation infrastructure in developing economies is creating new demand for HDPE pipes.
-
Mining Infrastructure: Continued investment in mining exploration and extraction is opening opportunities for specialized HDPE piping applications.
HDPE Pipes Market FAQs
1. What is the current size of the HDPE pipes market?
The global HDPE pipes market was valued at USD 22.0 Billion in 2025 and is expected to grow at a CAGR of 3.88% during 2026-2034, reaching USD 30.9 Billion by 2034.
2. What is driving the growth of the HDPE pipes market?
The market is driven by rising investments in infrastructure development, increasing water conservation initiatives, expanding mining activities, growing agricultural irrigation requirements, modernization of water and sewage networks, and increasing demand for durable and corrosion-resistant piping systems.
3. Which region dominates the HDPE pipes market?
Asia Pacific leads the global HDPE pipes market, accounting for over 44.1% of the market share in 2025. Rapid urbanization, infrastructure development, agricultural activities, and government investments in water and sewage networks are supporting the region's leading position.
4. Which segment holds the largest share in the HDPE pipes market?
PE 100 represents the largest type segment, accounting for around 68.6% of the market in 2025. By application, sewage system pipes represent the largest segment, holding around 40.5% of the market in 2025.
5. What are the key trends in the HDPE pipes market?
Key trends include growing investments in infrastructure development, rising water conservation initiatives, increasing mining activities, expanding agricultural irrigation infrastructure, growing adoption of trenchless pipe-laying technologies, and increasing use of recycled plastics in pipe production.
Conclusion: HDPE Pipes Market Outlook to 2034
The global HDPE pipes market is set for steady growth through 2034, underpinned by rising infrastructure investments, increasing water conservation initiatives, expanding mining activities, growing agricultural irrigation requirements, and the modernization of water and sewage networks.
The superior durability, flexibility, corrosion resistance, chemical resistance, lightweight characteristics, and long service life of HDPE pipes are supporting their adoption across water supply, sewage, irrigation, mining, oil and gas, and other industrial applications. The growing shift toward trenchless installation technologies and sustainable infrastructure is further creating opportunities for market participants.
With Asia Pacific maintaining its position as the leading regional market and North America, Europe, Latin America, and the Middle East and Africa offering additional growth avenues, the outlook through 2034 remains positive. Companies that invest in advanced HDPE products, expanded production capabilities, sustainable manufacturing practices, and innovative infrastructure solutions will be well positioned to capture opportunities as global demand for durable and efficient piping systems continues to expand.
About the Author:
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Energy and Mining, Construction and Manufacturing, Automotive, Chemicals and Materials, and more.
Media & Sales Contact:
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104