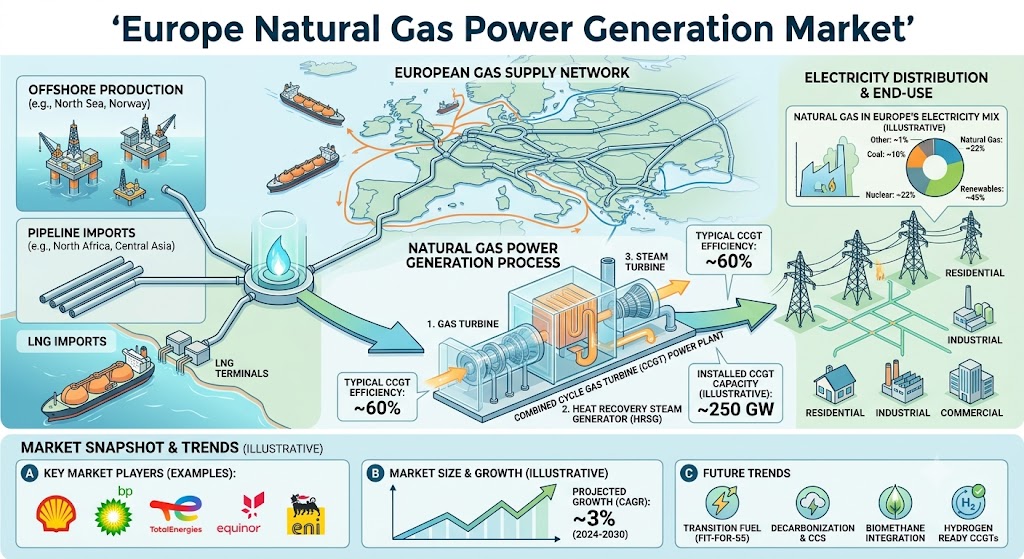
Europe’s natural gas power generation sector is developing within a competitive electricity market where utilities, independent power producers, technology suppliers, infrastructure companies, and financial investors are reassessing their strategies. Renewable generation and storage are expanding rapidly, but flexible thermal capacity continues to offer system services that cannot always be replaced immediately. This creates a market in which competitive positioning depends on efficiency, location, flexibility, financing, and the ability to adapt to changing energy policies.
For generation companies, operational performance is becoming a major differentiator. Efficient plants can reduce fuel consumption and carbon exposure, while flexible equipment can respond to price signals and grid requirements. Facilities capable of rapid ramping and reliable starts may capture additional value from balancing markets. As utilization patterns change, plant availability and response capability can become as important as annual electricity production.
Technology providers have opportunities across the asset lifecycle. Turbine upgrades, digital controls, predictive maintenance, emissions monitoring, cybersecurity, and performance analytics can help operators improve existing facilities. Service providers that combine engineering expertise with data-driven optimization may become increasingly important as owners seek to extend asset life while controlling capital expenditure.
Infrastructure companies also have a significant role. Gas generation depends on pipeline networks, storage facilities, LNG terminals, transmission connections, and other supporting infrastructure. Projects that improve fuel flexibility or strengthen grid access can enhance the strategic value of generation assets. However, infrastructure investments must consider long-term demand uncertainty because Europe’s decarbonization pathway may gradually reduce fossil-fuel consumption.
Financing conditions will influence future project development. New gas generation can face longer-term policy and utilization risks, making lenders and investors more attentive to contracted revenues, capacity payments, fuel arrangements, and asset flexibility. Existing plants with established infrastructure may have different risk profiles from greenfield projects. This distinction can shape acquisition strategies, refinancing decisions, and portfolio management.
Market competition is also expanding beyond conventional thermal generation. Battery storage can provide rapid response and increasingly compete for ancillary-service revenues. Demand response can reduce peak requirements, while pumped storage and interconnection can shift electricity across periods and regions. Gas plants therefore need to demonstrate value that complements rather than simply duplicates these resources.
Environmental performance will increasingly influence competitive positioning. Carbon pricing, emissions standards, methane concerns, and corporate sustainability objectives can affect operating economics and investment decisions. Companies that improve efficiency and prepare assets for lower-carbon fuels may be better positioned than operators relying on aging technology. Clear transition strategies can also improve stakeholder confidence and financing prospects.
Regional differences create additional opportunities. Power markets vary in renewable penetration, capacity mechanisms, grid constraints, gas infrastructure, and industrial demand. A generation asset that appears marginal in one country may provide valuable reliability services in another. Investors and suppliers therefore need country-level and regional analysis rather than treating Europe as a single homogeneous market.
The Europe Natural Gas Power Generation Market Share perspective can help businesses assess competitive positioning, demand conditions, and the relative role of major generation technologies. However, market share should be considered alongside installed capacity, utilization, efficiency, technology age, geographic exposure, and revenue structure.
Future opportunities are likely to favor companies that can connect conventional generation expertise with emerging flexibility technologies. Hybrid strategies involving gas generation, batteries, renewable power, and advanced energy management could become increasingly attractive where grid constraints and reliability requirements justify them.
Ultimately, Europe’s gas generation market is moving toward selective competition rather than straightforward expansion. Efficient assets, strategic locations, modern technology, and diversified revenue models can support resilience, while inefficient facilities may face increasing pressure. Businesses that anticipate regulation, invest in flexibility, and understand regional needs will be better positioned as Europe transforms strategically.