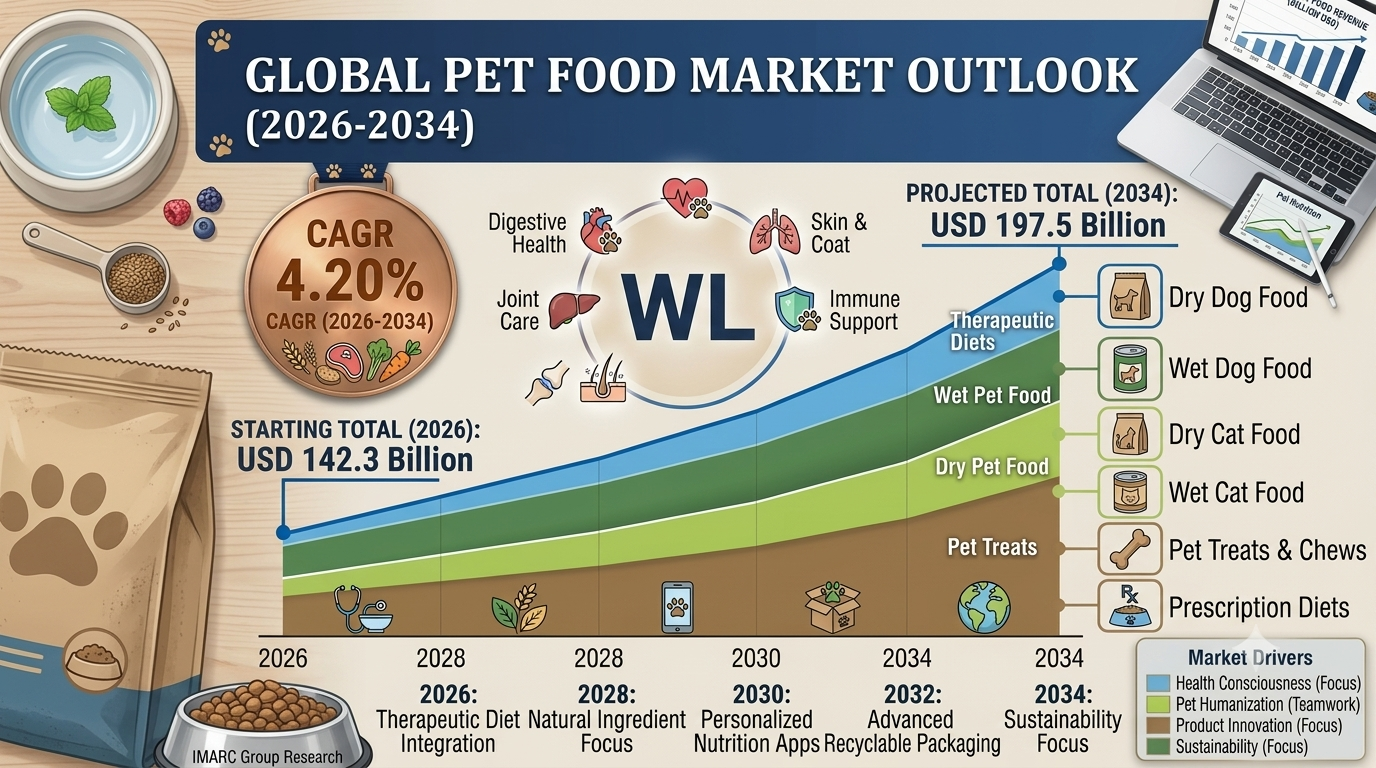
According to IMARC Group, the global pet food market was valued at USD 136.6 Billion in 2025 and is projected to reach USD 197.5 Billion by 2034, expanding at a CAGR of 4.20% during 2026–2034. This sustained pet food market growth reflects rising pet ownership rates, premiumization trends, accelerating e-commerce adoption, and growing consumer awareness of the link between diet and long-term pet health.
Pet Food Industry Overview
The pet food industry sits at the intersection of animal nutrition science, consumer goods retail, and rapidly evolving lifestyle trends. Pet food encompasses all commercially produced products designed to meet the dietary needs of domesticated animals — primarily dogs and cats — across their various life stages, from puppyhood and kittenhood through senior years.
The modern industry offers a diverse product portfolio spanning dry kibble, wet and canned food, raw and freeze-dried options, snacks, treats, and functional foods targeting specific health conditions such as joint support, digestive health, and skin and coat improvement. These products are distributed through an extensive network of supermarkets, specialty pet stores, veterinary clinics, and a rapidly expanding e-commerce ecosystem.
Key product categories within the pet food market include:
By Pet Type: Dog food, cat food, and food for other pets (birds, fish, small animals)
By Product Type: Dry pet food, wet and canned pet food, snacks and treats
By Pricing: Mass-market products and premium/specialized products
By Ingredient: Animal-derived formulations and plant-derived alternatives
By Channel: Supermarkets and hypermarkets, specialty stores, online platforms, and others
The industry is witnessing particularly strong momentum in the premium segment as consumers increasingly seek out organic, grain-free, high-protein, and breed-specific formulations that mirror the nutritional standards of human food.
Global Market Overview & Pet Food Market Size Statistics
Below are the key pet food market size statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020–2025 |
| Forecast Period | 2026–2034 |
| Market Size in 2025 | USD 136.6 Billion |
| Market Forecast in 2034 | USD 197.5 Billion |
| Market Growth Rate (2026–2034) | 4.20% CAGR |
| Largest Region | North America (42.5%+ share) |
Request for a Sample Report for Detailed Market Insights Evaluation: https://www.imarcgroup.com/pet-food-market/requestsample
Key Market Drivers & Trends in 2026
Several powerful forces are shaping the pet food market share landscape and driving consistent growth expectations across global markets:
- Increasing Pet Ownership and the Humanization of Pets
Rising pet adoption rates worldwide — particularly among millennials and Gen Z consumers — are expanding the global pet owner base at an unprecedented pace. The humanization trend, where pets are treated as family members, has elevated expectations around nutrition, ingredient transparency, and product quality. This cultural shift is a primary engine of the pet food market's premiumization wave.
- Growing Awareness of Pet Health and Nutrition
Pet owners are increasingly health-conscious on behalf of their animals. Growing awareness of conditions such as obesity, diabetes, food allergies, and digestive disorders in pets has fueled demand for functional and specialized food products. Manufacturers are responding with formulations offering targeted health benefits — from immune support and joint health to digestive wellness and coat conditioning.
- Continuous Technological Advancements in Production
Innovations in pet food manufacturing — including advanced extrusion technologies, freeze-drying processes, and improved packaging — are enabling wider nutritional variety and extended shelf life. Lab-grown proteins, insect-based ingredients, and precision nutrition formulations are among the emerging innovations positioning brands at the cutting edge of the market.
- Expanding E-Commerce and Retail Distribution Channels
The rapid growth of online retail has fundamentally changed how pet food is purchased. E-commerce channels accounted for approximately 27% of total U.S. pet food sales in 2023, up from 32% of all pet care online in 2020. Subscription models, auto-ship programs, and personalized product recommendations are enhancing convenience and driving repeat purchase behavior.
- Rising Disposable Incomes, Especially in Emerging Markets
Increasing disposable incomes in Asia Pacific, Latin America, and the Middle East are enabling pet owners in these regions to trade up from economy to premium pet food. As urbanization accelerates and pet ownership becomes culturally more prevalent, demand for higher-quality, specialized products is surging in previously underpenetrated markets.
- Sustainability and Ethical Sourcing Demands
Consumers are placing greater weight on environmental sustainability, ethical sourcing, and clean-label transparency. Brands are responding with eco-friendly packaging, responsibly sourced protein ingredients, and reduced-carbon formulations — including novel proteins from insects, algae, and cultivated meat — all of which are reshaping competitive positioning across the industry.
Key Market Segmentation
By Pet Type
Dog Food – Largest Segment (~42.0% market share in 2025)
Dog food commands the largest share of the global pet food market, driven by the massive worldwide population of dogs and their comparatively higher dietary requirements. Dogs accounted for approximately 39.4% of all pet-related spending in 2022, with premium dog food being the fastest-growing product sub-segment. Pet owners prioritize nutrition and variety, demanding an expanding range of breed-specific, age-specific, and condition-specific formulas.
- Cat Food
- Others (Birds, Fish, Small Animals)
By Product Type
Dry Pet Food – Largest (~57.1% market share in 2025)
Dry pet food holds the dominant product share due to its cost-effectiveness, extended shelf life, and ease of storage and portioning. It remains the everyday staple diet for the majority of pet owners across income segments globally, with the economy dry dog food segment alone exceeding USD 238 Million in India as of 2021.
- Wet and Canned Pet Food
- Snacks and Treats
By Pricing Type
Mass Products – Largest Segment
Mass-market products serve the broadest consumer base, offering accessible nutrition at affordable price points through widespread distribution in supermarkets, convenience stores, and online platforms. While premium products are the fastest-growing sub-segment, mass products continue to generate the highest absolute sales volume.
- Premium Products
By Ingredient Type
Animal Derived – Largest Segment
Animal-derived ingredients — including chicken, beef, fish, and emerging novel proteins such as squid meal and shrimp hydrolysate — dominate the ingredient landscape. Pet owners strongly associate meat-based formulations with high protein content and essential nutrients necessary for their pets' health.
- Plant Derived
By Distribution Channel
Supermarkets and Hypermarkets – Largest (~62.7% market share in 2025)
Supermarkets and hypermarkets remain the dominant distribution channel, providing a convenient one-stop shopping experience with wide product variety, competitive pricing, and loyalty programs. PetSmart, with 1,669 North American stores as of March 2022, exemplifies the scale of this channel's reach.
- Specialty Stores
- Online Stores
- Others
Regional Market Analysis
| Region | Key Highlights |
| North America – Largest (42.5%+ share) | United States & Canada; high pet ownership rates, strong premium product demand, widespread e-commerce adoption, U.S. pet food sales at USD 64.4 Billion (2023 per APPA), robust organic and grain-free product growth |
| Europe | UK, Germany, France; mature pet care cultures, growing sustainability demands, EU pet food exports at EUR 4.8 Billion (2022 per FEDIAF), strong premium and organic segment |
| Asia Pacific | China, Japan, India, South Korea, Australia; China's pet consumer market at USD 41.9 Billion (2024), fastest-growing regional market, urbanization driving pet ownership, rising demand for international premium brands |
| Latin America | Brazil, Mexico; Brazil's pet food market at USD 7.4 Billion (2023), Mexico with ~60 million dogs and cats, growing middle class driving premiumization, e-commerce gaining share |
| Middle East & Africa | UAE, Saudi Arabia, South Africa; UAE home to over 2 million pets, pet care industry exceeding USD 300 Million, increasing urbanization and pet culture adoption driving quality product demand |
Connect for Detailed Segmentation Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=667&flag=C
Leading Players in the Pet Food Industry
The global pet food market features a highly competitive landscape where multinational consumer goods giants compete alongside specialized premium brands and fast-growing regional players. Key companies covered in the IMARC Group report include:
- Mars Petcare Inc.
- Nestlé Purina Pet Care (Nestlé SA)
- Hill's Pet Nutrition
- The J.M. Smucker Company
The competitive landscape is marked by intense focus on innovation, quality, and pricing strategies to capture consumer loyalty. Companies are investing in premium, organic, and specialized products to meet the demand for tailored nutritional and wellness solutions. Strategic partnerships with retail and e-commerce platforms are enhancing market reach, while aggressive marketing — including influencer collaborations and digital campaigns — is driving consumer engagement. Regional players and global brands alike compete on product differentiation, unique formulations, and packaging innovation, with R&D investment continuing to accelerate to address shifting consumer preferences.
The report provides a comprehensive competitive analysis covering market structure, player positioning, winning strategies, a competitive dashboard, and a company evaluation quadrant.
Latest Industry Developments
October 2024 – Mars Petcare Inc.
Mars Petcare announced plans to invest USD 1 Billion over three years to expand its digital capabilities, with 70% allocated toward hiring, upskilling, and third-party partnerships, and the remaining 30% directed to AI, data management, and e-commerce infrastructure. The initiative aims to accelerate the company's digital transformation and strengthen its position in online retail channels.
March 2024 – The Crump Group Inc.
The Crump Group Inc. announced a USD 85 Million investment to expand its existing premium dog treat manufacturing facility in Nashville, North Carolina, signaling strong confidence in the continued growth of the premium pet treat segment.
March 2024 – Tropikal Pet A.S.
Turkish pet food producer Tropikal Pet A.S. announced a USD 9 Million funding agreement with Eminova Holdings International to expand its production capabilities and enter the U.S. pet food market, highlighting the growing international competitiveness of emerging-market manufacturers.
January 2024 – Hill's Pet Nutrition
Hill's Pet Nutrition launched its new Prescription Diet line with a strong emphasis on palatability and taste preference. New products introduced between March and June 2024 included z/d Low Fat Hydrolyzed Soy Canine, c/d Multicare Low Fat Canine, and Gastrointestinal Biome Stress Feline formulations, underscoring the brand's continued leadership in therapeutic pet nutrition.
August 2023 – Mars Inc.
Pet food major Mars Inc. invested INR 800 crore (approximately USD 94.17 Million) in the second phase of expansion at its manufacturing facility in Telangana, India, reinforcing its long-term commitment to the high-growth Asia Pacific market.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Technology, Retail, Healthcare, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104