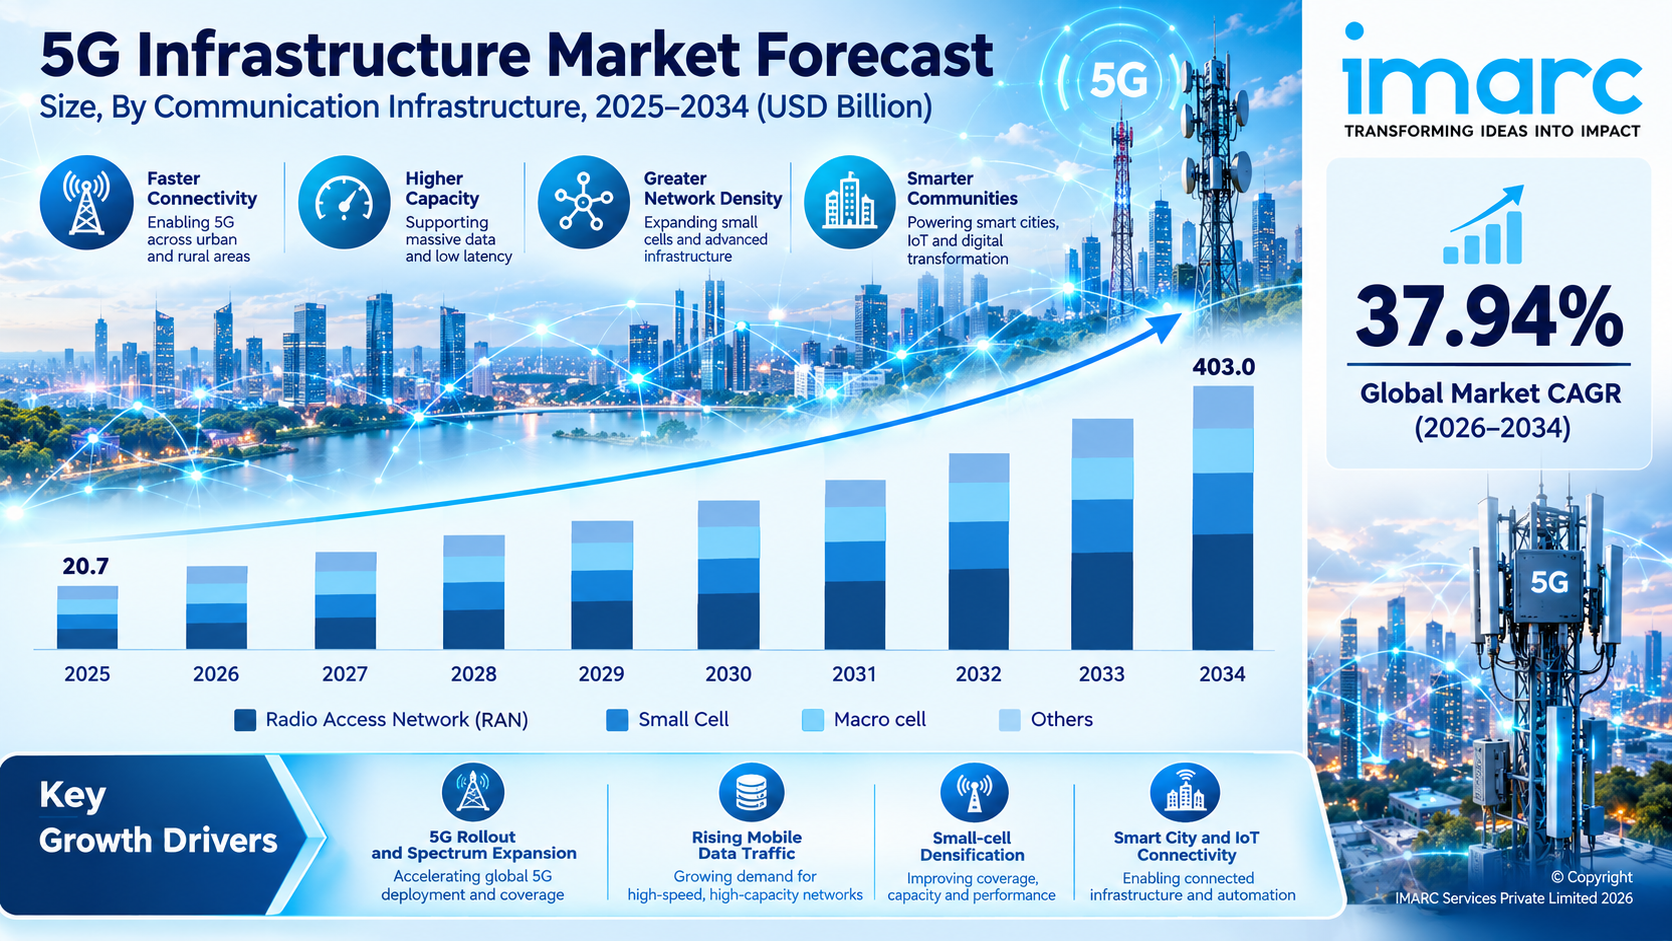
The global 5G infrastructure market size reached USD 20.7 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 403.0 Billion by 2034, exhibiting a growth rate (CAGR) of 37.94% during 2026-2034. The market is expanding due to rising mobile data consumption, growing demand for faster and more reliable connectivity, supportive government initiatives for network expansion, and increasing adoption of 5G across industrial automation, transportation, and healthcare.
Market Drivers, Challenges & Opportunities
Major Market Drivers:
- Rising Mobile Data Demand: Growth in smart devices, IoT, and AR/VR applications is increasing demand for high-bandwidth, low-latency networks.
- Industry 4.0 and Automation: 5G enables real-time analytics, remote monitoring, and predictive maintenance across industrial sectors.
- Government Initiatives: Spectrum allocation, financial incentives, streamlined permitting, and smart city programs are accelerating deployment.
- Fixed Wireless Access Expansion: FWA is extending broadband access, particularly in rural and underserved areas.
- Operator and Vendor Partnerships: Collaboration between telecom operators and technology providers is expanding coverage and improving service quality.
Key Challenges:
- High Deployment Costs: Building and densifying 5G networks, including small cells and new radio equipment, requires substantial capital investment.
- Spectrum Availability: Access to suitable spectrum and the pace of allocation can influence the speed of network rollouts.
- Integration with Existing Networks: Migrating from LTE-dependent non-standalone deployments to full standalone 5G adds technical and operational complexity.
Emerging Opportunities:
- Private 5G Networks: Industrial users in mining, manufacturing, and logistics are adopting dedicated 5G networks for mission-critical operations.
- Fixed Wireless Access: 5G-based broadband can reach rural and underserved households and businesses.
- Open RAN and Virtualization: Open and virtualized network architectures create opportunities for new vendors and more flexible deployments.
- Network Automation: Automation of 5G network operations can improve efficiency and service quality.
- Emerging Regions: Rising mobile data traffic and internet users in Latin America, the Middle East, and Africa open long-term growth avenues.
Request for a Sample Report for Detailed Evaluation: Request Sample
What Is Driving 5G Infrastructure Market Growth in 2026?
Rising Demand for High-Speed, Low-Latency Connectivity
The rapid growth of mobile data consumption is one of the primary factors driving the 5G infrastructure market. The proliferation of smart devices, Internet of Things (IoT) applications, and bandwidth-intensive technologies such as augmented and virtual reality (AR/VR) requires networks that deliver high bandwidth and low latency. According to GSMA estimates, there were over 1.5 billion 5G connections worldwide in 2023.
This surge in connected devices and data traffic is encouraging telecom operators to expand and densify their networks, supporting sustained investment in 5G radio, core, and transport infrastructure.
Industry 4.0 and Industrial Automation
The adoption of Industry 4.0 and automation is creating strong demand for robust and scalable 5G networks. Industries such as manufacturing, mining, transportation, healthcare, and agriculture are using 5G to enable real-time analytics, remote monitoring, predictive maintenance, and precision farming.
Telecom operators and technology providers are also forming partnerships to expand coverage and improve service quality, with private 5G agreements—such as the October 2022 agreement between Becker Mining Systems and Ericsson—illustrating the growing role of 5G in industrial environments.
Supportive Government Initiatives
Governments across the world are supporting 5G rollouts through spectrum allocation, financial incentives, streamlined permitting processes, and smart city programs. Initiatives such as the 5G India 2020 forum highlight how policy support is helping accelerate deployment.
These measures reduce barriers to infrastructure investment and help telecom operators scale networks faster, particularly in regions pursuing national digital transformation agendas.
Expansion of Fixed Wireless Access (FWA)
Fixed wireless access is emerging as a key application of 5G infrastructure, expanding broadband availability especially in rural and underserved areas where fiber deployment is difficult or costly.
The growing number of FWA connections is encouraging operators to extend 5G coverage and capacity, creating additional demand for small cells, macro cells, and RAN equipment.
5G Infrastructure Market Segmentation Analysis
By Communication Infrastructure
- Small Cell
- Macro Cell
- Radio Access Network (RAN)
- Others
Radio access network (RAN) accounts for the majority of the market share, at about 67.1% in 2025. RAN comprises the radio equipment, antennas, and base stations that connect user devices to the core network, making it the most capital-intensive layer of 5G deployment. Continued network rollouts, coverage expansion, and capacity upgrades keep RAN at the center of operator investment.
Small cells are gaining importance as operators densify networks to deliver high capacity in urban areas, indoor locations, and enterprise campuses, while macro cells continue to provide wide-area coverage across urban, suburban, and rural regions.
By Network Technology
- Software-Defined Networking (SDN)
- Network Function Virtualization (NFV)
- Others
Network function virtualization (NFV) holds the leading position in the market in 2025. NFV allows network functions to run as software on standard hardware rather than on dedicated appliances, helping operators scale services flexibly, reduce costs, and deploy new capabilities faster.
Software-defined networking (SDN) complements this by enabling centralized, programmable network control, supporting efficient traffic management, automation, and network slicing in 5G environments.
By Network Architecture
- Standalone (SA)
- Non-Standalone (NSA)
Standalone architecture uses a dedicated 5G core and offers the full 5G feature set, including lower latency and advanced capabilities such as network slicing, making it well suited to enterprise and industrial use cases.
Non-standalone architecture serves as an interim approach that leverages existing LTE infrastructure, allowing operators to launch 5G services faster and at a lower initial investment before migrating to standalone networks.
By Frequency
- Sub-6 GHz
- Above 6 GHz
Sub-6 GHz accounts for the largest share of the market, at about 84.5% in 2025. These frequencies offer a favorable balance of coverage and capacity, enabling wide-area deployment with fewer sites compared with higher-frequency bands.
Above 6 GHz spectrum, including millimeter-wave bands, supports very high data speeds and capacity in dense environments, although its shorter range requires more extensive small-cell deployment.
By End User
- Automotive
- Energy and Utilities
- Healthcare
- Home User
- Others
Home users hold the largest share of the 5G infrastructure market, at about 26.7% in 2025, supported by rising demand for high-speed mobile broadband and FWA services for home internet access.
Automotive applications are benefiting from connected and autonomous vehicle initiatives, while energy and utilities are adopting 5G for smart grid monitoring and remote asset management. Healthcare is leveraging low-latency connectivity for remote monitoring, telemedicine, and connected medical devices.
By Region
- North America United States Canada
- Asia Pacific China Japan India South Korea Australia Indonesia Others
- Europe Germany France United Kingdom Italy Spain Russia Others
- Latin America Brazil Mexico Others
- Middle East and Africa
Asia Pacific holds the largest share of the global 5G infrastructure market, accounting for over 62.0% in 2025. China, Japan, and South Korea lead regional deployment, with China having over 2.3 million 5G base stations at the end of 2022.
North America is a major market, with the United States accounting for about 92.90% of regional share. Fixed wireless access is a key growth area, with about 9 million FWA premises connected in the first quarter of 2024, and 5G low-band coverage reaches around 90% of the U.S. population.
In Europe, 5G adoption is progressing steadily. Western Europe had an estimated 226 million 5G subscriptions in 2024, up from 143 million, and operators such as Telekom Deutschland have extended 5G coverage to 96% of the population.
Latin America is expected to see mobile data traffic grow threefold between 2024 and 2030, at 19% year-on-year, supporting continued investment in 5G network capacity.
In the Middle East and Africa, mobile internet users are projected to reach about 422 million by 2030, up from 327 million in 2023, creating long-term opportunities for network expansion.
Competitive Landscape in the 5G Infrastructure Industry
The global 5G infrastructure market features active competition among established network equipment vendors, telecom operators, and technology providers. Leading market participants are focusing on expanding 5G portfolios, advancing Open RAN and virtualized network solutions, and enhancing network automation capabilities.
Strategic partnerships, collaborations, and acquisitions are also being pursued to expand coverage, strengthen service offerings, and address enterprise and fixed wireless access opportunities.
Key 5G Infrastructure Market Players Include:
- Airspan Networks
- AT&T
- Cisco Systems
- Comba Telecom
- Hewlett Packard Enterprise
- Huawei
- Mavenir (Comverse Technology)
- NEC
- Nokia
- Oracle
- Ericsson
- ZTE
- and others
Note: The above represents a partial list of companies covered in the report. The complete list of companies is provided in the full report.
Recent Developments:
- January 2023: Airspan Networks announced plans to expand its 5G Innovation Lab in Tokyo.
- December 2023: AT&T announced plans with Ericsson to lead commercial-scale Open RAN deployment in the United States.
- January 2024: T-Mobile and Cisco launched the Connected Workplace managed service.
- January 2024: Telekom Deutschland extended its 5G network to 96% population coverage.
- February 2024: Wind Tre completed its acquisition of Linkem OpNet, a fixed wireless access provider.
- February 2025: AT&T expanded its partnership with Nokia on 5G network automation, including Voice over New Radio (VoNR).
About the Author:
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Energy and Mining, Construction and Manufacturing, Automotive, Chemicals and Materials, and more.
Media & Sales Contact:
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104