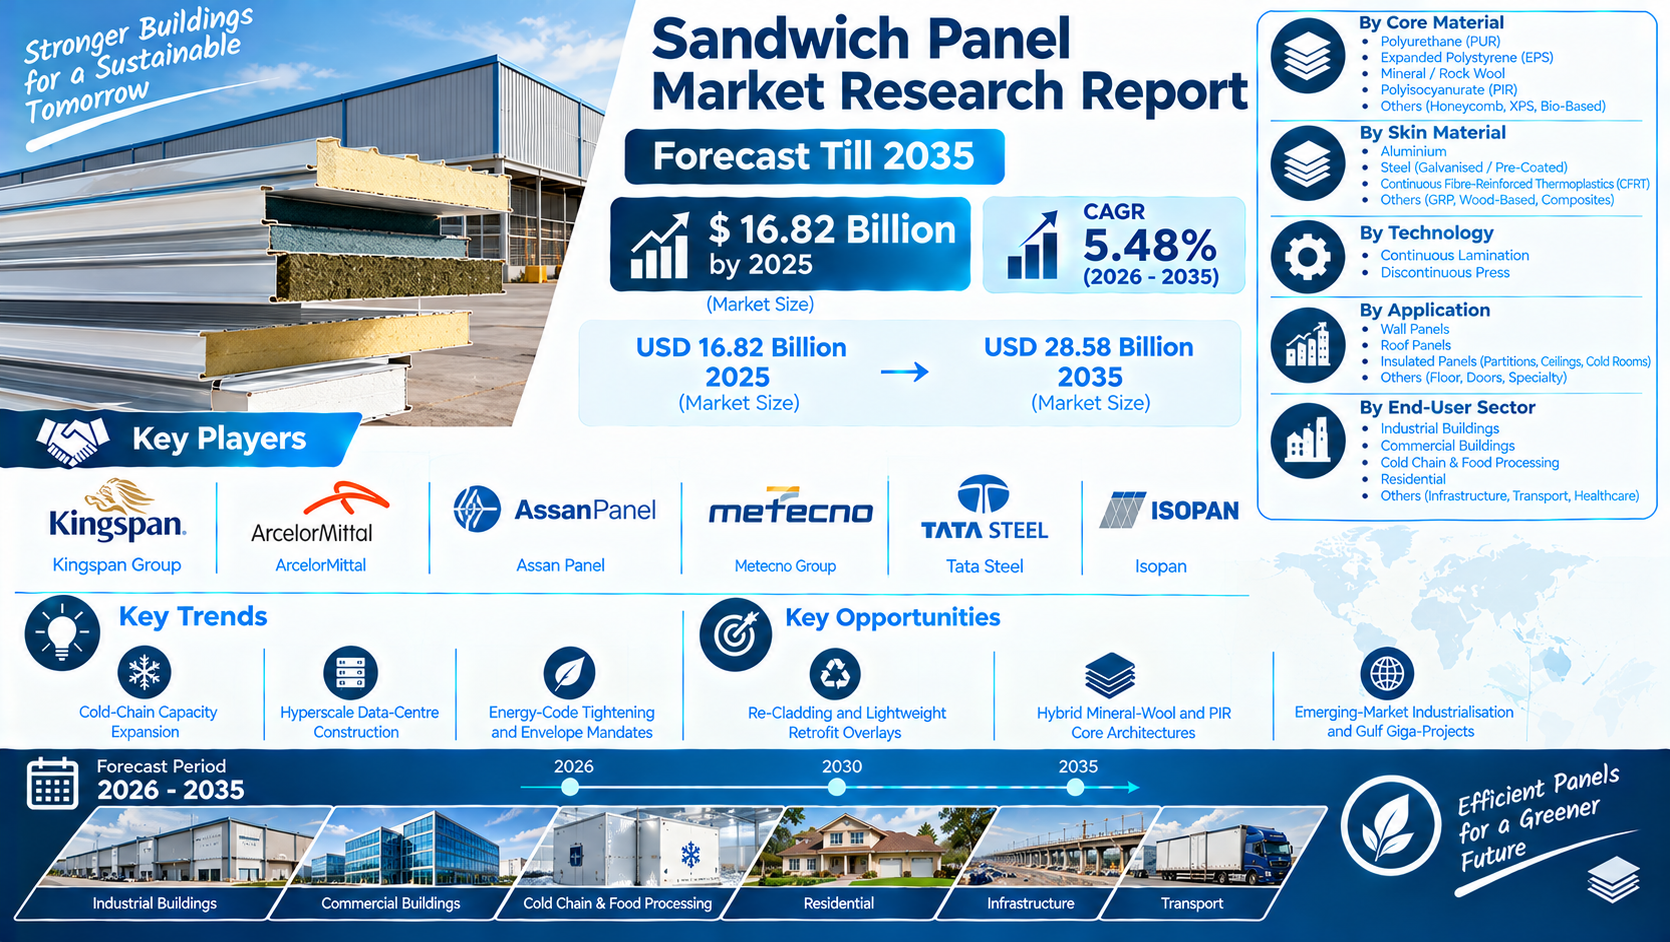
According to Market Research Future® (MRFR), the Sandwich Panel Market is expected to increase from USD 16.82 billion in 2025 to USD 28.58 billion by 2035, advancing at a CAGR of 5.48% over 2026–2035. The market's development is associated with changing construction requirements, growing demand for insulated facilities, and opportunities in building renovation. Cold-chain infrastructure, large-scale data centres, and industrialisation are among the trends creating potential demand for panel-based building systems.
Market Growth and Construction Requirements
Sandwich panels combine an internal core with outer skin materials to form building components used in walls, roofs, and insulated spaces. Their composition can be adapted to different construction needs, allowing project teams to consider thermal insulation, material weight, durability, and installation requirements when selecting products. The choice of panel depends on the building's intended function and the specifications that apply to the project.
The forecast increase from USD 16.82 billion in 2025 to USD 28.58 billion in 2035 represents an expansion of USD 11.76 billion over the period. The projected 5.48% CAGR reflects the anticipated growth between 2026 and 2035. Demand will depend on construction investment, renovation activity, building standards, and the suitability of available panel systems for different structures.
Core Materials and Exterior Skins
Material selection is central to sandwich panel design. The market's core-material categories include polyurethane (PUR), expanded polystyrene (EPS), mineral / rock wool, polyisocyanurate (PIR), and other materials such as honeycomb, XPS, and bio-based options. Each category offers a potential choice for projects with particular design and performance requirements. Buyers must evaluate the properties needed for the application rather than assume that one core material is appropriate for every building.
Skin materials covered in the report include aluminium, steel (galvanised / pre-coated), continuous fibre-reinforced thermoplastics (CFRT), and other options such as GRP, wood-based materials, and composites. These skins form the panel's outer surfaces and contribute to its suitability for the intended environment. The combination of core and skin affects the final product configuration, so manufacturers must match material options to project requirements and applicable standards.
The range of materials also gives suppliers scope to serve different customer preferences. However, the supplied data does not provide revenue shares or growth rates for individual materials, so it does not establish which core or skin category leads the market.
Production Technology and Application Areas
Continuous lamination and discontinuous press are the two technology categories specified in the report. These processes provide different production approaches for sandwich panels. Manufacturing decisions can depend on panel design, required specifications, production planning, and the needs of customers. Maintaining consistency between product requirements and manufacturing capabilities is important when supplying construction projects.
The application categories cover wall panels, roof panels, insulated panels used for partitions, ceilings, and cold rooms, as well as floors, doors, and specialty applications. Wall and roof panels serve building-envelope requirements, while insulated panels can help create separated or temperature-controlled spaces. Cold rooms are particularly relevant to food processing and cold-chain infrastructure, where the building's enclosure must meet the operational needs of stored products.
The diversity of applications broadens the market's potential customer base. Nevertheless, project demand is affected by building design, construction budgets, technical specifications, and the performance criteria established by owners and developers.
Cold Chain and Data-Centre Construction
Cold-chain capacity expansion is one of the key trends identified by MRFR. Facilities used for storing and processing temperature-sensitive goods require building systems that address their insulation and operational needs. Sandwich panels may be considered for cold rooms and related structures when their specifications suit the project. Growth opportunities will depend on infrastructure investment and the requirements of individual facilities.
Hyperscale data-centre construction represents another emerging demand area. Large data-centre projects require coordinated building and infrastructure systems, and sandwich panels may be relevant where their characteristics meet the building design. However, the supplied information does not quantify the volume of panel demand associated with data centres or identify a specific share of market revenue attributable to this segment.
Tighter energy codes and building-envelope mandates can also affect product selection. Developers and building owners may need to assess insulation systems against local requirements and project performance goals. The effects will differ across markets because regulations, climate conditions, and building practices are not uniform.
Retrofit Projects and New Opportunities
Re-cladding and lightweight retrofit overlays are identified as opportunities for the industry. Existing buildings may require envelope upgrades, and project teams can assess lightweight panel solutions where they suit the building's structure and renovation objectives. Feasibility depends on the condition of the existing facility, installation constraints, design requirements, and compliance with relevant standards.
Hybrid mineral-wool and PIR core architectures provide another opportunity for product development. These combinations may be evaluated for projects that need a specific balance of performance characteristics. Adoption will depend on the suitability of the architecture, cost, product availability, and customer requirements.
Emerging-market industrialisation and Gulf giga-projects also feature in the report's opportunity outlook. Industrial expansion can increase the need for factories, warehouses, and other facilities, while major construction programmes may create procurement opportunities for panel suppliers. The scale of any resulting demand will depend on project execution, material selection, and supply capabilities.
End Users and Competitive Landscape
The market serves industrial buildings, commercial buildings, cold chain and food processing, residential projects, and other sectors, including infrastructure, transport, and healthcare. These end users differ in their construction methods and requirements, creating varied opportunities for manufacturers. Suppliers need to adapt their product configurations to the technical needs of each project.
MRFR identifies Kingspan Group, ArcelorMittal, Assan Panel, Metecno Group, Tata Steel, and Isopan as key players. The supplied information does not provide market-share data, revenue comparisons, or competitive rankings for these companies. Their inclusion indicates the range of participants covered in the market assessment, not a confirmed order of market leadership.
Forecast Outlook
The Sandwich Panel Market is projected to grow to USD 28.58 billion by 2035 from USD 16.82 billion in 2025, at a CAGR of 5.48% during 2026–2035. Construction requirements, cold-chain expansion, data-centre development, retrofit projects, and industrialisation form the principal areas of interest. Continued opportunities will depend on matching core and skin materials, manufacturing technology, and application-specific requirements to the needs of construction projects.