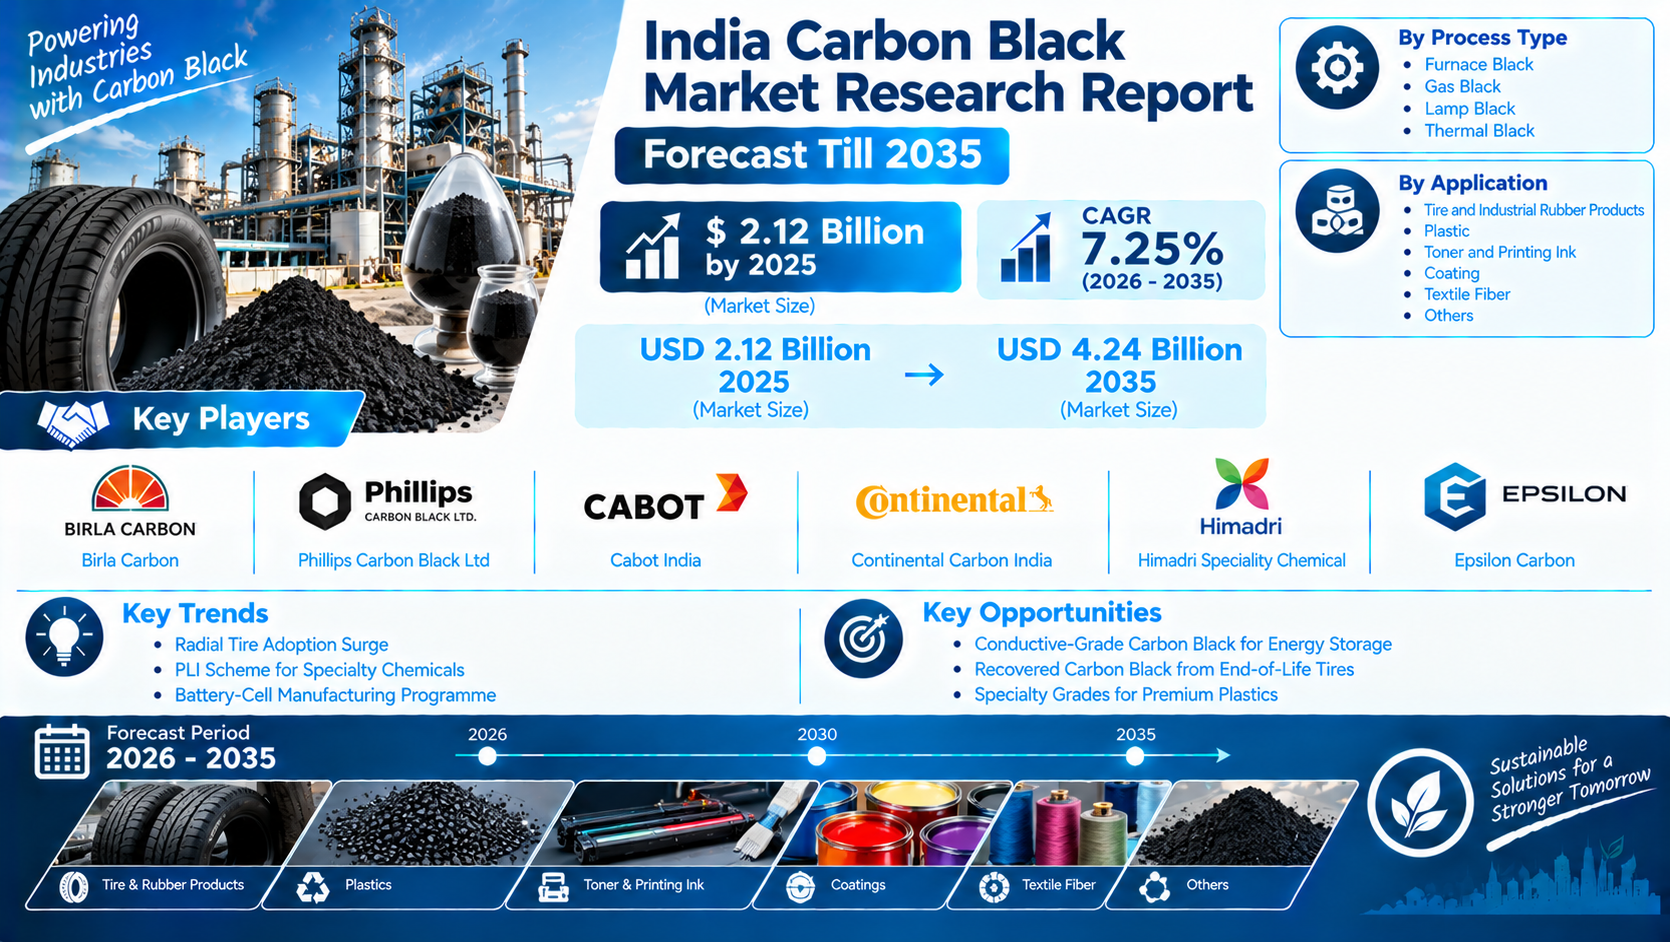
According to Market Research Future® (MRFR), the India Carbon Black Market is expected to expand from USD 2.12 billion in 2025 to USD 4.24 billion by 2035, reflecting a CAGR of 7.25% over the 2026–2035 forecast period. The material serves a broad range of industrial applications, including tire production, industrial rubber, plastics, printing inks, and coatings. Changes in automotive manufacturing, specialty chemical production, and energy-storage technologies are creating opportunities for India's carbon black industry.
Carbon Black's Role in Industrial Manufacturing
Carbon black is used in products that require particular reinforcing, coloring, or functional characteristics. Tire and rubber manufacturers are major participants in its application landscape, while plastics, toner and printing inks, coatings, textile fibers, and other industries provide additional outlets. This range of uses links demand to multiple manufacturing sectors rather than a single end market.
The forecast indicates that the market is expected to double in value between 2025 and 2035. Growth opportunities will depend on the development of downstream industries, the needs of industrial customers, and the ability of producers to deliver consistent materials. Carbon black manufacturers must also consider how product requirements differ between high-volume rubber applications and specialized formulations.
Tire Manufacturing Remains a Key Demand Area
The adoption of radial tires is one of the identified trends in India's carbon black market. Carbon black is used in tire compounds and can contribute to the reinforcement and performance characteristics required in rubber products. As tire manufacturers evaluate material inputs, consistent quality and compatibility with their production processes remain important.
Demand is not limited to tires. Industrial rubber products create additional applications across manufacturing and equipment-related uses. These customers may require carbon black grades suited to different compound formulations and operating conditions. Suppliers that understand application specifications can support customers in choosing appropriate products.
Serving these markets requires reliable production and distribution. Variations in material characteristics can affect downstream processing, making quality control and technical support important parts of supplier relationships. Manufacturers must therefore align production capabilities with the requirements of tire producers and other rubber-product customers.
Production Processes and Grade Selection
The market's process-type categories are furnace black, gas black, lamp black, and thermal black. Each category is associated with production methods and material characteristics that influence potential applications.
Furnace black is used in several industrial applications, including rubber products. Gas black, lamp black, and thermal black can serve different requirements depending on their properties and the formulation in which they are used. Selection depends on the customer's intended use, technical specifications, and manufacturing process.
The range of production types creates opportunities for manufacturers to serve different customer segments. Developing and supplying suitable grades requires process control, consistent product quality, and an understanding of end-use requirements. Specialty products can offer a route to differentiation where customers require more specific characteristics than those associated with general-purpose grades.
Expanding Applications Beyond Rubber
Carbon black is also used in plastics, toner and printing ink, coatings, textile fibers, and other applications. These segments provide diversification opportunities for suppliers and connect demand to several types of industrial production.
In plastics, material selection may be influenced by appearance, formulation requirements, and functional performance. Specialty grades for premium plastics are an identified opportunity for the Indian market. Suppliers can explore this area by aligning product specifications with the needs of manufacturers producing higher-value plastic products.
Toner and printing inks require suitable coloring materials and consistent formulation characteristics. Coatings and textile fiber applications contribute further demand, although the requirements can differ considerably between product categories. For producers, a diversified portfolio may help address customers with different technical and commercial priorities.
Successful expansion into these applications depends on matching material properties to the end product. Technical support and consistent supply can help manufacturers evaluate whether a carbon black grade is suitable for a particular formulation.
Specialty Chemicals and Energy Storage
The PLI scheme for specialty chemicals is a key trend identified in the market. Such initiatives are relevant to the broader manufacturing environment, although the specific benefits for an individual company depend on eligibility and program conditions. The trend underscores the importance of domestic specialty chemical capabilities in shaping industrial investment decisions.
The Battery-Cell Manufacturing Programme is another development associated with the market outlook. Energy storage presents a potential application area for conductive-grade carbon black. These grades must meet the technical requirements of their intended uses, which may differ from those of conventional tire and rubber products.
This opportunity creates a potential avenue for producers to develop capabilities beyond established markets. However, entry into specialized applications requires attention to product specifications, qualification processes, and customer expectations. Market participants must evaluate the technical and commercial requirements before treating energy storage as a replacement for existing demand.
Circularity and Recovered Carbon Black
Recovered carbon black from end-of-life tires is another identified opportunity. This approach can connect the tire waste stream with material recovery and potential reuse in industrial applications. It may also support efforts to use resources more efficiently, provided the recovered product meets the requirements of the intended application.
The commercial potential of recovered carbon black depends on processing methods, quality consistency, and customer acceptance. Different end uses may require different levels of performance, so recovered material may not be interchangeable with every conventional grade. Producers and users need to evaluate its suitability against application-specific specifications.
The opportunity nevertheless gives market participants another area to explore as the industry considers resource recovery alongside conventional production.
Competitive Landscape in India
The key players listed by MRFR are Birla Carbon, Phillips Carbon Black Ltd, Cabot India, Continental Carbon India, Himadri Speciality Chemical, and Epsilon Carbon. Competition can reflect production capabilities, product range, technical expertise, supply reliability, and customer relationships.
Companies serving tire and industrial rubber manufacturers must maintain dependable material quality, while those targeting plastics or emerging applications may need more specialized grades. The ability to address both established and developing applications can help suppliers diversify their market exposure.
Outlook Through 2035
The India Carbon Black Market is projected to grow at a CAGR of 7.25% from 2026 to 2035, reaching USD 4.24 billion by the end of the forecast period. Radial tire adoption, specialty chemical initiatives, and battery-cell manufacturing are important trends shaping the outlook. Conductive carbon black for energy storage, recovered material from end-of-life tires, and specialty grades for premium plastics provide potential growth avenues. Producers that combine dependable supply with targeted product development can address established industrial demand while exploring emerging applications.