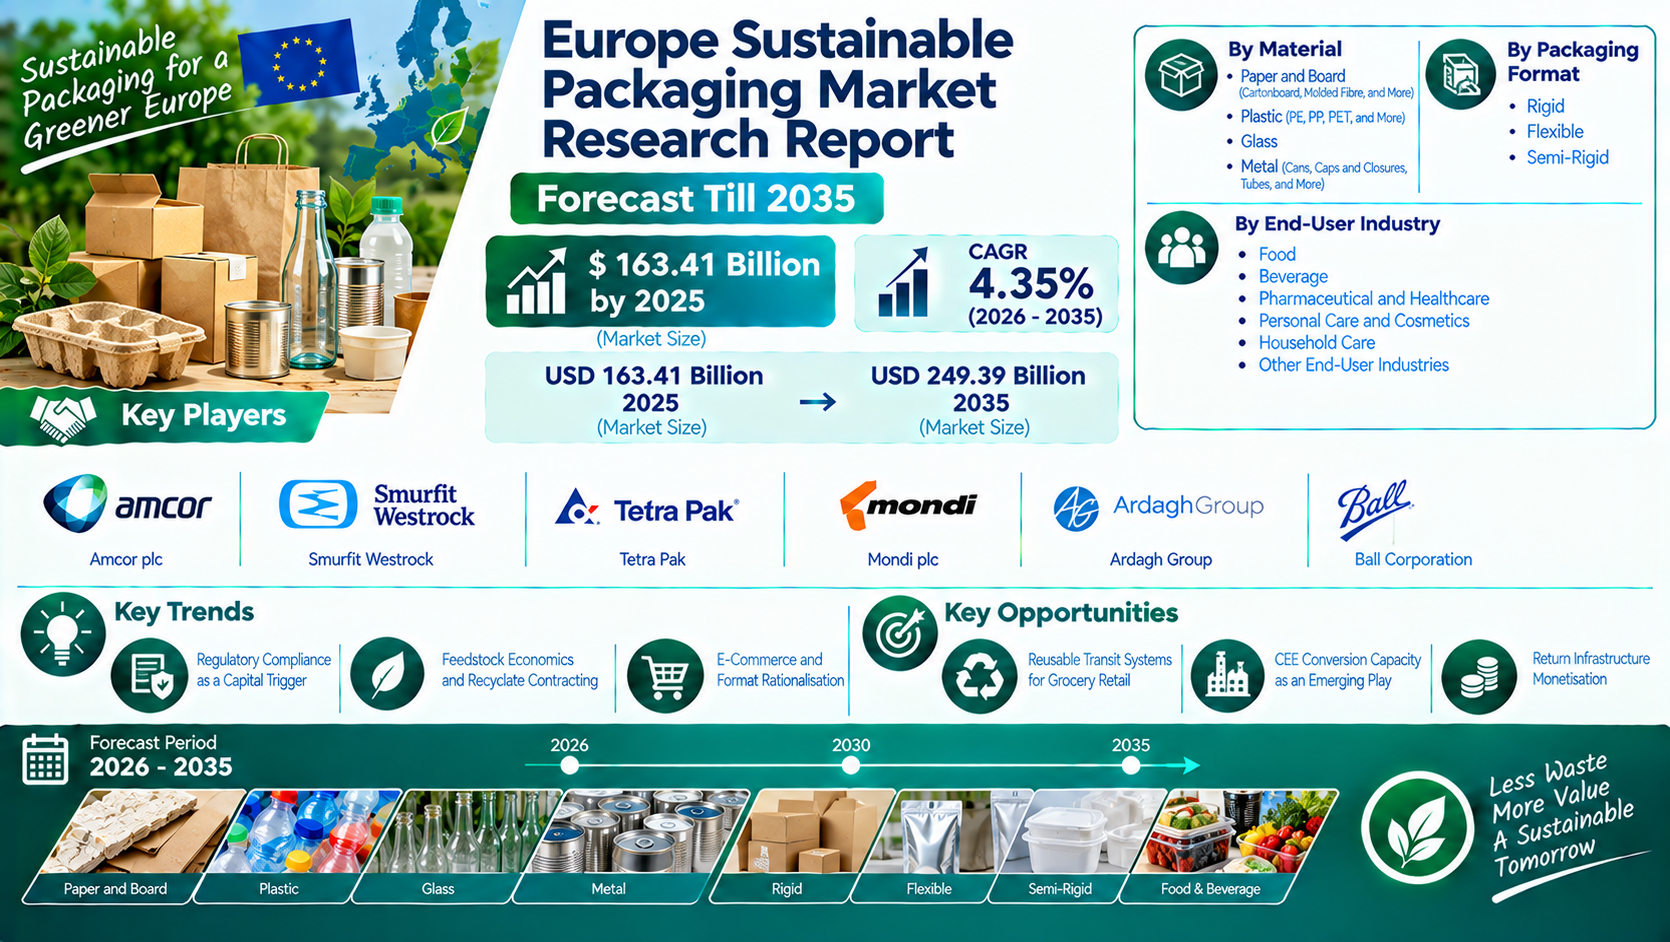
According to Market Research Future® (MRFR), the Europe Sustainable Packaging Market is expected to expand steadily as businesses adapt packaging strategies to environmental priorities, regulatory requirements, and changing consumer and distribution needs. The market was valued at USD 163.41 billion in 2025 and is projected to reach USD 249.39 billion by 2035, registering a compound annual growth rate (CAGR) of 4.35% during the 2026–2035 forecast period. Its development will be shaped by material selection, packaging design, access to suitable recycled feedstocks, and the ability of companies to implement sustainable solutions across different end-user industries.
Regulatory Compliance Shapes Packaging Investment
Regulatory compliance is a key consideration for packaging producers and the businesses that purchase their products. European companies must assess packaging decisions against applicable environmental requirements, recycling expectations, and waste-management obligations. These considerations can influence investment in production equipment, material sourcing, packaging redesign, and systems for collecting or recovering used packaging.
For manufacturers, regulatory change can create both costs and opportunities. Businesses may need to modify established formats, evaluate alternative materials, or adjust packaging specifications to meet changing requirements. Such decisions often involve balancing environmental objectives with product protection, production efficiency, transport needs, and affordability. Suppliers capable of providing reliable materials and practical design options may become important partners for companies reviewing their packaging portfolios.
The impact of regulation varies according to material, product category, and application. Paper and board, plastic, glass, and metal have different performance characteristics and recovery pathways. A sustainable packaging strategy therefore requires an application-specific assessment rather than assuming that one material is appropriate for every product. Compliance planning and investment decisions are likely to remain important factors influencing market development through 2035.
Material Innovation and Feedstock Economics
The market covers paper and board, including cartonboard and molded fibre; plastics, including PE, PP, and PET; glass; and metal formats such as cans, caps and closures, and tubes. Each material category serves different packaging functions, and the selection process depends on factors such as strength, weight, barrier properties, shelf-life requirements, manufacturing compatibility, and end-of-life handling.
Paper and board can support packaging designs that prioritize fibre-based materials, while plastic remains relevant where flexibility, low weight, or particular protective properties are required. Glass and metal serve applications that need their specific structural or barrier characteristics. The sustainability performance of any format depends on its design, sourcing, use, collection, and processing, as well as the infrastructure available to recover it.
Feedstock economics and recycled-material contracting are important market themes. Packaging producers need dependable supplies of materials that meet technical and quality specifications. Recycled feedstock availability, consistency, and cost can influence procurement strategies and manufacturing economics. When suitable recycled inputs are constrained or expensive, companies may face difficult trade-offs between material targets, production requirements, and price competitiveness.
Longer-term supply relationships and better visibility into feedstock availability can help companies plan production and manage volatility. However, the commercial benefits depend on contract terms, material quality, processing capacity, and actual market conditions. Companies will need to evaluate recycled content and other sustainability attributes alongside the performance requirements of each packaging application.
Packaging Formats and End-User Requirements
The market is segmented into rigid, flexible, and semi-rigid packaging formats. Rigid packaging is used where structural strength and shape retention are important, while flexible packaging can suit applications that benefit from adaptability and efficient storage or transport. Semi-rigid formats provide an alternative for products requiring a balance between structure and flexibility. The most suitable option depends on the product, distribution environment, and packaging line.
End-user industries include food, beverage, pharmaceutical and healthcare, personal care and cosmetics, household care, and other sectors. Food and beverage businesses must consider product protection, hygiene, shelf life, and handling requirements. Pharmaceutical and healthcare packaging places particular emphasis on product integrity and applicable quality standards. Personal care and household products have their own requirements relating to usability, presentation, durability, and compatibility with the contents.
These differences create opportunities for packaging suppliers to develop solutions for specific uses rather than relying on a single design approach. Companies evaluating sustainable alternatives must ensure that packaging continues to perform its primary function. Material reduction, recyclability, or reuse objectives need to be considered alongside product protection, production efficiency, and customer requirements.
E-Commerce and Packaging Format Rationalisation
E-commerce is influencing packaging decisions by changing how products are stored, handled, shipped, and delivered. Businesses may review package dimensions, material consumption, durability, and the number of different formats used across their product ranges. Format rationalisation can simplify purchasing and production while helping companies identify opportunities to reduce unnecessary packaging complexity.
For packaging suppliers, this trend creates demand for designs that accommodate distribution requirements without compromising product protection. Standardized formats may help streamline operations, although different products still require distinct specifications. The value of redesign depends on product characteristics, shipping conditions, customer expectations, and the efficiency of existing packaging systems.
Emerging Opportunities and Competitive Landscape
Opportunities identified for the market include reusable transit systems for grocery retail, conversion capacity in Central and Eastern Europe (CEE), and monetisation of return infrastructure. Reusable transit packaging may support repeated use in suitable distribution networks, provided collection, cleaning, reverse logistics, and return rates make the system practical. Return infrastructure may create operational or commercial value when it can reliably bring packaging back into circulation.
CEE conversion capacity represents another potential opportunity for businesses seeking regional production capabilities. The attractiveness of such investment depends on demand, labour and operating costs, infrastructure, material availability, and access to customers. These factors should be assessed before drawing conclusions about the scale of the opportunity.
Key players identified by MRFR include Amcor plc, Smurfit Westrock, Tetra Pak, Mondi plc, Ardagh Group, and Ball Corporation. The supplied market information does not provide individual market shares or a ranking among these companies.
Market Outlook Through 2035
The Europe Sustainable Packaging Market is projected to grow from USD 163.41 billion in 2025 to USD 249.39 billion by 2035, at a CAGR of 4.35% during 2026–2035. Regulatory compliance, recycled-feedstock economics, e-commerce requirements, and packaging redesign will influence strategic decisions. Companies that align material performance, operational practicality, and sustainability objectives may be better positioned to respond to evolving demand across Europe.