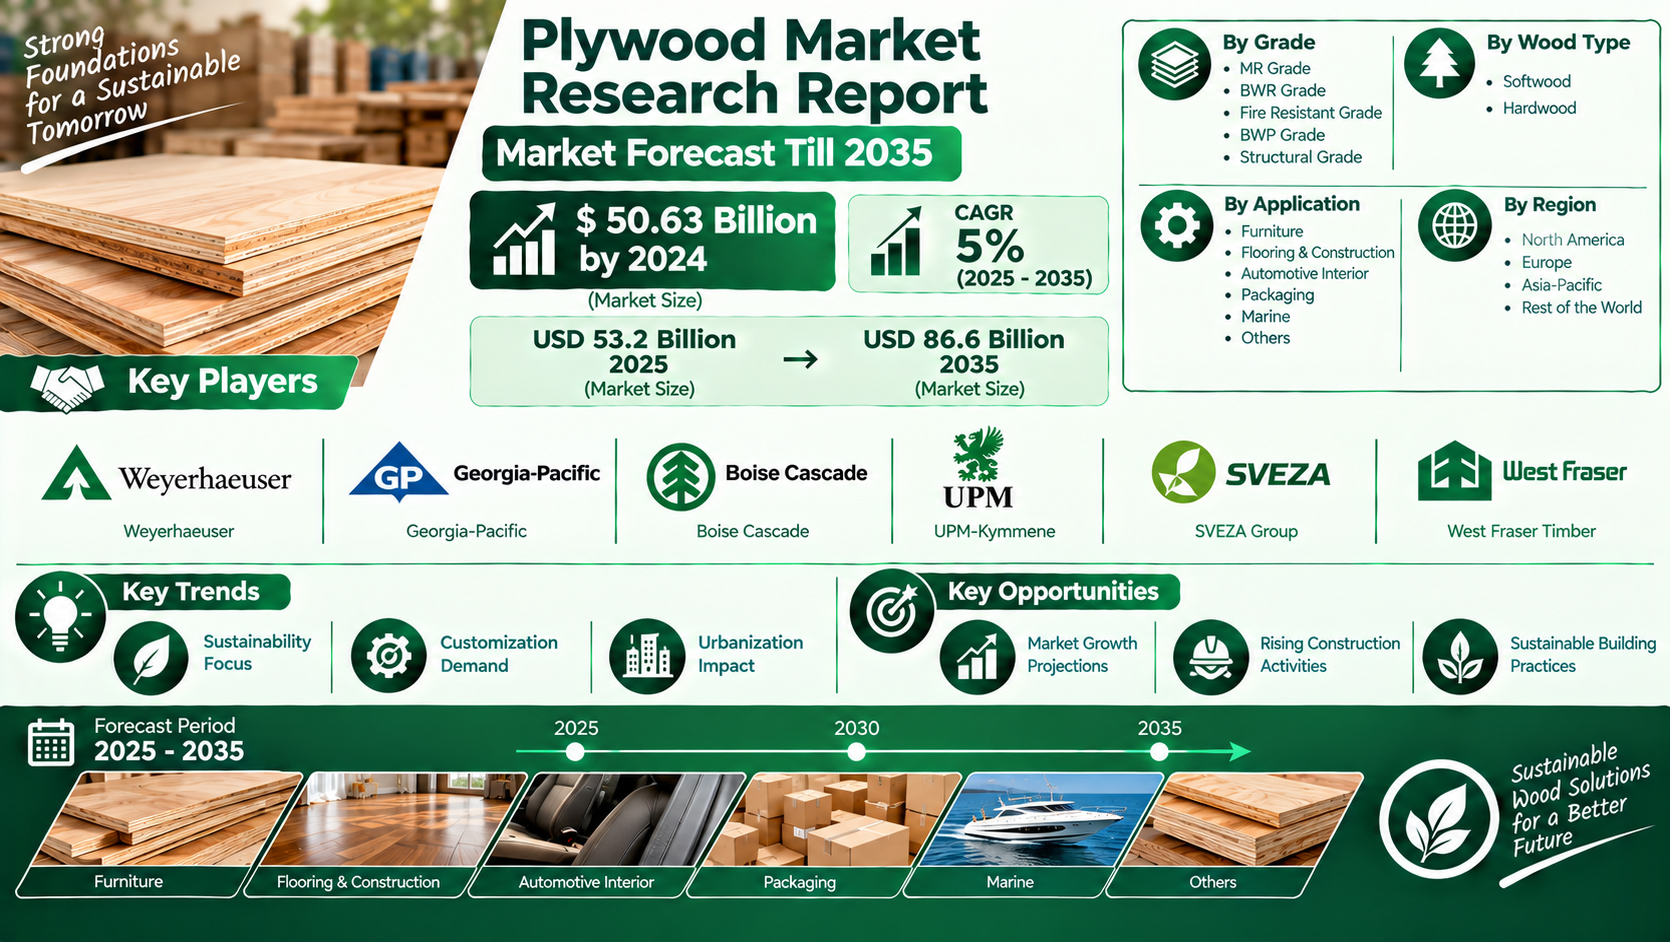
According to Market Research Future® (MRFR), the Plywood Market is expected to increase from USD 53.2 billion in 2025 to USD 86.6 billion in 2035, representing a CAGR of 5% over the 2025–2035 forecast period. The market's 2024 valuation stood at USD 50.63 billion. Its outlook reflects demand from construction, furniture production, flooring, packaging, marine uses, and automotive interiors, alongside wider interest in customized materials and sustainable building solutions.
Market Outlook and Product Importance
Plywood occupies an established position in the engineered wood products industry because it combines multiple wood veneers into a panel designed for practical strength and stability. The arrangement of veneer layers helps limit movement compared with some solid-wood products, while panel dimensions and surface characteristics make plywood suitable for many manufacturing and building tasks.
Its role extends from structural components to visible interior surfaces. Construction companies may use suitable plywood grades in flooring, wall systems, partitions, and other building applications. Furniture manufacturers use panels for cabinets, shelving, tables, and storage products, while industrial buyers may require plywood for packaging or specialized components. This range of end uses gives the market exposure to several sectors rather than a single source of demand.
The forecast suggests steady market expansion through 2035. Sustaining this trajectory will require manufacturers to align product specifications with customer needs while managing supply costs, quality expectations, and changing environmental priorities.
Grade and Wood-Type Analysis
Product grade is a central factor in purchasing decisions because different projects require different levels of moisture resistance, fire performance, and structural capability. The market includes MR Grade, BWR Grade, Fire Resistant Grade, BWP Grade, and Structural Grade plywood.
MR Grade products are intended for applications with moderate moisture exposure. BWR and BWP grades are used where greater water resistance is required, subject to the specifications of the individual product. Fire Resistant Grade plywood is relevant when projects call for materials with defined fire-performance characteristics. Structural Grade panels serve applications where mechanical strength and load-related requirements are important.
The distinctions between these grades create opportunities for manufacturers to address a broad customer base. Clear product labelling, dependable manufacturing processes, and compliance with relevant standards help buyers identify materials suitable for their intended applications. Selecting a grade that matches actual service conditions is important for both performance and cost control.
Wood type provides another basis for market segmentation. Softwood and hardwood plywood differ in their source materials and can serve different requirements depending on veneer characteristics, panel construction, and finishing needs. Softwood products are used in various construction and structural applications, while hardwood plywood is often selected for furniture, cabinetry, and interior finishes. These are broad tendencies rather than absolute rules; final selection depends on product specifications and project requirements.
Applications Across Construction and Manufacturing
Furniture is a significant application area because plywood supports the production of cabinets, shelves, desks, wardrobes, and other furnishings. Manufacturers value the availability of different panel dimensions and surface finishes, especially when producing standardized furniture or fulfilling customized orders. Design preferences and renovation activity can influence the types of panels purchased.
Flooring and construction represent another important demand channel. Plywood may be specified for subfloors, partitions, wall panels, and other building components when its characteristics suit the application. Construction activity therefore affects demand, but material selection also depends on building codes, moisture conditions, engineering requirements, and the availability of alternatives.
Packaging creates demand for panels used in crates and protective containers for industrial goods. Marine applications require careful consideration of moisture exposure, adhesive performance, and the operating environment. Automotive interior uses may involve panels or components designed to meet specific requirements for fit, weight, finish, and durability. Other applications add further diversity to the market.
Because these uses have different technical and commercial priorities, suppliers benefit from understanding end-user requirements rather than relying on a uniform product strategy. A grade suitable for one application may not be appropriate for another, making specification support and product consistency valuable competitive factors.
Sustainability, Customization, and Urban Development
Sustainability is increasingly relevant to material sourcing and product selection. Plywood manufacturers can respond by improving timber utilization, reducing manufacturing waste, strengthening sourcing transparency, and communicating product attributes accurately. Responsible forestry practices and efficient use of wood resources can contribute to more credible sustainability positioning. Environmental performance, however, should be evaluated using verifiable information rather than broad claims alone.
Customization also influences product development. Customers may request specific thicknesses, dimensions, finishes, grades, or other characteristics to meet manufacturing and installation needs. Suppliers that maintain flexible production capabilities can serve a wider variety of orders, although customization must be balanced against production efficiency, inventory management, and delivery requirements.
Urbanization supports potential demand by creating requirements for housing, offices, retail buildings, and renovated interiors. These projects can stimulate purchases of construction panels, furniture materials, flooring components, and interior products. The resulting demand depends on the pace of development, construction methods, local purchasing power, and competition from other building materials.
Opportunities and Business Considerations
Rising construction activity offers manufacturers opportunities to expand sales through relationships with builders, contractors, distributors, and interior-product manufacturers. Growth in furniture production can similarly benefit suppliers that provide dependable quality and consistent panel availability. Sustainable building practices offer an additional avenue for differentiation where purchasers prioritize responsible sourcing and suitable product documentation.
To capture these opportunities, companies must navigate fluctuations in wood prices and availability, energy expenses, logistics costs, and competition from alternative engineered panels. Particleboard and medium-density fibreboard, for example, may be considered for selected furniture and interior applications. The decision depends on relative cost, finish, strength, moisture performance, and processing requirements.
Manufacturers also need to maintain quality control across bonding, pressing, finishing, and panel dimensions. Product defects or inconsistent specifications can affect customer confidence and create additional costs. Investment in efficient production, testing, and product development may help businesses respond to demanding applications while protecting operational performance.
Regional Landscape and Competition
The plywood market is assessed across North America, Europe, Asia-Pacific, and the Rest of the World. Construction investment, renovation activity, furniture manufacturing, distribution infrastructure, timber availability, and regulatory requirements shape regional opportunities. Asia-Pacific may benefit from urban development and manufacturing demand, while North America and Europe present opportunities in building, renovation, furniture, and interior applications. Conditions differ by country, and regional growth should not be assumed to be uniform.
Major companies named in the market include Weyerhaeuser, Georgia-Pacific, Boise Cascade, UPM-Kymmene, SVEZA Group, and West Fraser Timber. Their competitive environment is shaped by production capabilities, distribution, product range, sourcing, and service to customers with different specifications.
Plywood Market Forecast Through 2035
With the market projected to rise from USD 53.2 billion in 2025 to USD 86.6 billion in 2035 at a CAGR of 5%, plywood is positioned for continued expansion across construction and manufacturing applications. Sustainability, customization, and urbanization will remain relevant considerations for market participants. Companies that manage costs, maintain consistent quality, and offer products suited to varied end uses can pursue opportunities while adapting to changing customer expectations.