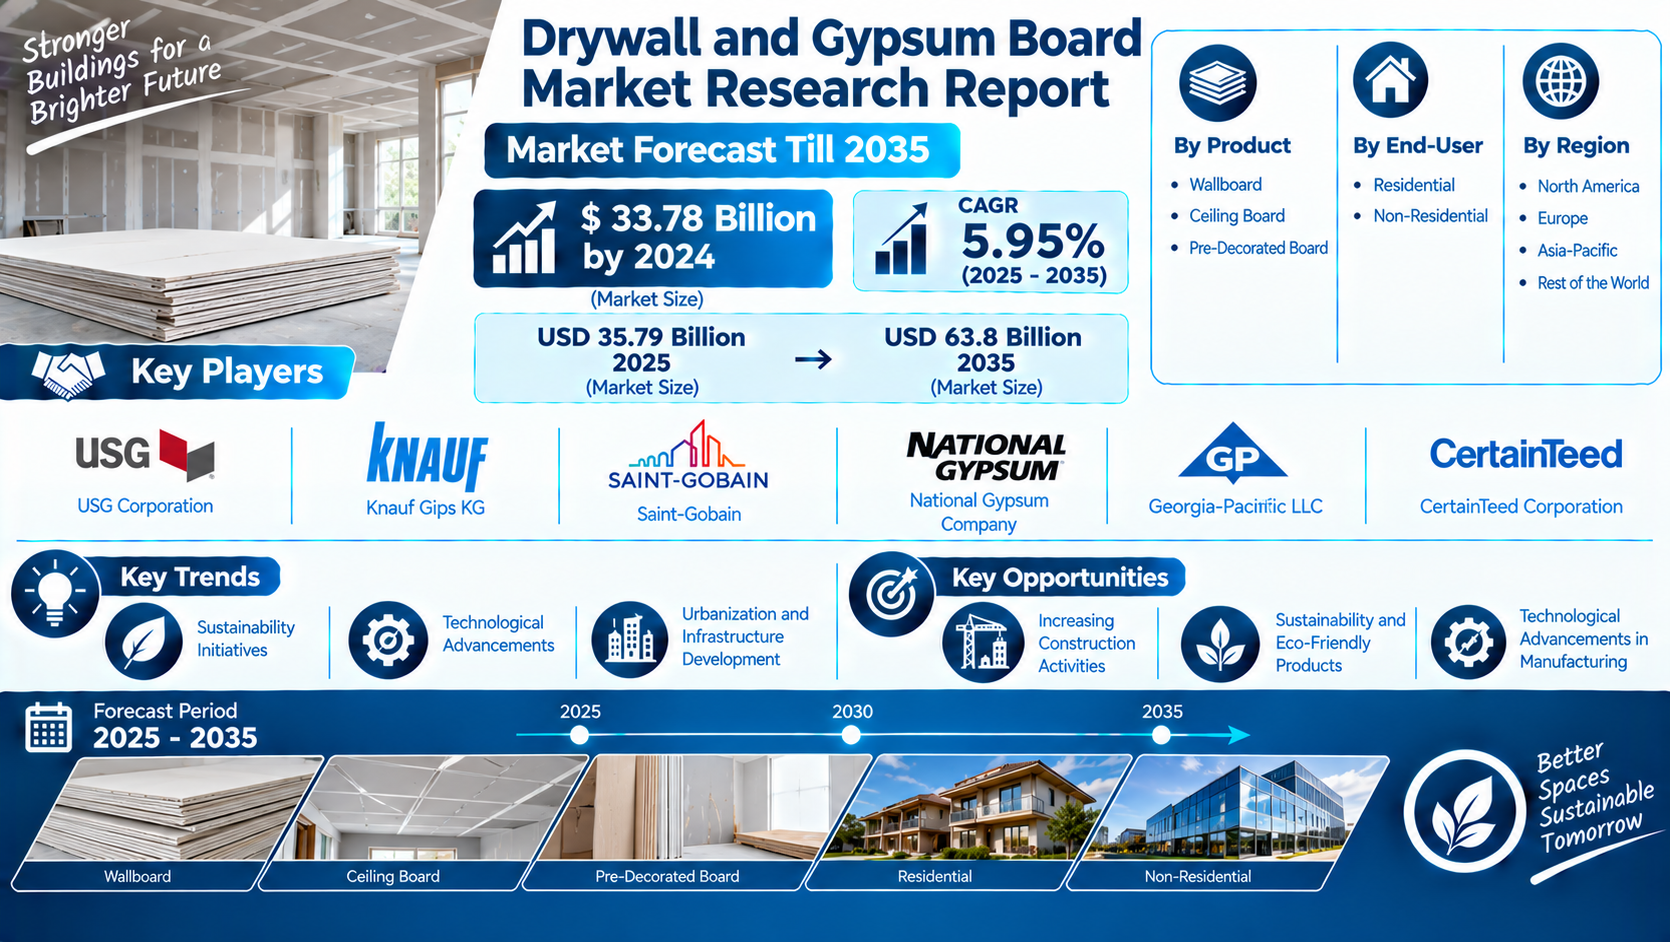
According to Market Research Future® (MRFR), the Drywall and Gypsum Board Market is projected to grow from USD 35.79 billion in 2025 to USD 63.8 billion by 2035, registering a compound annual growth rate (CAGR) of 5.95% during the 2025–2035 forecast period. The market was valued at USD 33.78 billion in 2024. Growth is supported by construction activity, urbanization, infrastructure development, and the increasing emphasis on efficient building materials and sustainable construction practices.
Drywall and Gypsum Board Market Overview
Drywall and gypsum board are widely used in modern construction for interior walls, ceilings, partitions, and other building applications. These panels are typically manufactured using a gypsum-based core enclosed between facing materials. Their relatively straightforward installation, consistent surface quality, and suitability for different interior designs have made them important materials in residential and non-residential construction.
Compared with some traditional wall construction methods, drywall systems can help streamline interior fit-outs and support faster project completion when appropriately specified and installed. They can also accommodate a variety of finishes and building layouts. Product selection depends on factors such as the intended application, required durability, moisture exposure, fire-performance requirements, and applicable building standards.
The market's forecast growth reflects the continuing role of gypsum-based panels in new construction and renovation. However, demand is affected by construction investment, material costs, distribution networks, building regulations, and the availability of alternatives. Manufacturers must balance performance and affordability while adapting to evolving requirements from contractors, developers, and building owners.
Market Segmentation by Product and End-User
The market is segmented by product into wallboard, ceiling board, and pre-decorated board. Each category addresses different construction and finishing needs.
Wallboard is used extensively in interior wall systems and partitions across residential and commercial properties. Its popularity is associated with its versatility, compatibility with different finishing methods, and suitability for a range of building layouts. Ceiling board serves ceiling installations where appearance, installation requirements, and relevant performance characteristics influence selection. Pre-decorated board can reduce some finishing work by incorporating a decorative surface, making it useful in projects where installation time and interior presentation are important considerations.
Product differentiation enables suppliers to serve projects with varying technical and aesthetic requirements. Depending on the specification, buyers may also consider moisture resistance, fire performance, acoustic properties, handling characteristics, and compatibility with other construction materials.
By end-user, the market covers residential and non-residential construction. Residential demand comes from new housing, apartment developments, home improvement, and renovation projects. Non-residential applications include offices, retail properties, educational facilities, healthcare buildings, hospitality properties, and other commercial or institutional structures. These projects may have distinct performance requirements and procurement processes, creating opportunities for manufacturers with broad product portfolios.
Major Trends Shaping Market Development
Sustainability initiatives are influencing decisions across the construction materials industry. Developers and building owners are increasingly considering resource efficiency, waste reduction, product durability, and the environmental impact of materials throughout their life cycles. Gypsum board manufacturers can respond through improved production efficiency, responsible sourcing, reduced waste, and recycling initiatives where suitable infrastructure is available.
Technological advancements are another important market influence. Improvements in manufacturing processes can support more consistent board quality, efficient resource use, and product characteristics tailored to specific applications. Developments in installation systems and building components can also improve construction workflows. The commercial value of these advances depends on performance, cost, compatibility with building practices, and compliance with applicable standards.
Urbanization and infrastructure development provide a further source of demand. Growing cities require housing, workplaces, public buildings, and commercial facilities, all of which may incorporate drywall and gypsum board. Renovation and refurbishment activity can also generate demand as building owners update interiors or adapt spaces to new requirements. The effect varies across markets according to construction budgets, building methods, and economic conditions.
Growth Opportunities and Industry Challenges
Increasing construction activity offers manufacturers opportunities to expand sales across residential and non-residential projects. Housing developments and commercial building programmes create demand for wallboard and ceiling board, while refurbishment projects can generate additional requirements for interior materials. Reliable supply, consistent product quality, and support for contractors can help suppliers compete for these opportunities.
Eco-friendly products provide another area for development. Companies that improve manufacturing efficiency, reduce material waste, and support responsible handling or recycling of gypsum-based products may be better positioned to address sustainability priorities. Clear product information and credible environmental claims are important as buyers evaluate materials for projects with specific sustainability goals.
Technological improvements in manufacturing can help companies manage production costs, reduce inconsistencies, and respond to changing customer specifications. Nevertheless, investment in equipment and process upgrades must be weighed against capital requirements and competitive pricing pressures.
The market also faces challenges from fluctuations in energy, raw-material, and transportation costs. Gypsum board is bulky relative to its value, making logistics and proximity to construction markets important commercial considerations. Manufacturers must maintain dependable delivery schedules while managing inventories and distribution expenses. Competition from alternative construction systems and materials can also influence product selection, particularly where buyers prioritize cost, installation methods, or specific performance attributes.
Regional Market Perspective
The market is assessed across North America, Europe, Asia-Pacific, and the Rest of the World. Regional performance depends on construction investment, housing demand, renovation activity, infrastructure development, local building standards, and the availability of distribution and manufacturing capacity.
Asia-Pacific offers opportunities linked to urban development, housing requirements, and infrastructure investment. North America and Europe have demand from residential construction, commercial development, and building renovation, alongside growing attention to efficient and sustainable construction practices. Opportunities in other regions depend on construction activity, access to materials, and the development of local supply chains. These regional factors influence demand differently, so growth is unlikely to be uniform across all markets.
Competitive Landscape and Market Outlook
Key companies identified in the market include USG Corporation, Knauf Gips KG, Saint-Gobain, National Gypsum Company, Georgia-Pacific LLC, and CertainTeed Corporation. Competition is shaped by product quality, manufacturing efficiency, distribution coverage, technical support, and the ability to meet project-specific requirements. Product innovation and sustainability initiatives can provide additional ways to differentiate offerings.
The drywall and gypsum board market is forecast to increase from USD 35.79 billion in 2025 to USD 63.8 billion by 2035, at a CAGR of 5.95%. Construction activity, urbanization, technological advancement, and sustainability initiatives are expected to remain central market influences. Companies that combine dependable performance with efficient production and responsive supply networks may be positioned to benefit from evolving construction requirements.