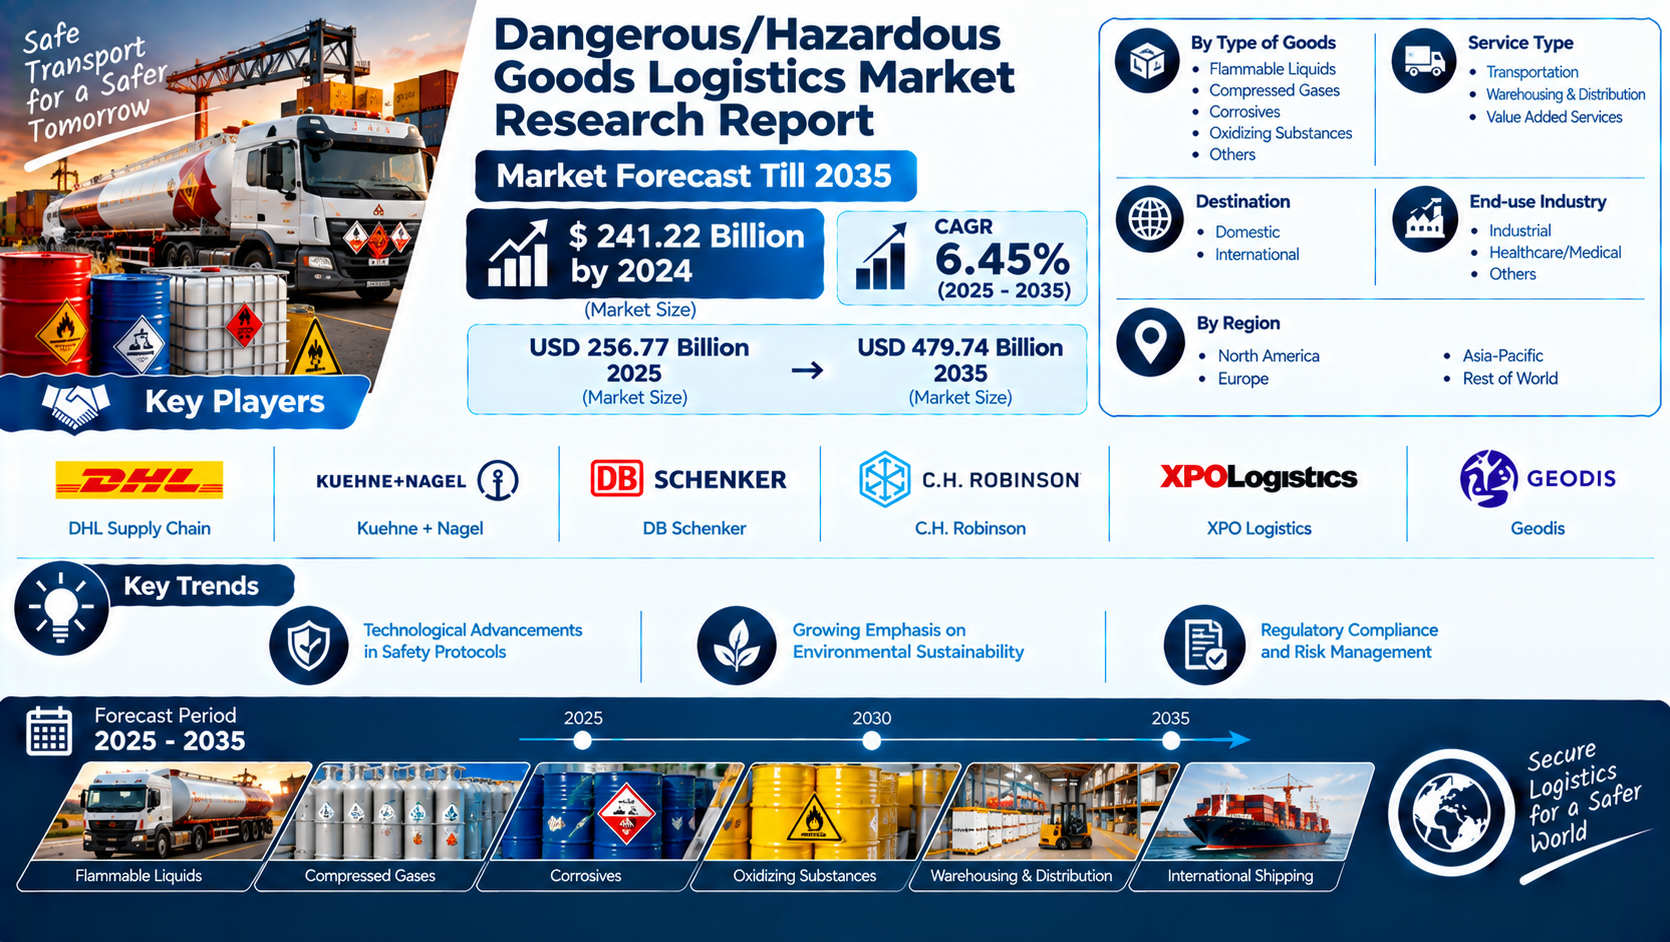
According to Market Research Future® (MRFR), the Dangerous/Hazardous Goods Logistics Market is projected to increase from USD 256.77 billion in 2025 to USD 479.74 billion by 2035, registering a compound annual growth rate (CAGR) of 6.45% during the 2025–2035 forecast period. The market was valued at USD 241.22 billion in 2024. Its development is closely linked to industrial supply chains, specialized transportation requirements, regulatory compliance, and the need to manage risks associated with moving and storing hazardous materials.
Dangerous and Hazardous Goods Logistics Market Overview
Dangerous and hazardous goods logistics covers the specialized handling, transportation, warehousing, and distribution of materials that may pose risks to people, property, or the environment. These goods can include flammable liquids, compressed gases, corrosive substances, oxidizing substances, and other regulated materials. Their movement requires procedures designed to reduce exposure, prevent incidents, and maintain compliance with applicable transportation and storage requirements.
Unlike conventional freight, hazardous goods logistics often requires additional documentation, suitable packaging, trained personnel, compatible storage arrangements, and emergency-response planning. Requirements differ according to the substance, its classification, the route, the mode of transport, and the jurisdiction involved. As a result, customers frequently rely on logistics providers with relevant operating expertise and established safety systems.
The market's forecast expansion reflects the continued movement of regulated materials through industrial and healthcare supply chains. However, growth depends not only on shipment volumes but also on the cost of compliance, availability of specialized infrastructure, operational reliability, and the ability to manage risks across domestic and international routes.
Market Segmentation by Goods and Services
The market is segmented by type of goods into flammable liquids, compressed gases, corrosives, oxidizing substances, and others. Each category creates different handling and transportation requirements. Flammable liquids require controls intended to reduce ignition risks, while compressed gases need suitable containers, secure handling, and protection against damage or inappropriate storage conditions. Corrosive substances require compatible packaging and handling procedures to reduce the risk of chemical injury or material damage. Oxidizing substances may intensify combustion and therefore need appropriate segregation and safety controls.
These differences make classification, documentation, and staff training central to logistics operations. Providers must follow the requirements applicable to the specific goods being transported rather than applying a single procedure to every shipment.
By service type, the market includes transportation, warehousing and distribution, and value-added services. Transportation covers the movement of hazardous materials by suitable logistics networks. Warehousing and distribution require facilities, inventory controls, segregation practices, and emergency procedures appropriate to the materials stored. Value-added services may include specialized packaging, documentation support, shipment monitoring, and coordination of compliance-related processes, depending on provider capabilities and customer requirements.
Domestic and International Logistics Demand
The destination segment includes domestic and international movements. Domestic shipments must comply with the rules applicable within the relevant country and transport mode. International movements add complexity because shipments may cross jurisdictions with different documentation requirements, classification rules, border procedures, and permitted handling practices.
Cross-border logistics can require coordination among shippers, carriers, customs intermediaries, warehouse operators, and receiving facilities. Accurate shipment information and consistent documentation help reduce delays and support traceability. Logistics providers with established international networks may be able to coordinate these activities more efficiently, although the requirements remain specific to each shipment and route.
End-use industries are categorized into industrial, healthcare and medical, and others. Industrial demand can arise from the movement of chemicals, gases, and other regulated inputs used in manufacturing and processing. Healthcare and medical supply chains may require logistics services for certain chemicals, gases, and other materials used in healthcare operations or production. Additional end uses contribute to demand where regulated goods must be moved safely and reliably.
Key Market Trends
Technological advancements in safety protocols are shaping the way logistics companies monitor shipments and manage operational risks. Digital documentation, shipment tracking, inventory systems, and communication tools can improve visibility across supply chains. When integrated with suitable operating procedures, these technologies can help teams identify delays, maintain records, and coordinate responses to changing conditions.
Technology does not replace physical safeguards, trained personnel, or regulatory obligations. Its value depends on accurate data, reliable systems, staff competency, and integration with the procedures required for the goods involved. Providers must also consider cybersecurity, system availability, and the quality of information shared among logistics partners.
Environmental sustainability is another important trend. Companies face pressure to improve transport efficiency, reduce unnecessary movements, optimize routes, and manage packaging and operational waste. Such initiatives must be evaluated alongside safety requirements because the most efficient route or handling arrangement is not necessarily appropriate for every hazardous shipment. Environmental improvements are most effective when they complement, rather than compromise, risk controls.
Regulatory compliance and risk management remain fundamental to this market. Logistics operators must keep processes aligned with applicable rules and maintain procedures for incident prevention, emergency response, staff training, and shipment documentation. As requirements differ by material and jurisdiction, continuous review is necessary.
Growth Opportunities and Industry Challenges
Industrial activity and the continued need to move regulated materials provide opportunities for logistics providers with specialized capabilities. Customers may seek partners that can coordinate transportation, storage, documentation, and distribution under consistent operating standards. Healthcare and medical supply chains also create requirements for reliable handling of relevant regulated materials.
Investment in monitoring systems, staff development, warehouse controls, and compliance management can strengthen service quality. Providers that demonstrate dependable execution and clear communication may be better positioned to build long-term relationships with customers whose operations depend on timely and compliant deliveries.
Nevertheless, the sector faces significant operational challenges. Specialized vehicles, storage facilities, protective equipment, training, insurance, and compliance systems can increase costs. Incidents may result in environmental harm, injuries, asset damage, service interruptions, and legal consequences. Logistics companies therefore need to evaluate risks throughout the shipment lifecycle, including loading, transit, unloading, and storage.
Regional Market Perspective
The report covers North America, Europe, Asia-Pacific, and the Rest of the World. Regional demand and operating conditions are influenced by industrial activity, trade flows, infrastructure, regulatory frameworks, and the availability of specialized logistics services.
North America and Europe have established industrial and distribution networks in which compliance and risk management are important operational considerations. Asia-Pacific offers opportunities associated with industrial supply chains and cross-border trade, although requirements and infrastructure differ among countries. Growth in other regions depends on industrial development, transport connectivity, regulatory capacity, and access to suitable storage and handling facilities.
Competitive Landscape and Outlook
Key companies identified in the market include DHL Supply Chain, Kuehne + Nagel, DB Schenker, C.H. Robinson, XPO Logistics, and Geodis. Competitive factors include network reach, service reliability, specialized handling capabilities, regulatory expertise, shipment visibility, and risk-management procedures.
The dangerous and hazardous goods logistics market is forecast to grow from USD 256.77 billion in 2025 to USD 479.74 billion by 2035, at a CAGR of 6.45%. Technology adoption, sustainability initiatives, regulatory compliance, and demand from industrial and healthcare supply chains are expected to influence market development. Providers that maintain strong safety systems while improving visibility and operational efficiency may be positioned to address evolving customer requirements.