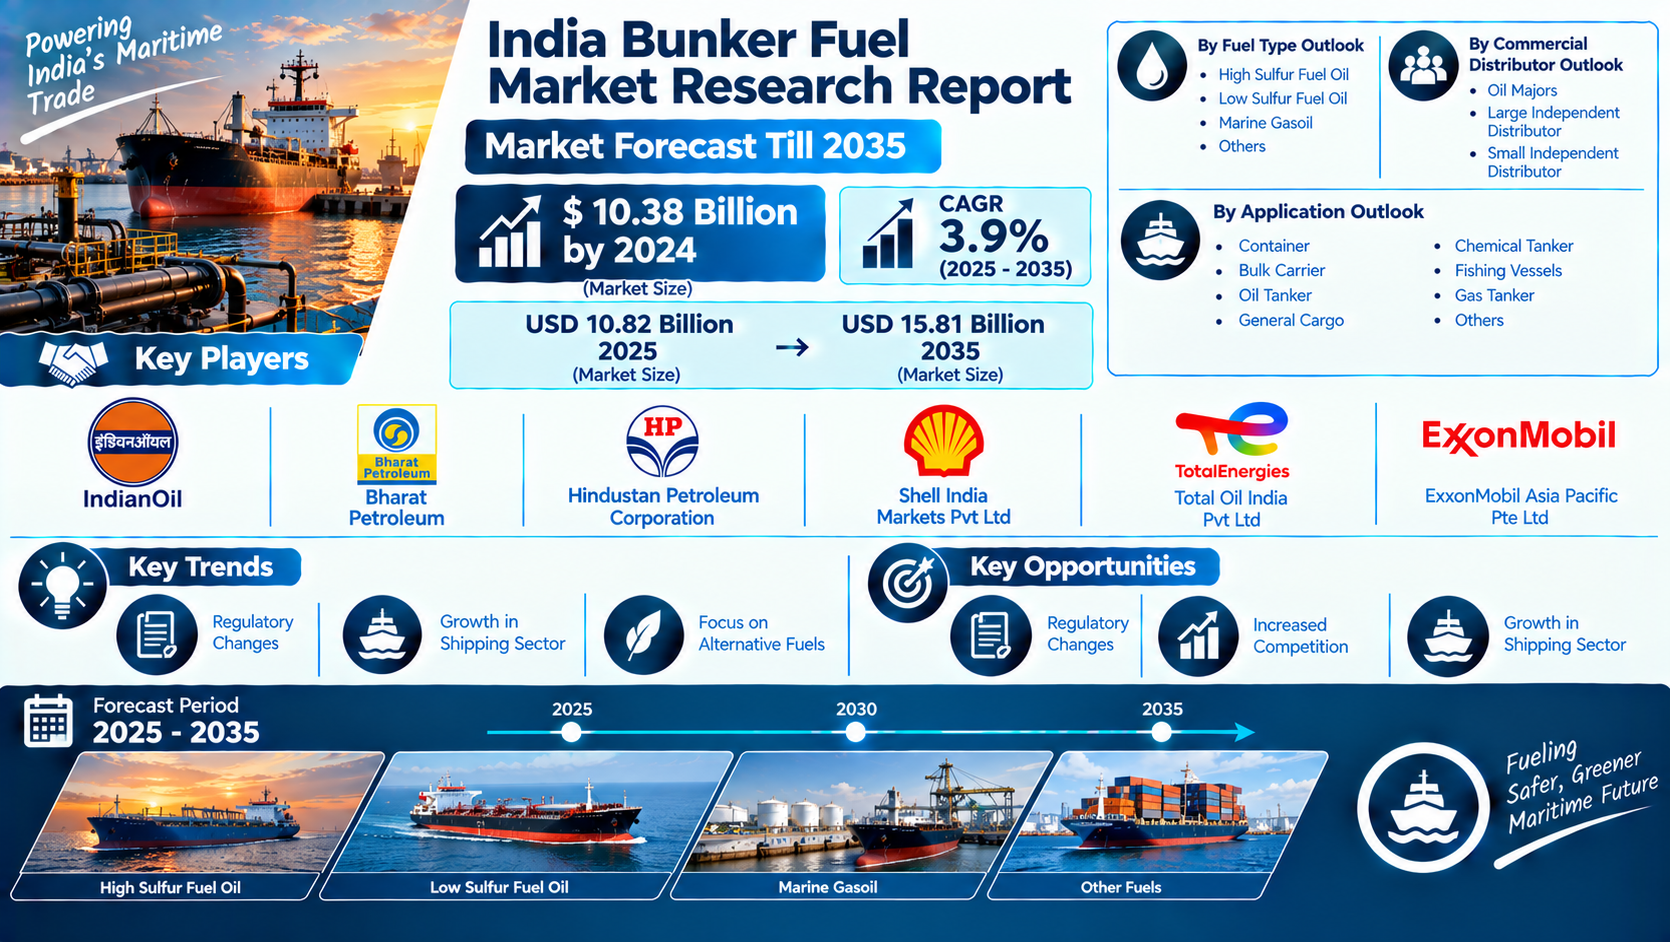
According to Market Research Future® (MRFR), the India Bunker Fuel Market was valued at USD 10.38 billion in 2024 and is projected to increase from USD 10.82 billion in 2025 to USD 15.81 billion by 2035, registering a compound annual growth rate (CAGR) of 3.9% during the forecast period from 2025 to 2035. Market development is closely linked to maritime trade, shipping-sector expansion, changing fuel regulations, and the industry's gradual consideration of alternative marine fuels.
India Bunker Fuel Market Overview
Bunker fuel refers to fuel supplied to ships for propulsion and onboard energy requirements. It is an essential component of maritime operations, supporting container vessels, bulk carriers, oil tankers, chemical tankers, and other commercial and specialized vessels. India's role in regional and international maritime trade creates demand for dependable marine fuel supply, distribution infrastructure, and services at ports and shipping hubs.
The market's performance depends on vessel activity, cargo volumes, fuel prices, regulatory requirements, and the availability of compliant fuel grades. Shipping operators must balance fuel costs with operational reliability and environmental obligations. Suppliers, meanwhile, need to manage procurement, storage, quality control, and distribution while responding to changes in customer demand and marine fuel specifications.
The projected increase from USD 10.82 billion in 2025 to USD 15.81 billion in 2035 reflects the anticipated expansion of the market over the forecast period. The reported CAGR of 3.9% indicates steady growth as maritime activity and fuel requirements evolve.
Key Market Drivers and Industry Trends
Growth in the shipping sector is a major factor influencing India's bunker fuel demand. Maritime transport supports the movement of energy products, manufactured goods, agricultural commodities, chemicals, and other cargoes. Changes in vessel traffic and cargo handling can affect the volumes of marine fuel required by commercial operators.
Container ships, bulk carriers, and tankers have different operating profiles and fuel requirements. Increased shipping activity can create opportunities for fuel suppliers, distributors, and port-based service providers. However, market expansion also depends on freight conditions, vessel efficiency, international trade activity, and the cost competitiveness of maritime transport.
Regulatory changes represent another important influence. Marine fuel specifications and emissions-related requirements affect the types of fuels that operators can use in different operating environments. Compliance can require changes in fuel sourcing, storage, handling, and documentation. For Indian suppliers, the ability to offer suitable fuel grades and maintain reliable quality can be an important competitive consideration.
The focus on alternative fuels is also shaping the industry's longer-term outlook. Shipping companies are assessing options that may help address emissions objectives and evolving environmental requirements. The pace of adoption depends on vessel compatibility, fuel availability, infrastructure investment, safety requirements, and cost. Conventional bunker fuels are therefore likely to remain relevant while the industry evaluates and develops alternative energy pathways.
Market Segmentation by Fuel Type
The India Bunker Fuel Market is segmented into high sulfur fuel oil, low sulfur fuel oil, marine gasoil, and other fuel types. These categories serve different operational and regulatory requirements.
High sulfur fuel oil remains relevant for vessels and operating arrangements where its use is permitted and suitable compliance measures are in place. Low sulfur fuel oil provides an option for meeting applicable sulfur limits, subject to the relevant fuel specifications. Marine gasoil is another marine fuel category used according to vessel requirements and operating conditions. The other category encompasses additional fuel options included in the market classification.
Demand among these fuel types is influenced by relative prices, fuel availability, engine compatibility, and environmental regulations. Suppliers must also maintain appropriate handling procedures and quality controls to ensure that delivered fuels meet contractual specifications.
Commercial Distribution and Vessel Applications
By commercial distributor, the market includes oil majors, large independent distributors, and small independent distributors. Oil majors can participate through established supply and distribution networks, while independent distributors serve customers according to their procurement capabilities, geographic reach, and service offerings. Competition can involve pricing, availability, delivery reliability, fuel quality, and the ability to serve vessels within port schedules.
The application segment includes container vessels, bulk carriers, oil tankers, general cargo vessels, chemical tankers, fishing vessels, gas tankers, and other vessel categories. Container ships transport goods through scheduled maritime networks, while bulk carriers move commodities such as minerals and agricultural products. Oil and chemical tankers require fuel supply arrangements that support their specialized operations. General cargo ships, fishing vessels, and gas carriers contribute additional sources of demand.
Different vessel categories have varying consumption patterns based on size, engine configuration, route, speed, and time spent at sea. Consequently, bunker fuel suppliers must adapt service and delivery arrangements to the requirements of different shipping customers.
Competitive Landscape and Growth Opportunities
Key companies identified in the report include Indian Oil Corporation, Bharat Petroleum Corporation, Hindustan Petroleum Corporation, Shell India Markets Pvt Ltd, Total Oil India Pvt Ltd, and ExxonMobil Asia Pacific Pte Ltd. These participants operate within a market where procurement, distribution capacity, customer relationships, and compliance with fuel requirements can influence competitiveness. The supplied information does not establish individual market shares or rankings.
Growth opportunities include shipping-sector expansion, regulatory changes, and increased competition. Greater vessel activity can strengthen demand for dependable bunker supply services. Regulatory developments can create opportunities for distributors capable of providing compliant fuel grades and supporting customers through changing requirements. Competition may also encourage suppliers to improve service reliability, pricing strategies, and operational efficiency.
Outlook Through 2035
The India Bunker Fuel Market is projected to reach USD 15.81 billion by 2035, supported by a CAGR of 3.9% between 2025 and 2035. Its trajectory will depend on maritime trade, vessel traffic, fuel prices, environmental regulations, and the availability of alternative fuels.
Market participants that combine reliable distribution, quality management, regulatory awareness, and responsive customer service may be better positioned to address changing shipping requirements. As India continues to participate in regional and global maritime trade, bunker fuel supply will remain an important part of the marine transportation ecosystem.