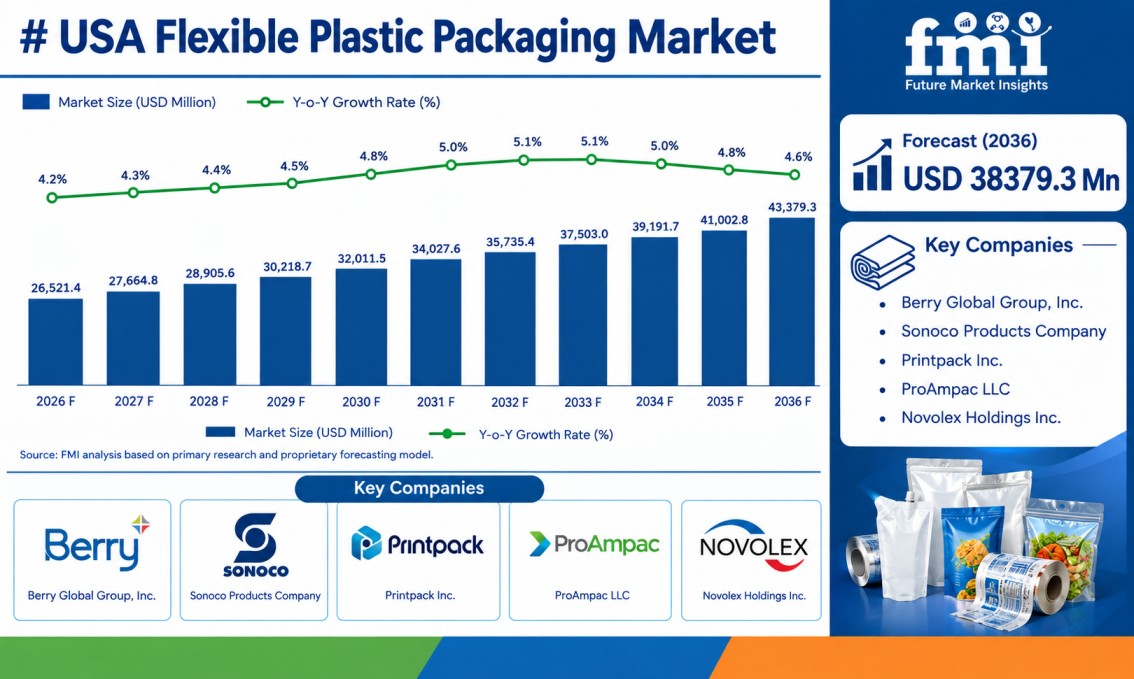
The USA flexible plastic packaging market is projected to expand from USD 26,946.4 million in 2026 to USD 38,379.3 million by 2036, registering a CAGR of 3.6% during the forecast period. According to FMI analysis, the market’s growth is increasingly being driven by rigid-to-flexible material substitution, recyclability mandates, and state-level Extended Producer Responsibility (EPR) legislation reshaping packaging procurement strategies across food, healthcare, and e-commerce industries.
The sector is entering a structural transformation phase where mono-material recyclable films, high-barrier laminates, and recycled-content flexible packaging are becoming essential for regulatory compliance and long-term market access.
USA Flexible Plastic Packaging Market Snapshot
• Market Size (2026): USD 26,946.4 Million
• Forecast Value (2036): USD 38,379.3 Million
• CAGR (2026-2036): 3.6%
• Largest Packaging Type: MAP (Modified Atmospheric Packaging) – 48.8% share
• Leading Product Type: Films & Wraps – 34.8% share
• Key Demand Sectors: Rigid-to-flexible packaging substitution
Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-gb-20250
Market Overview
The USA flexible plastic packaging market includes:
- Flexible films
- Stand-up pouches
- Flat pouches & sachets
- Laminates
- Shrink and stretch films
- Medical flexible packaging
- E-commerce mailers and bags
These formats are increasingly replacing rigid packaging because they offer:
- Lower transportation costs
- Lightweight structures
- Better material efficiency
- Improved shelf-life performance
- Enhanced convenience for consumers
According to the Flexible Packaging Association, USA flexible packaging shipments reached USD 39.7 billion in 2024, highlighting the sector’s accelerating share gains against rigid and corrugated alternatives.
Flexible Packaging Challenging Corrugated Packaging
Industry leaders increasingly view flexible packaging as a structural growth category rather than a mature packaging segment.
Dan Felton, CEO of the Flexible Packaging Association, noted that the industry could potentially surpass corrugated packaging in overall USA market share within the next five years.
This shift is particularly visible across:
- Protein packaging
- Snack foods
- Healthcare packaging
- Meal kits
- Pet food
- E-commerce delivery systems
EPR Legislation Reshaping Packaging Design
State-Level Packaging Regulations Becoming Market Drivers
The market is being fundamentally reshaped by EPR laws introduced in:
- California
- Oregon
- Colorado
- Maine
These regulations increasingly require:
- Recyclability compliance
- Recycled content integration
- Packaging recovery targets
- Circular economy alignment
California SB 54 Emerging as National Benchmark
Because national brands distribute products across multiple states, California’s SB 54 legislation is effectively becoming the de facto national packaging standard.
As a result, packaging suppliers are rapidly investing in:
- Mono-material recyclable films
- Recycle-ready laminates
- Simplified film structures
- High-barrier recyclable pouches
to maintain long-term market relevance.
Industry Consolidation Accelerating
Amcor-Berry Global Merger Transforming Industry Structure
One of the largest developments in the industry was the announcement of the merger between:
- Amcor plc
- Berry Global Group, Inc.
The all-stock transaction, valued at approximately USD 37 billion enterprise value, is expected to close by mid-2025.
Strategic Impact of Consolidation
The merger creates a packaging giant with major advantages in:
- Scale economics
- Recyclability R&D
- Mono-material conversion
- Resin procurement
- EPR compliance capability
FMI analysts indicate that future competitiveness will increasingly depend on the ability to finance:
- Advanced recycling investments
- Sustainable material conversion
- Recycled-content sourcing programs
which may place mid-tier converters under margin pressure.
Sonoco Divestiture Reshaping Competitive Landscape
In another major industry move:
Sonoco Products Company agreed to sell its Thermoformed and Flexibles Packaging business to Toppan Holdings for approximately USD 1.8 billion.
This transaction reflects broader industry repositioning toward:
- High-margin recyclable formats
- Scale optimization
- Portfolio specialization
Material Innovation Driving Market Evolution
Mono-Material Films Becoming Strategic Priority
Traditional multi-layer laminates remain difficult to recycle due to incompatible polymer structures.
As a result, converters are shifting toward:
- Mono-material PE films
- Recyclable PP laminates
- Recycle-ready barrier structures
- High-performance single-resin packaging
Speak to Analyst: Customize insights for your Business Strategy: https://www.futuremarketinsights.com/customization-available/rep-gb-20250
High-Barrier Recyclable Films Commanding Premium Pricing
A major pricing asymmetry is emerging between:
| Packaging Type | Approximate Price |
| Commodity PE Films | USD 1.50–2.50/kg |
| High-Barrier Recyclable Laminates | USD 4–8/kg |
This reflects the growing value of compliance-ready packaging solutions.
Food Packaging Dominating Market Demand
Food Segment Expected to Grow at 5.1% CAGR
Food applications remain the largest demand generator because flexible packaging offers:
- Superior shelf-life extension
- Moisture barriers
- Oxygen protection
- Lightweight shipping efficiency
- Reduced food waste
Modified Atmospheric Packaging (MAP) Leading Packaging Type
MAP is projected to hold 48.8% value share by 2036.
These systems are increasingly used for:
- Fresh meat
- Poultry
- Seafood
- Organic produce
- Meal kits
- Ready-to-eat foods
because they extend shelf life while maintaining freshness.
Films and Wraps Remaining Core Product Category
Films & Wraps to Hold 34.8% Share
Films and wraps dominate because of their:
- High barrier properties
- Lightweight construction
- Cost efficiency
- Versatility across industries
These materials are widely used in:
- Snack packaging
- Frozen foods
- Bakery products
- Fresh produce
- Industrial pallet wrapping
Sustainability Driving New Film Development
Demand is increasing for:
- Recyclable stretch films
- Compostable flexible films
- Biodegradable wraps
- Post-consumer recycled content films
to align with sustainability goals.
E-Commerce Expanding Flexible Packaging Demand
Online Retail Increasing Need for Lightweight Packaging
E-commerce growth is accelerating demand for:
- Poly mailers
- Bubble mailers
- Flexible protective films
- Lightweight shipping bags
Major retailers such as:
- Amazon
- Walmart
continue adopting flexible packaging formats to reduce:
- Shipping weight
- Transportation costs
- Packaging waste
- Parcel dimensional charges
Recycling Challenges Remain Major Industry Constraint
Multi-layer Film Structures Difficult to Recycle
One of the biggest industry restraints remains the recyclability of flexible packaging.
Current challenges include:
- Mixed polymer structures
- Food contamination
- Limited collection systems
- Sorting complexity
- Insufficient recycling infrastructure
Recycled Flexible Film Supply Still Limited
According to FMI analysis:
- Recycled content remains below 10% of total flexible film supply
- Mechanical recycling capacity remains constrained
- Chemical recycling investments are still scaling
This creates a supply bottleneck for EPR compliance.
Geographic Market Dynamics
Southeast and Midwest Leading Manufacturing Capacity
The largest flexible packaging manufacturing hubs are concentrated in:
- Southeast USA
- Midwest USA
due to:
- Resin availability
- manufacturing infrastructure
- logistics connectivity
- lower operating costs
California Dominating Consumption and Regulation
California remains:
- the largest consumer market
- the most influential regulatory environment
making it strategically important for packaging suppliers.
Explore In-Depth Packaging Market Insights: https://www.futuremarketinsights.com/industry-analysis/packaging
Competitive Landscape
The USA flexible packaging industry is becoming increasingly concentrated around large-scale converters capable of supporting:
- recyclability investments
- national compliance programs
- advanced barrier technologies
- recycled-content sourcing
Major Companies Operating in the Market
Key players include:
- Amcor plc
- Berry Global Group, Inc.
- Sealed Air Corporation
- Sonoco Products Company
- ProAmpac LLC
- Novolex Holdings Inc.
- Printpack Inc.
- American Packaging Corporation
- Sigma Plastics Group Inc.
- C-P Flexible Packaging
Strategic Recommendations for Industry Stakeholders
Accelerate Mono-Material Film Development
Converters should prioritize:
- PE-based recyclable laminates
- mono-material pouch systems
- recycle-ready barrier technologies
to maintain future compliance.
Expand Recycling Infrastructure Partnerships
Companies should invest in:
- chemical recycling partnerships
- mechanical recycling systems
- recycled-content sourcing programs
to secure future resin availability.
Focus on Compliance-Driven Procurement
Future purchasing decisions will increasingly depend on:
- recyclability certification
- EPR readiness
- recycled content verification
- carbon reduction performance
rather than price alone.
Explore Industry Insights: https://www.futuremarketinsights.com/industry-analysis
Future Outlook
The USA flexible plastic packaging market is expected to continue evolving toward:
- recyclable mono-material structures
- high-barrier sustainable laminates
- circular packaging systems
- recycled-content flexible films
Growth is expected to remain strongest across:
- food packaging
- healthcare packaging
- e-commerce delivery
- convenience foods
- premium ready-to-eat products
The industry’s long-term direction increasingly indicates that recyclability compliance is no longer a sustainability initiative—it is becoming a mandatory market access requirement.
Executive Summary
- Market projected to reach USD 38.38 billion by 2036
- CAGR forecast at 3.6% during 2026–2036
- MAP packaging expected to dominate with 48.8% share
- Films and wraps expected to hold 34.8% share
- EPR regulations reshaping packaging procurement nationwide
- Mono-material recyclable films becoming critical growth category
- Industry consolidation accelerating through mega-mergers
- Food, healthcare, and e-commerce expected to drive majority demand
- Recycling infrastructure expected to remain primary market bottleneck
Read Full Report- https://www.futuremarketinsights.com/reports/united-states-flexible-plastic-packaging-market
Have a Look at Related Research Reports on the Packaging Domain:
Demand for PCR Films in USA: https://www.futuremarketinsights.com/reports/united-states-pcr-films-market
Demand for Stretch Film Packs in USA: https://www.futuremarketinsights.com/reports/united-states-stretch-film-packs-market
Demand for MDO-PE Films in USA: https://www.futuremarketinsights.com/reports/united-states-mdo-pe-films-market
Contact Us:
Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware - 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com
About Future Market Insights (FMI)
Future Market Insights, Inc. (FMI) is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization, trusted by Fortune 500 clients and global enterprises. With operations in the U.S., UK, India, and Dubai, FMI provides data-backed insights and strategic intelligence across 30+ industries and 1200 markets worldwide.