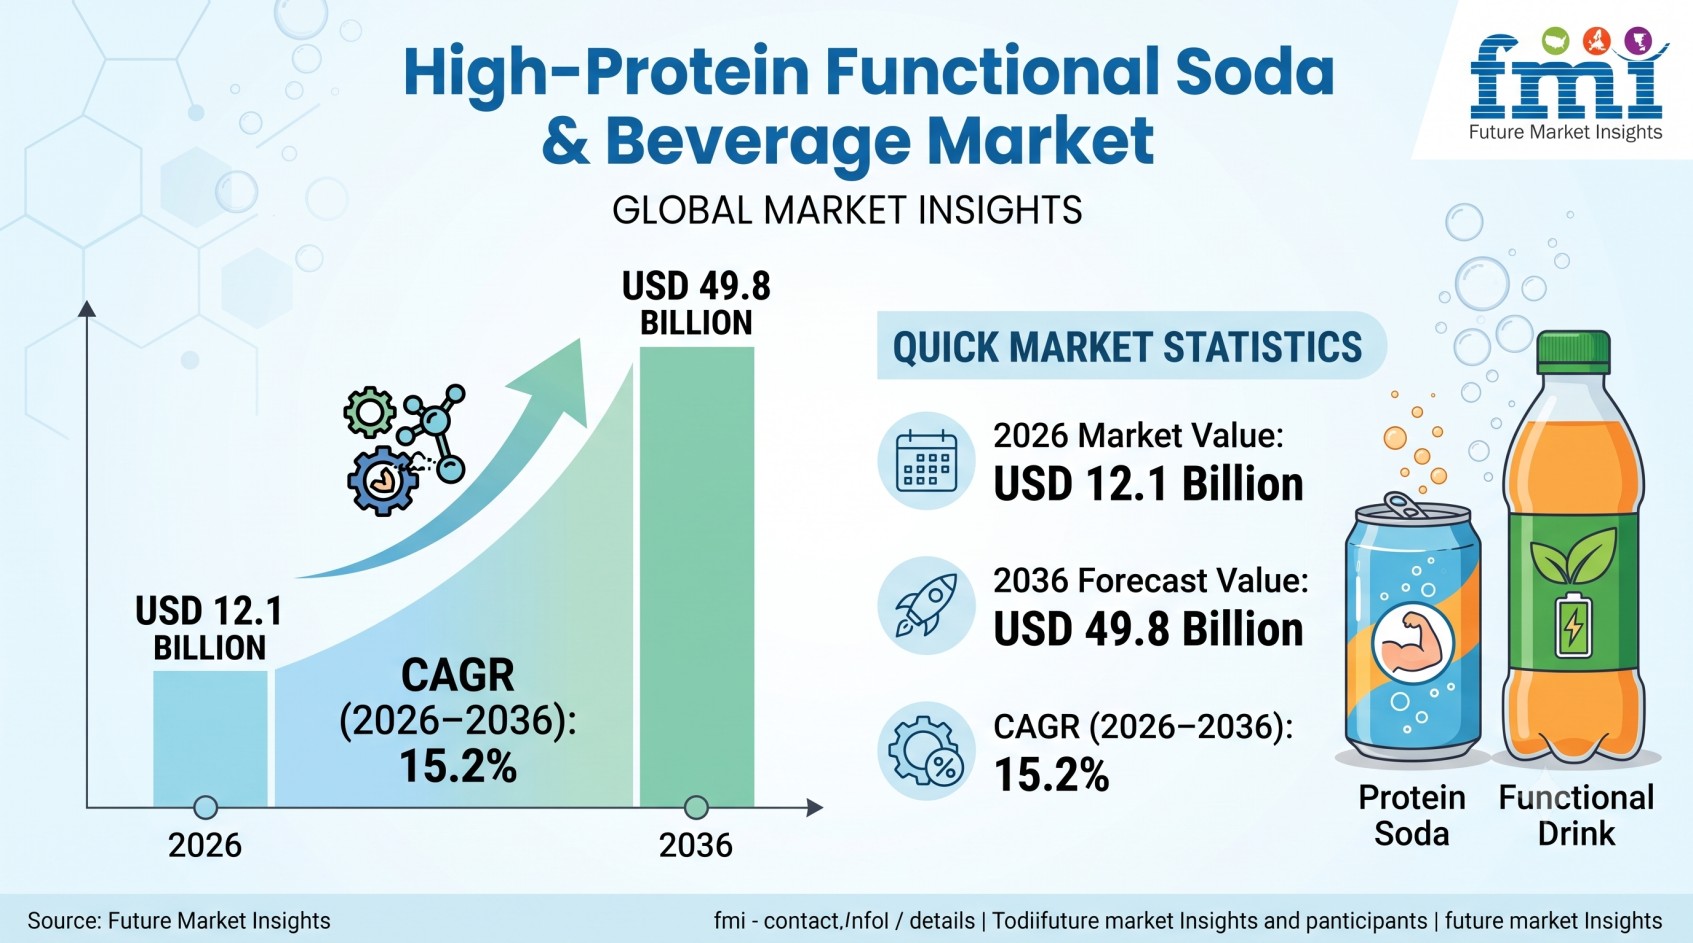
The global high-protein functional soda and beverage market is entering an accelerated, value-led expansion phase as beverage brands and ingredient formulators bridge functional carbonated refreshment with high-protein nutrition. Valued at USD 12.1 billion in 2026, the sector is projected to reach USD 49.8 billion by 2036, according to the latest research insights by Future Market Insights (FMI). The forecast implies an industry-leading compound annual growth rate (CAGR) of 15.2% over the ten-year assessment period, creating an absolute dollar growth opportunity of USD 37.7 billion. The market's momentum is driven by a fundamental formulation shift: manufacturers are transitioning from dense, milky shakes toward transparent, effervescent drinks that deliver genuine protein claims within light, low-sugar, ready-to-drink (RTD) soda profiles.
Quick Market Statistics
- 2026 market value: USD 12.1 billion
- 2036 forecast value: USD 49.8 billion
- CAGR (2026–2036):2%
- Incremental opportunity: USD 37.7 billion
- Protein soda share of product category (2026):3%
- Whey share of protein source segment (2026):2%
- Hypermarkets & supermarkets share of sales channels (2026):4%
- Canada market forecast CAGR (2026–2036):2%
- Australia market forecast CAGR (2026–2036):8%
- United States market forecast CAGR (2026–2036):4%
Request a Sample Report: https://www.futuremarketinsights.com/reports/sample/rep-gb-34278
Market Growth Is Becoming a Clarity, Carbonation, and Taste-Masking Story
A 15.2% CAGR signals high commercial momentum as protein moves into everyday snacking and refreshment occasions. However, category success requires overcoming significant food science hurdles rather than relying on nutritional positioning alone.
Traditional protein beverages depend on emulsified dairy suspensions that feel heavy and chalky. In contrast, modern consumers expect high-protein sodas to mimic mainstream carbonated soft drinks in clarity, crisp mouthfeel, and acidity. This requirement puts pressure on formulators to eliminate protein astringency, maintain solution clarity at low pH, and protect carbonation retention across typical room-temperature retail supply chains. Brands that deliver clean label claims without lingering aftertastes are converting early trial into repeat supermarket purchases.
Protein Soda Commands Finished Product Innovation
Protein soda is projected to command 45.3% of product category revenue in 2026, leading alternative formats such as RTD protein shakes and functional sparkling waters.
The format’s leadership position reflects its alignment with modern daytime refreshment habits. Consumers seeking 10g to 20g of protein per can increasingly prefer refreshing, fruity, or cola-style profiles over heavy, dessert-like milkshakes. By combining effervescence with functional macros, protein sodas appeal directly to desk workers, casual fitness enthusiasts, and flexitarian shoppers who previously avoided sports nutrition aisles.
Whey Isolates Anchor Low-pH Formulation Routes
Whey is projected to capture 53.2% of the protein source category in 2026, anchoring market formulation.
Whey protein isolate (WPI) and specialized clear whey fractions remain the gold standard due to their solubility in low-pH, acidic environments. Unlike whole milk concentrates or standard plant proteins which flocculate, sediment, and turn turbid under carbonation purified clear whey fractions stay fully dispersed. While collagen and specialized plant fractions are gaining ground in wellness and dairy-free formulations, clear whey processing remains the most dependable, scalable route to achieving clear beverage aesthetics alongside complete amino acid delivery.
Hypermarkets and Supermarkets Dominate Initial Channel Discovery
Hypermarkets and supermarkets are estimated to account for 32.4% of total sales channel revenue in 2026.
Large-format grocers serve as the primary discovery platform where consumers directly compare protein soda against conventional sodas, prebiotic tonics, and energy drinks. Visible shelf placement near chilled grab-and-go functional drinks encourages planned basket additions as well as spontaneous trials. In parallel, convenience stores and direct-to-consumer e-commerce channels serve as vital high-margin conduits for subscription-based replenishment.
Regional Analysis: North American Innovation Leads Western Expansion
Geographically, the high-protein functional soda and beverage market shows strong adoption across mature retail economies where functional wellness integration is high and retail cold chains are well established.
Canada leads the country set with an expected 13.2% CAGR through 2036. Demand is accelerated by high consumer health awareness, rapid grocery retail testing cycles, and strong local contract manufacturing capacity capable of handling carbonated canning lines.
Australia follows closely at a 12.8% CAGR, supported by an established active outdoor lifestyle culture, warm weather driving light beverage consumption, and extensive supermarket placement for wellness-oriented soft drinks.
The United States is forecast to expand at a 12.4% CAGR through 2036. The U.S. market operates as a major testing ground, backed by total national food spending exceeding USD 2.5 trillion and dynamic e-commerce fulfillment networks. Brands in this corridor actively reformulate to balance clean-label sweetness (via stevia or monk fruit) with corrected protein quality score documentation under FDA 21 CFR 101.54 guidelines.
European markets represent rigorous, compliance-led growth hubs:
- United Kingdom (12.0% CAGR): Growth is shaped by the Soft Drinks Industry Levy, which penalizes added sugar and accelerates manufacturer adoption of zero-sugar, protein-fortified alternative drinks.
- Germany (11.6% CAGR): Driven by disciplined label review, strict sweetener limits under EFSA safety evaluations, and consumer interest in functional fitness nutrition.
Competitive Landscape: Beverage Conglomerates and Ingredient Pioneers
The market features global beverage enterprises, functional soda pioneers, and specialized dairy ingredient processors collaborating to optimize formulation economics.
Key companies identified in the market include:
- PepsiCo, Inc.
- The Coca-Cola Company
- Nestlé S.A.
- Glanbia plc
- Danone S.A.
- Arla Foods Ingredients Group P/S
- OLIPOP PBC
- Cargill, Incorporated
Multinational beverage corporations (PepsiCo, The Coca-Cola Company) bring deep distribution leverage, cold-vault presence, and portfolio expansion strategies—highlighted by high-profile investments in prebiotic and functional soda platforms. In contrast, dairy ingredient specialists like Arla Foods Ingredients and Glanbia focus on the upstream science, commercializing acid-stable clear whey isolates to facilitate clarity and mouthfeel. Meanwhile, sweetener suppliers like Cargill enable balanced sugar reduction without sacrificing body or effervescence.
Key Challenges for Industry Participants
- Stringent Label Claim Substantiation: Complying with jurisdiction-specific protein quality scoring (such as PDCAAS or DIAAS) to legally validate "Good Source" or "High Protein" marketing claims on packaging.
- Acidic Astringency and Flavor Fatigue: Formulating around dry, mouth-drying astringency naturally caused by whey proteins at low pH.
- Cost Premiums of Clear Protein Isolates: Specialized fractionation and microfiltration technologies command significantly higher ingredient costs than conventional dairy or soy powders.
Strategic Opportunities Through 2036
- Hybrid Functional Profiles: Combining clear protein with prebiotic dietary fibers, nootropics, or electrolytes to deliver multi-benefit wellness tonics.
- Mainstream Soda Flavor Replicas: Launching classic cola, root beer, citrus, and ginger profiles that closely mimic traditional carbonated soft drinks.
- Clear Botanical & Plant Protein Formats: Developing ultra-filtered pea and fermented plant proteins to capture dairy-free and vegan consumers seeking clear sparkling formats.
- Single-Can Impulse Merchandising: Partnering with convenience retail networks to place chilled single cans near checkout registers to capture midday snack occasions.
What the Market Means for C-Level Decision-Makers
For beverage executives and food processors, protein soda represents the next evolutionary step in functional soft drinks. Moving beyond niche gym culture into everyday hydration requires capital investment in acid-stable protein sourcing, meticulous shelf-life and carbonation stability validation, and transparent front-of-pack claims that withstand evolving regulatory scrutiny.
Exclusive Discounts on Full Report: https://www.futuremarketinsights.com/reports/high-protein-functional-soda-and-beverage-market
Executive Takeaways
- The global high-protein functional soda and beverage market is forecast to grow from USD 12.1 billion in 2026 to USD 49.8 billion by 2036.
- The sector will record a 15.2% CAGR over the ten-year forecast window, yielding USD 37.7 billion in incremental revenue.
- Protein soda represents the leading product format, accounting for 45.3% of market share in 2026.
- Whey remains the primary protein source, capturing 53.2% of category demand due to its clarity and solubility in acidic profiles.
- Hypermarkets and supermarkets hold a 32.4% share of sales channels, acting as the primary discovery venue for consumers.
- Canada (13.2% CAGR), Australia (12.8% CAGR), and the USA (12.4% CAGR) represent the fastest-expanding national markets.
Explore More Related Studies Published by FMI Research
Lecithin Market https://www.openpr.com/news/4537768/lecithin-market-to-reach-usd-3-6-billion-by-2035-as-demand
Frozen Dough Market https://www.openpr.com/news/4537774/frozen-dough-market-to-reach-usd-32-7-billion-by-2036-as
Popcorn Market https://www.openpr.com/news/4537777/popcorn-market-to-reach-usd-14-43-billion-by-2036-as
About Future Market Insights (FMI)
Future Market Insights (FMI) delivers actionable, decision-focused market intelligence that goes beyond traditional research reports.
The company provides:
- In-depth pricing and cost benchmarking analysis
- Demand forecasting based on real industry inputs
- Procurement and buyer behavior insights
- Supply chain and trade flow intelligence
- Technology and application trend analysis across industries
FMI follows a robust bottom-up research methodology, combining insights from industry experts, procurement leaders, manufacturers, and technical professionals to ensure accurate and practical market intelligence.
For Press & Corporate Inquiries
Rahul Singh, AVP - Marketing and Growth Strategy
Future Market Insights,
Inc. +1-347-918-3531
For Sales: sales@futuremarketinsights.com
For Media: Rahul.singh@futuremarketinsights.com