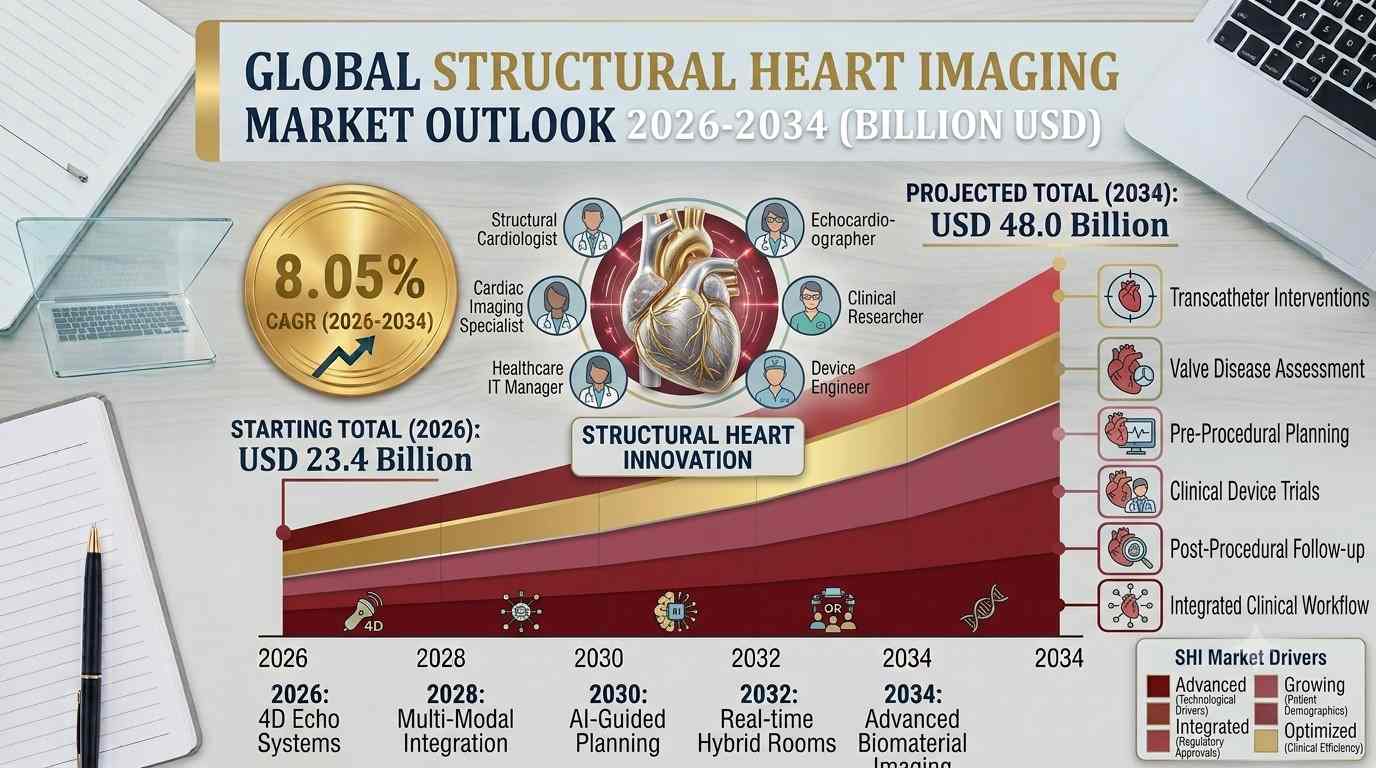
According to IMARC Group, the global structural heart imaging market size reached USD 23.4 Billion in 2025 and is projected to reach USD 48.0 Billion by 2034, expanding at a CAGR of 8.05% during 2026–2034. This remarkable growth trajectory underscores the critical role of imaging technologies in enabling safer, more effective structural heart interventions and the growing global burden of cardiovascular disease.
Structural Heart Imaging Industry Overview
Structural heart imaging is a specialized diagnostic discipline focused on generating detailed anatomical and functional visualizations of cardiac structures — including heart valves, chambers, walls, and surrounding vasculature. Unlike conventional cardiac imaging, SHI is purpose-built to support both diagnostic assessment and procedural guidance during complex interventional and surgical cardiac procedures.
The two primary imaging modalities driving the market include:
- Echocardiography (Echocardiogram): The dominant imaging modality, using high-frequency sound waves to produce real-time images of heart structures. It is essential for TAVR, TMVR, and LAAC procedure planning and intraoperative guidance.
- Angiography (Angiogram): Including CT angiography and MRI, providing detailed vascular and structural mapping critical for pre-procedural planning and post-procedural assessment.
SHI solutions are widely deployed across hospitals, cardiac centers, specialty clinics, catheterization laboratories, ambulatory surgical centers, and diagnostic centers — enabling cardiologists and cardiovascular surgeons to deliver more precise, less invasive, and more effective care for patients with structural heart diseases.
Global Market Overview & Structural Heart Imaging Market Size Statistics
Below are the key statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020–2025 |
| Forecast Period | 2026–2034 |
| Market Size in 2025 | USD 23.4 Billion |
| Market Forecast in 2034 | USD 48.0 Billion |
| Market Growth Rate (2026–2034) | 8.05% CAGR |
| Largest Region | North America |
Request for a Sample Report for Detailed Structural Heart Imaging Market Analysis: https://www.imarcgroup.com/structural-heart-imaging-market/requestsample
Key Market Drivers & Structural Heart Imaging Market Trends in 2026
Several powerful macro and micro factors are shaping the structural heart imaging landscape and accelerating market expansion globally:
- Rising Prevalence of Cardiovascular and Congenital Heart Diseases
The escalating global burden of cardiac diseases—including valvular heart disease, coronary artery disease, congenital heart defects, and heart failure—is the primary catalyst for structural heart imaging market growth . Lifestyle-related risk factors such as obesity, diabetes, hypertension, and sedentary behaviors are contributing to a surge in structural heart conditions, driving demand for advanced imaging-guided interventions worldwide.
- Rapid Adoption of Minimally Invasive Cardiac Procedures
The widespread adoption of transcatheter procedures—particularly Transcatheter Aortic Valve Replacement (TAVR) and Transcatheter Mitral Valve Repair (TMVR)—is significantly boosting demand for high-precision structural heart imaging. These procedures rely entirely on real-time echocardiographic and fluoroscopic imaging for safe device navigation and deployment, making SHI technologies indispensable in modern catheterization laboratories.
- Technological Advancements in Imaging Systems
Continuous innovations in imaging hardware and software are transforming structural heart imaging market trends. The integration of 3D and 4D echocardiography, artificial intelligence-powered image analysis, and fusion imaging combining multiple modalities (echo + CT + fluoroscopy) is improving procedural accuracy, reducing complications, and improving patient outcomes — creating strong demand for next-generation SHI platforms.
- Expanding Medical Tourism and International Healthcare Access
The rapid growth of global medical tourism — particularly in Asia Pacific, Middle East, and Latin America — is driving investments in advanced cardiac imaging infrastructure. International patients seeking complex cardiac interventions at competitive costs are fueling demand for state-of-the-art SHI technologies at hospitals and cardiac centers in emerging markets.
- Increasing Healthcare Expenditure and Infrastructure Investment
Governments and private healthcare organizations worldwide are significantly increasing investments in cardiovascular healthcare infrastructure, diagnostic equipment, and cardiac intervention capabilities. These investments are directly translating into greater adoption of advanced structural heart imaging systems across hospitals, specialty cardiac centers, and ambulatory surgical facilities.
- Growing Focus on Early Diagnosis and Preventive Cardiac Care
Rising health consciousness among consumers, combined with healthcare policies promoting preventive care and early disease detection, is driving greater utilization of structural heart imaging for screening and early-stage diagnosis. Early detection of structural abnormalities enables timely interventions, improving patient outcomes and driving market penetration across diverse healthcare settings.
Key Market Segmentation
By Imaging Modality
- Echocardiogram – Largest Segment
Echocardiography holds the dominant share in the structural heart imaging market due to its real-time imaging capability, non-invasive nature, widespread availability, and critical role in guiding transcatheter cardiac procedures. Transesophageal echocardiography (TEE) in particular is the gold standard for intraoperative guidance in TAVR, TMVR, and LAAC procedures.
- Angiogram (CT & MRI)
CT angiography and cardiac MRI are increasingly utilized for pre-procedural structural assessment, offering superior 3D anatomical detail for surgical planning in TAVR, SAVR, and complex congenital heart disease interventions.
By Procedure Type
- Transcatheter Aortic Valve Replacement (TAVR) – Largest Segment
- Surgical Aortic Valve Replacement (SAVR)
- Transcatheter Mitral Valve Repair (TMVR)
- Left Atrial Appendage Closure (LAAC)
- Annuloplasty
- Valvuloplasty
- Others
TAVR remains the largest procedure type driving SHI adoption, as every TAVR procedure requires comprehensive pre-procedural CT imaging and intraoperative echocardiographic guidance, creating a consistent and high-volume demand for structural heart imaging solutions.
By Application
- Diagnosis – Primary Application
- Surgery (Procedural Guidance)
While diagnostic applications represent the broader use case for structural heart imaging, the surgical/procedural guidance segment is experiencing the fastest growth, driven by the exponential increase in transcatheter cardiac interventions requiring real-time imaging support.
By End User
- Hospitals – Largest Segment
- Specialty Clinics
- Cardiac Centers
- Diagnostic Centers
- Ambulatory Surgical Centers
- Catheterization Laboratories
- Others
Hospitals account for the largest share of structural heart imaging adoption due to their high procedural volumes, comprehensive cardiac surgery capabilities, and ability to invest in advanced multi-modality imaging platforms. Cardiac catheterization laboratories represent the fastest-growing end-user segment, reflecting the rapid expansion of transcatheter cardiac interventions globally.
Regional Market Analysis
| Region | Key Highlights |
| North America – Largest | United States & Canada; highly developed cardiovascular healthcare ecosystem, high TAVR/TMVR procedure volumes, strong adoption of advanced echocardiography and CT imaging, robust reimbursement frameworks, leading medical device companies |
| Europe | Germany, France, UK, Italy, Spain, Russia; aging population driving structural heart disease prevalence, mature public healthcare infrastructure, growing adoption of hybrid catheterization laboratories, supportive regulatory environment for cardiac devices |
| Asia Pacific | China, Japan, India, South Korea, Australia, Indonesia; fastest-growing regional market, rapidly expanding cardiac care infrastructure, rising medical tourism, increasing government healthcare investment, growing prevalence of rheumatic heart disease and congenital defects |
| Latin America | Brazil, Mexico; Brazil is the largest LatAm cardiac imaging market, growing demand for advanced SHI solutions as cardiac surgical and interventional programs expand across major urban healthcare centers |
| Middle East & Africa | UAE, Saudi Arabia, South Africa; healthcare modernization initiatives, rising cardiovascular disease burden, growing medical tourism driving demand for advanced cardiac imaging infrastructure in specialty hospitals and cardiac centers |
Connect for Detailed Structural Heart Imaging Market Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=5127&flag=C
Leading Players in the Structural Heart Imaging Industry
The global structural heart imaging market features a competitive landscape of leading medical imaging companies and specialized cardiac device manufacturers. Key companies covered in the IMARC Group report include:
- Abbott Laboratories
- Boston Scientific Corporation
- Canon Medical Systems Corporation
- Circle Cardiovascular Imaging Inc.
- Esaote SPA
- FUJIFILM Holdings Corporation
- Koninklijke Philips NV
- Mindray Medical India Pvt. Ltd.
- Samsung Healthcare
- Shimadzu Corporation
- Siemens Healthineers
The report includes comprehensive competitive analysis covering market structure, player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant for the structural heart imaging industry.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Technology, Construction, Healthcare, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104