Technology, Efficiency, and the Future of Gas Power Plants
Europe’s natural gas generation fleet is entering a period in which operational performance and flexibility may matter as much as total installed capacity. Wind and solar additions alter dispatch patterns, electrification can increase demand, and grid constraints create local reliability challenges. Gas-fired assets can respond to some of these pressures, but their economic position depends on efficiency, fuel costs, carbon rules, and the availability of alternative flexibility.
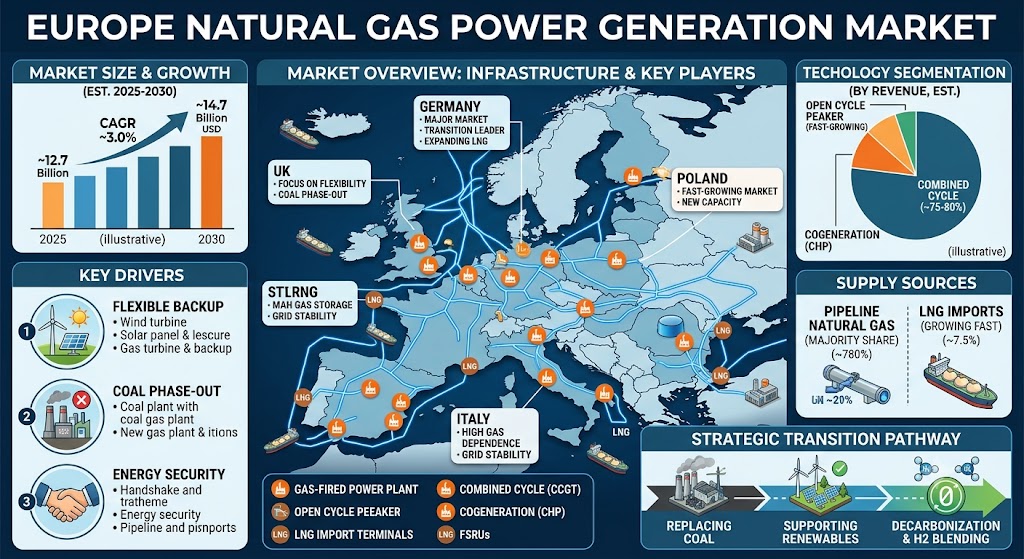
Combined-cycle power plants use a gas turbine and a steam cycle to recover heat, generally delivering better fuel efficiency than simple-cycle units. This configuration can be valuable when a plant runs for extended periods. Open-cycle turbines usually sacrifice efficiency for speed and operational simplicity, making them useful during peaks or sudden shortfalls. Plant owners should match technology to expected duty cycles rather than assume one design is suitable for every market.
The Europe Natural Gas Power Generation Market Share can be understood in several ways, including the proportion of installed capacity, electricity output, fuel use, or revenue attributable to different technologies and operators. These measures are not interchangeable. A company may own a substantial share of capacity but generate a smaller share of annual electricity if its assets operate mainly during scarcity periods. Clear definitions are essential for meaningful comparisons.
Operational upgrades can improve performance across an existing fleet. Turbine inspections, compressor improvements, heat-recovery optimisation, improved combustion controls, and predictive maintenance can reduce outages and fuel use. Digital tools can help operators forecast demand, monitor component health, and schedule maintenance during lower-value periods. The benefits depend on asset condition and operating profile, so investment cases should use measured baseline performance and realistic savings estimates.
Flexibility has become a system-level requirement. Gas plants can increase or decrease output, but their practical ramp rates, start times, minimum stable loads, and cycling costs vary. Frequent starts can increase wear and maintenance needs. Plant contracts and market bids should reflect these realities so that flexibility revenues are not overstated. Coordination with grid operators is also important when local congestion limits the ability to deliver power.
Competing technologies continue to improve. Batteries offer rapid response and can shift energy over several hours, while pumped hydro may provide longer-duration flexibility where geography permits. Demand response can reduce peaks, and interconnectors allow countries to share resources when capacity is available. Gas generation may remain valuable for longer periods of low renewable output, but this advantage must be assessed against fuel supply risk, emissions, and total system cost.
Decarbonisation planning should distinguish near-term efficiency from structural change. A more efficient plant burns less gas per megawatt-hour, yet still emits carbon dioxide. Hydrogen conversion can require significant equipment and infrastructure changes, and the climate value depends on how hydrogen is produced. Carbon capture may reduce plant emissions but introduces energy penalties and transport and storage requirements. Both options need detailed technical and commercial validation.
Supply resilience is a further operating concern. Plant availability depends on fuel delivery, pipeline capacity, storage, maintenance planning, spare parts, and trained personnel. Weather events or network disruptions can coincide with periods of high electricity demand. Scenario exercises should test fuel interruptions and outages, while procurement strategies should balance price, flexibility, and reliability rather than focus solely on the cheapest nominal supply.
Market participants should monitor dispatch hours, heat rates, start frequency, unplanned outage rates, balancing prices, capacity-auction outcomes, and competing storage additions. These indicators help reveal whether an asset is delivering the services for which it was designed. Comparisons should account for country-specific market structures and weather conditions, since continental averages can hide important differences.
The future fleet will likely combine high-efficiency plants, flexible peaking assets, upgrades, and retirements. Some facilities may retain value because they serve constrained regions or cover extended shortages; others may be displaced by cheaper flexibility or face unacceptable emissions exposure. Evidence and planning will identify assets that strengthen the electricity system reliably.