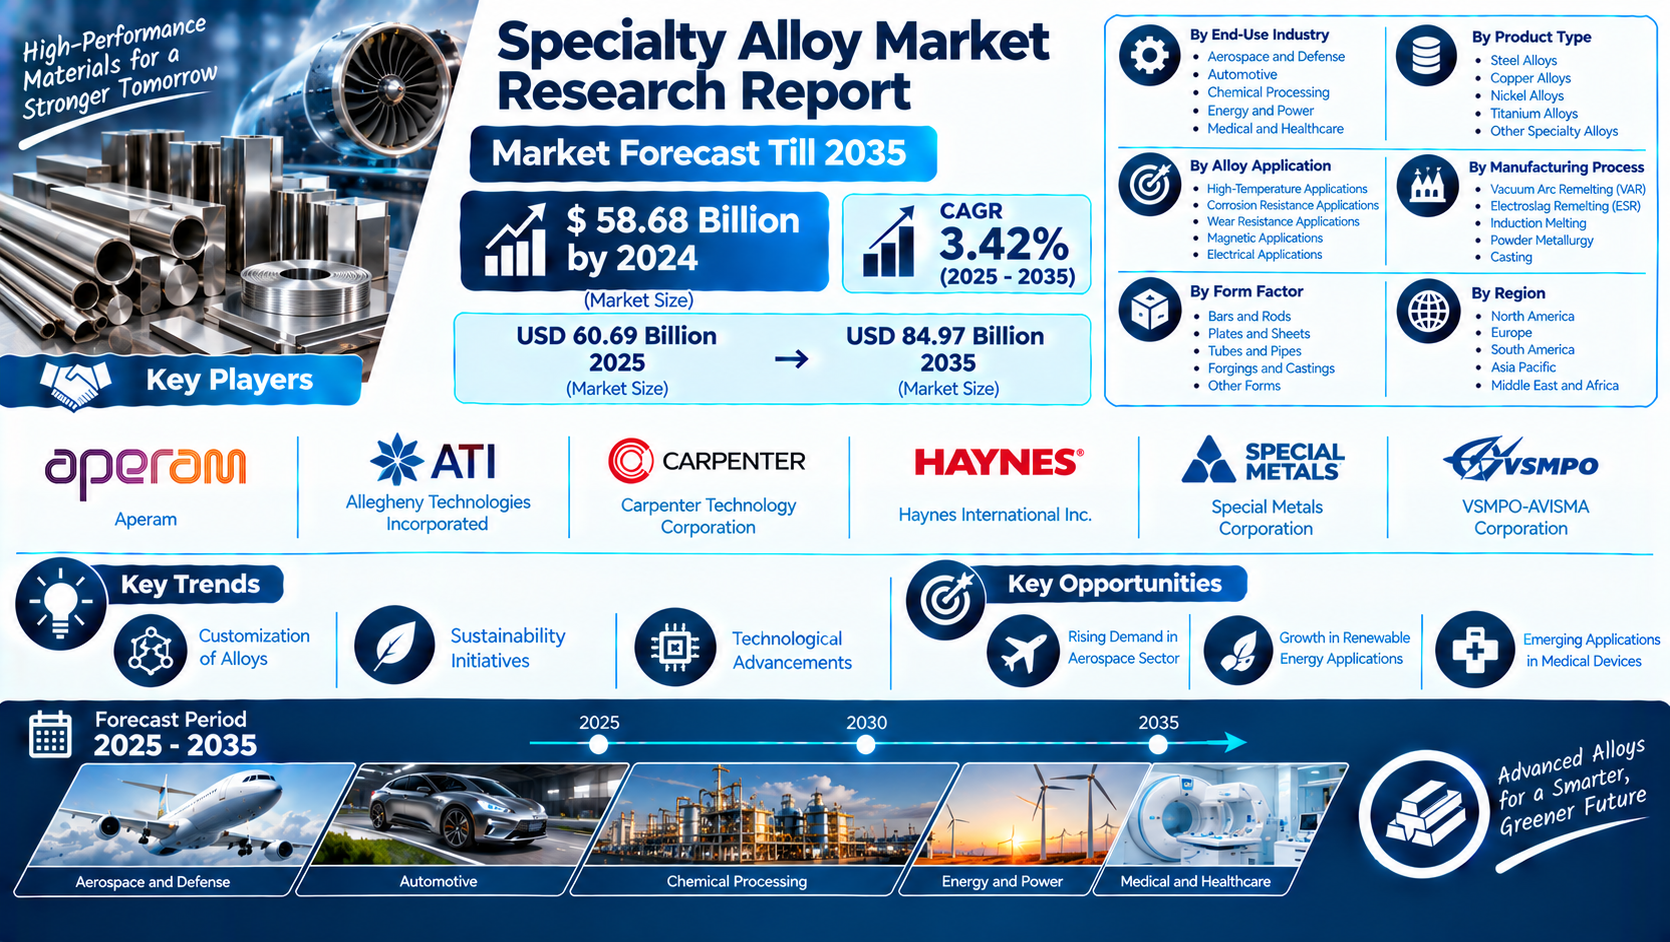
According to Market Research Future® (MRFR), the Specialty Alloy Market was valued at USD 58.68 billion in 2024 and is projected to increase from USD 60.69 billion in 2025 to USD 84.97 billion by 2035, registering a compound annual growth rate (CAGR) of 3.42% during the forecast period from 2025 to 2035. Market development is supported by demand for materials that deliver specialized performance in aerospace and defense, automotive manufacturing, chemical processing, energy and power, and medical and healthcare applications.
Specialty Alloy Market Overview
Specialty alloys are engineered metallic materials developed to provide specific properties beyond those typically required from conventional metals. Depending on their composition and processing, these materials can offer high-temperature performance, corrosion resistance, wear resistance, magnetic characteristics, or electrical functionality. Their suitability for demanding operating environments makes them important to industries where material reliability, durability, and performance can influence equipment efficiency and service life.
The market encompasses several alloy families, including steel alloys, copper alloys, nickel alloys, titanium alloys, and other specialty alloys. Each category serves different technical requirements. Nickel and titanium alloys, for example, may be selected for demanding temperature, strength, or corrosion conditions, while copper alloys can be relevant to applications requiring particular electrical or thermal properties. Actual selection depends on the composition, operating environment, engineering design, and applicable industry specifications.
Key Market Drivers and Trends
Customization of alloys is an important market trend. Industrial customers frequently require materials designed for specific combinations of temperature tolerance, mechanical strength, corrosion resistance, weight, and manufacturing compatibility. Alloy producers can respond through composition adjustments, specialized processing, and closer collaboration with customers during material selection and product development.
This demand for tailored performance is particularly relevant in aerospace, defense, chemical processing, and energy infrastructure. Components in these sectors may experience elevated temperatures, corrosive substances, mechanical stress, or demanding operating cycles. Materials that meet defined performance requirements can support equipment reliability and reduce the consequences associated with premature component failure.
Sustainability initiatives are also influencing industry priorities. Manufacturers are examining resource efficiency, energy consumption, waste reduction, and opportunities to recover or recycle suitable metals. Specialty alloy production can require energy-intensive melting and processing, making operational efficiency an important consideration. The feasibility of recycling and material recovery varies by alloy composition, contamination, and available processing infrastructure.
Technological advancements provide another source of market development. Improvements in melting, refining, powder metallurgy, and material characterization can help manufacturers achieve more consistent compositions and controlled material properties. Such capabilities are relevant where components must meet demanding technical specifications. Advances in manufacturing can also expand the range of shapes and component designs that can be produced from specialty alloys.
Market Segmentation by Product and Application
By product type, the market includes steel alloys, copper alloys, nickel alloys, titanium alloys, and other specialty alloys. Steel alloys serve a wide range of industrial and structural applications where strength and durability are important. Copper alloys can be used in applications requiring electrical or thermal characteristics, while nickel alloys are relevant to demanding temperature and corrosion conditions. Titanium alloys may be selected where a combination of strength, weight, and corrosion resistance is required.
By alloy application, the market covers high-temperature applications, corrosion resistance applications, wear resistance applications, magnetic applications, and electrical applications. This segmentation reflects the functional properties that influence material selection. High-temperature alloys support components exposed to heat, while corrosion-resistant grades are relevant to chemical processing and other challenging environments. Wear-resistant alloys address friction and surface degradation, while magnetic and electrical applications require specific functional characteristics.
End-Use Industries and Manufacturing Processes
The end-use industry segment includes aerospace and defense, automotive, chemical processing, energy and power, and medical and healthcare. Aerospace and defense applications require materials that satisfy demanding performance and reliability specifications. Automotive manufacturers use specialty alloys where component strength, weight, durability, or thermal performance is important. Chemical processing applications can require resistance to corrosive environments, while energy and power infrastructure may depend on materials suited to heat, pressure, and operational stress. Medical and healthcare uses require application-specific material properties and compliance with relevant standards.
Manufacturing processes include vacuum arc remelting (VAR), electroslag remelting (ESR), induction melting, powder metallurgy, and casting. These processes serve different production requirements and influence material quality, composition control, and component design. The choice depends on the alloy, desired properties, product geometry, and customer specifications.
The market's form-factor segmentation includes bars and rods, plates and sheets, tubes and pipes, forgings and castings, and other forms. These formats support different component designs and fabrication methods, allowing specialty alloys to serve diverse industrial applications.
Regional Outlook and Competitive Landscape
The report identifies North America, Europe, South America, Asia Pacific, and the Middle East and Africa as regional markets. Regional demand is influenced by industrial production, aerospace and defense activity, infrastructure investment, manufacturing capabilities, and the development of energy projects. Differences in supply chains, technical standards, and access to specialized production facilities can also shape regional market conditions.
Key players listed in the report include Aperam, Allegheny Technologies Incorporated, Carpenter Technology Corporation, Haynes International Inc., Special Metals Corporation, and VSMPO-AVISMA Corporation. Competitive factors may include product quality, alloy-development capabilities, manufacturing consistency, technical support, and the ability to meet customer specifications. The supplied information does not establish individual market shares or company rankings.
Growth Opportunities Through 2035
The market presents opportunities through rising demand in the aerospace sector, growth in renewable energy applications, and emerging uses in medical devices. Aerospace applications can require advanced materials for components operating under demanding mechanical and thermal conditions. Renewable energy projects may create requirements for alloys used in equipment exposed to environmental stress, temperature variation, or corrosive conditions. Medical device applications offer opportunities where specialized material properties and stringent quality requirements are necessary.
The market is forecast to reach USD 84.97 billion by 2035, supported by a CAGR of 3.42%. Continued customization, manufacturing innovation, and demand for reliable materials across critical industries are expected to influence its trajectory. Suppliers that align alloy development with evolving technical requirements and efficient production practices may be positioned to serve these long-term needs.