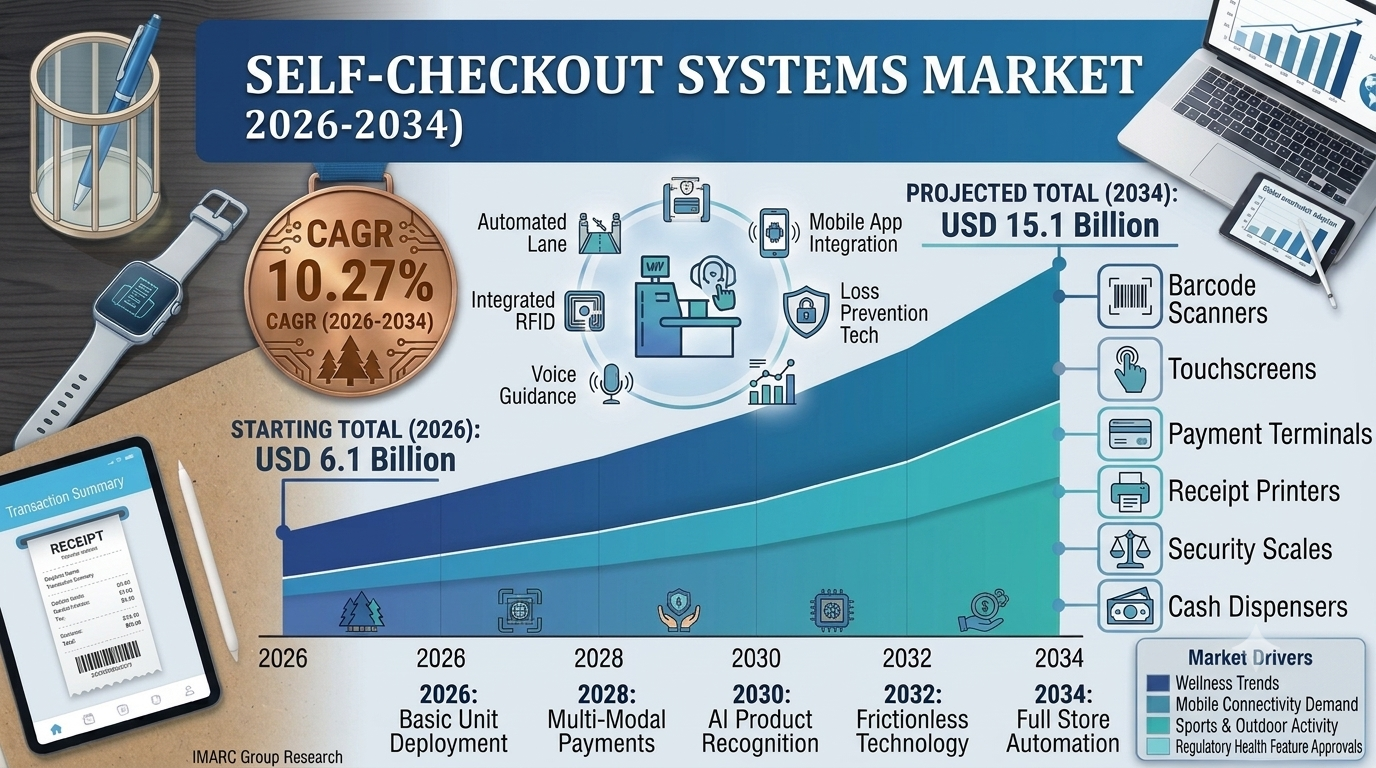
According to IMARC Group, the global self-checkout systems market size reached USD 6.1 Billion in 2025 and is projected to reach USD 15.1 Billion by 2034, expanding at a CAGR of 10.27% during 2026–2034. This strong self-checkout systems market growth reflects rising labor costs, growing consumer preference for contactless and cashless transactions, heightened hygiene expectations since the pandemic, and continuous innovation in AI, IoT, and computer-vision-based loss prevention.
Self-Checkout Systems Industry Overview
A self-checkout system is a retail technology solution that allows customers to scan, bag, and pay for their own purchases without the assistance of a cashier. Built around barcode or RFID scanning hardware, point-of-sale software, and secure payment terminals, these systems are designed to reduce transaction time, minimize labor dependency, and improve the overall shopping experience across high-footfall retail formats.
Self-checkout deployments span a wide range of retail environments:
- Supermarkets and hypermarkets: High-volume grocery and general-merchandise checkout lanes designed to handle large daily transaction counts
- Convenience stores: Compact, space-saving kiosks suited to quick, low-item-count purchases
- Departmental stores: Multi-category retail environments requiring flexible scanning and payment configurations
- Specialty and emerging retail formats: Pharmacies, fuel-and-convenience outlets, and smaller-format stores adopting self-service checkout to stay competitive
Global Self-Checkout Systems Market Size & Key Statistics
Below are the key self-checkout systems market statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020–2025 |
| Forecast Period | 2026–2034 |
| Self-Checkout Systems Market Size in 2025 | USD 6.1 Billion |
| Market Forecast in 2034 | USD 15.1 Billion |
| Market Growth Rate (2026–2034) | 10.27% CAGR |
| Largest Region | North America |
| Leading Offering Segment | Hardware |
| Leading Model Type | Cash Model Type |
| Leading Mounting Type | Wall-Mounted and Countertop Mounting |
| Leading End-Use Segment | Supermarkets and Hypermarkets |
Request for a Sample Report for Detailed Self-Checkout Systems Market Share Evaluation: https://www.imarcgroup.com/self-checkout-systems-market/requestsample
Key Market Drivers & Self-Checkout Systems Market Trends in 2025
Several powerful forces are shaping self-checkout systems market trends and fuelling sustained growth expectations across global retail technology markets:
- Escalating Global Labor Costs
Rising wages, hiring expenses, and staff-retention costs are pushing retailers to automate front-end operations. Self-checkout systems reduce dependency on cashier headcount, allowing retailers to redeploy staff toward customer service and loss-prevention roles while containing operating expenses — particularly in regions with strict labor regulations and higher minimum wages.
- Growing Focus on Hygiene and Contactless Shopping
Heightened post-pandemic awareness of hygiene and safety continues to support adoption, as self-checkout lanes limit physical contact between staff and shoppers. Features such as antimicrobial touchpoints and UV sanitization are increasingly bundled into newer kiosk designs, reinforcing consumer confidence in self-service checkout.
- Rising Preference for Contactless and Mobile Payments
The integration of mobile wallets, tap-to-pay cards, and QR-based payment options into self-checkout kiosks is a defining Self-Checkout Systems Market Trend. This flexibility caters to a broader base of digitally native shoppers while speeding up transaction times at the point of sale.
- AI, Machine Learning, and Computer-Vision Integration
Retailers are embedding AI-driven weight verification, computer-vision item recognition, and machine-learning-based fraud detection into self-checkout hardware to curb theft and scanning errors — one of the industry's most persistent challenges — while also enabling personalized product recommendations at checkout.
- IoT-Enabled Remote Monitoring and Maintenance
Internet of Things connectivity allows retailers to monitor kiosk performance, cash levels, and technical faults in real time, reducing downtime and ensuring self-checkout lanes remain operational during peak shopping hours.
- Retail Expansion and Modernization Across Emerging Markets
Expanding organized retail infrastructure across Asia-Pacific and Latin America, combined with rising consumer familiarity with self-service technology, is opening new deployment opportunities for self-checkout vendors beyond their traditional North American and European strongholds.
Key Market Segmentation
By Offering
Hardware — Largest Segment: Hardware, comprising scanners, payment terminals, and kiosk enclosures, commands the largest self-checkout systems market share as every deployment requires a physical terminal footprint. Software and services — covering transaction software, analytics, and maintenance contracts — round out the offering segment and are growing steadily as retailers seek ongoing system optimization.
By Model Type
Cash Model Type — Largest Segment: Cash-enabled self-checkout systems hold the largest market share, reflecting continued demand in regions with lower card penetration and shoppers who prefer cash transactions. Automated cash recyclers and improved fraud-prevention technology have strengthened retailer confidence in cash-based self-service lanes. Cashless model type is expanding quickly alongside the broader shift toward digital payments.
By Mounting Type
Wall-Mounted and Countertop Mounting — Largest Segment: This configuration leads the market thanks to its space efficiency, making it well-suited to convenience stores and smaller-format retail outlets where floor space is limited. Stand-alone mounting remains popular in high-volume supermarket and hypermarket settings that can accommodate dedicated self-checkout islands.
By End User
Supermarkets and Hypermarkets — Largest End-Use Segment: High transaction volumes and the need to minimize queue times make supermarkets and hypermarkets the dominant end-use segment. Departmental stores and convenience stores follow, each adopting self-checkout formats tailored to their footfall patterns, while other specialty retail formats represent an emerging growth pocket.
Regional Self-Checkout Systems Market Analysis
| Region | Key Highlights |
| North America — Largest | United States & Canada; high consumer technology adoption, dense presence of international retail chains, strong emphasis on operational efficiency and customer convenience |
| Europe | Germany, France, UK, Italy, Spain, Russia; mature retail automation base, rising contactless payment adoption, strong supermarket chain investment in self-service checkout |
| Asia-Pacific — Fastest Growing | China, Japan, India, South Korea, Australia, Indonesia; rapid organized-retail expansion, rising disposable incomes, growing modernization of supermarket and convenience-store formats |
| Latin America | Brazil, Mexico; expanding modern retail infrastructure and increasing hypermarket penetration supporting gradual self-checkout adoption |
| Middle East and Africa | Growing investment in retail modernization and shopping-mall infrastructure creating early-stage opportunities for self-checkout deployment |
Connect for Detailed Self-Checkout Systems Market Share Segmentation Analysis — Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=2428&flag=C
Leading Players in the Global Self-Checkout Systems Industry
The global self-checkout systems market features a mix of established retail-technology hardware manufacturers and specialized point-of-sale solution providers. Key companies covered in the IMARC Group report include:
| Company | Competitive Strength |
| Diebold Nixdorf Inc. | Broad self-service checkout and retail automation hardware portfolio |
| Digimarc Corporation | Digital watermarking technology supporting faster, more accurate item recognition |
| ECR Software Corporation | Point-of-sale and retail management software integration |
| Fujitsu Limited (Furukawa Group) | Retail technology hardware and systems integration expertise |
| IBM Corporation | Enterprise-grade retail analytics and AI-enabled checkout solutions |
| ITAB Scanflow AB | Self-checkout kiosk design and store-fixture integration |
| NCR Corporation | Market-leading POS and self-checkout terminal installed base |
| Pan-Oston Co. | Checkout furniture and self-service kiosk manufacturing |
| PCMS Group Inc. | Retail software platforms supporting omnichannel checkout |
| Toshiba TEC Corporation | Integrated POS hardware and retail technology solutions |
Leading players are prioritizing R&D investment in AI-driven transaction processing and enhanced security features, while pursuing strategic partnerships with major retail chains and geographic expansion into emerging markets to strengthen their competitive position and capture rising Self-Checkout Systems Market Share.
Latest Self-Checkout Systems Market Industry Developments
January 2024 — Stellar Lifestyle (SMRT)
Stellar Lifestyle, the business arm of SMRT, launched Hive 2.0 at Esplanade Xchange within Singapore's Esplanade MRT station, introducing roughly ten retail experiences centered on robotics, automation, and digital retail — including the city-state's first self-checkout 7-Eleven store.
December 2023 — Enactor and Harrods
Enactor partnered with Harrods to launch a new self-checkout system aimed at improving the shopping experience for customers, reinforcing Enactor's commitment to enhancing checkout convenience across its retail client base.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Retail, Technology, Healthcare, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104