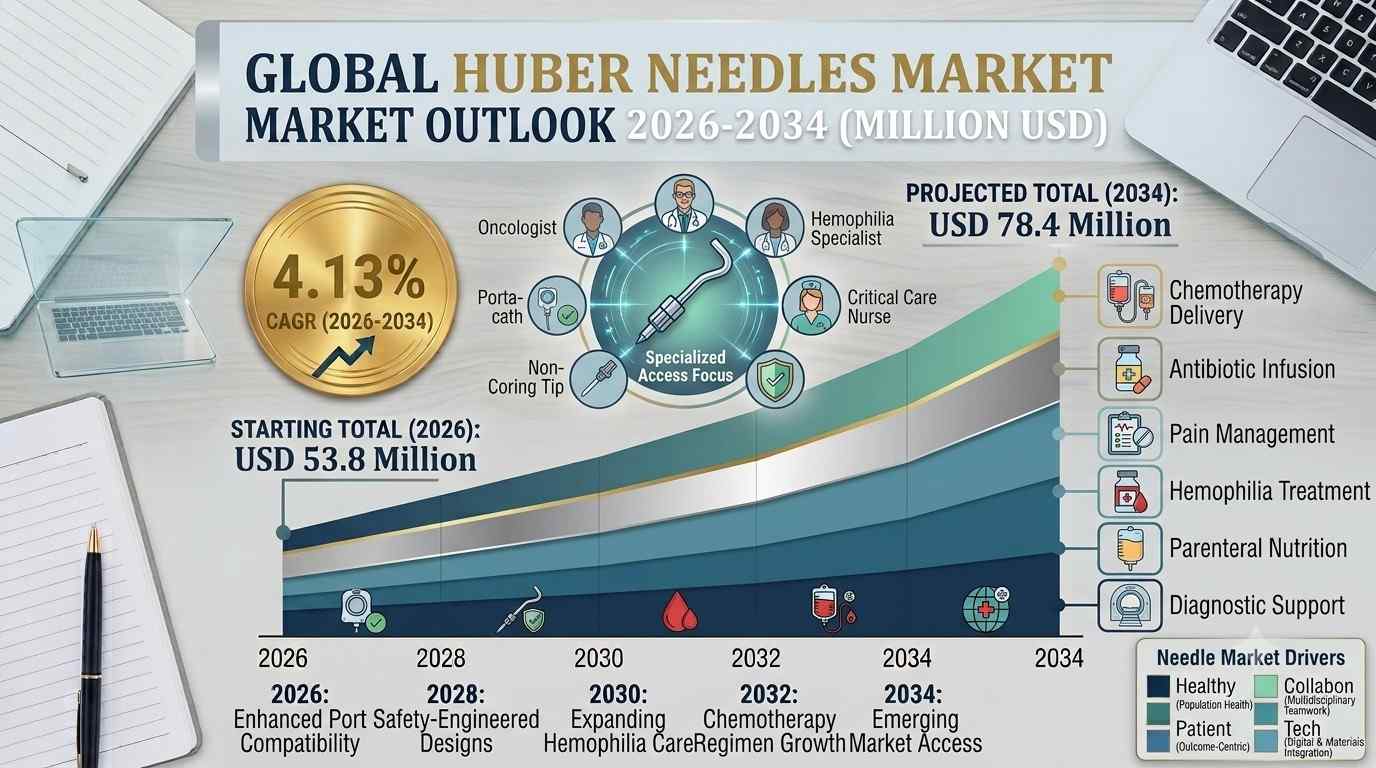
According to IMARC Group, the global huber needles market size reached USD 53.8 Million in 2025 and is projected to reach USD 78.4 Million by 2034, expanding at a CAGR of 4.13% during 2026–2034. This steady huber needles market growth reflects the rising prevalence of cancer and chronic diseases, wider use of implantable ports, ongoing advances in safety-engineered needle design, and tightening infection control standards across healthcare systems.
Huber Needles Industry Overview
A Huber needle is a specialized non-coring needle used to access implanted vascular ports safely and repeatedly. Its design is engineered to reduce coring and limit tissue damage each time a port is accessed, making it well suited to patients who need frequent vascular access over long treatment periods. Ergonomic construction that eases insertion and removal further reduces patient discomfort and complications.
Huber needles are deployed across a broad range of clinical use cases:
- Oncology and chemotherapy: Safe delivery of chemotherapy and other intravenous cancer therapies through implanted ports, including infusion of newly approved oncology drugs
- Blood transfusion: Reliable port access for patients with leukemia, sickle cell anemia, and other hematological disorders who require regular transfusions
- Parenteral nutrition: Long-term nutritional support delivered through implanted ports for patients who cannot rely on oral or enteral feeding
- Pain management and long-term drug administration: Ongoing therapy delivery for chronic conditions requiring repeated, secure vascular access
- Dialysis and chronic disease care: Vascular access support for patients with end-stage renal disease and other long-term illnesses
- Pharmaceutical liquid transfer: Huber-tipped needle designs enabling vented and non-vented vial transfers in drug handling workflows
Global Huber Needles Market Size & Key Statistics
Below are the key Huber Needles Market statistics drawn from IMARC Group's comprehensive market analysis:
| Report Attribute | Key Statistics |
| Base Year | 2025 |
| Historical Period | 2020–2025 |
| Forecast Period | 2026–2034 |
| Huber Needles Market Size in 2025 | USD 53.8 Million |
| Market Forecast in 2034 | USD 78.4 Million |
| Market Growth Rate (2026–2034) | 4.13% CAGR |
| Largest Region | North America (over 42.7% share in 2025) |
| Leading Product Segment | Curved Huber Needles (around 56.4% share) |
| Leading Application | Transfusion of Blood |
| Leading End-User Segment | Hospitals (around 60.0% share) |
Request for a Sample Report for Detailed Huber Needles Market Size Evaluation: https://www.imarcgroup.com/huber-needles-market/requestsample
Key Market Drivers & Huber Needles Market Trends in 2026
Several powerful forces are shaping Huber Needles Market Trends and supporting sustained growth expectations across oncology, hematology, and chronic care markets:
- Rising Prevalence of Cancer and Chronic Diseases
The growing incidence of cancer, chronic illnesses, and blood disorders is a primary catalyst for Huber Needles Market Growth. According to IARC's 2022 report, roughly 20 Million new cancer cases and 9.7 Million cancer deaths were recorded worldwide that year. Patients undergoing chemotherapy frequently need repeated vascular access through implantable ports, which makes Huber needles indispensable for safe drug administration. Conditions such as sickle cell anemia and end-stage renal disease, which call for regular transfusions or dialysis, add to demand, while an aging population requiring long-term treatment reinforces it.
- Growing Adoption of Implantable Ports
The rising use of implantable ports for chemotherapy, dialysis, and long-term drug administration directly lifts demand for compatible access needles. The steady shift toward port-based drug delivery is a defining Huber Needles Market Trend, as healthcare providers look for efficient, safe vascular access solutions that reduce complications associated with traditional access methods.
- Expanding Healthcare Infrastructure and Favorable Reimbursement Policies
Expansion of hospitals, cancer treatment centers, and dialysis clinics—particularly in developed countries—is increasing the use of Huber needles to serve rising patient volumes. Favorable reimbursement policies in regions such as North America and Europe reduce out-of-pocket costs for patients needing frequent vascular access, while government and private insurance coverage for cancer treatment, blood transfusions, and dialysis encourages providers to invest in high-quality needles.
- Stringent Safety Regulations and Infection Control Measures
Regulatory and infection control protocols set by bodies such as the FDA, CDC, and WHO are steering purchasing decisions. The FDA estimates that approximately 50% of single-use medical devices undergo terminal sterilization using ethylene oxide (EtO), and changes in sterilization methods now require extensive revalidation testing covering biocompatibility, chemical characterization, and performance. Providers must also follow strict standards to prevent bloodstream infections linked to implanted ports, and the focus on reducing hospital-acquired infections (HAIs) is accelerating adoption of advanced, safety-engineered Huber needle designs.
- Technological Advancements in Safety-Engineered Needle Design
Manufacturers are investing in non-coring needles with enhanced safety features that improve patient comfort and lower the risk of complications. Recent launches illustrate this direction, including Nipro's Huber needle sets designed to protect against needlestick injuries, Vygon's POLYPERF Safe safety Huber needle for chemotherapy port access, and MedSafety Solutions' dual-purpose TwoFer Needle. Continuous innovation in medical devices remains a significant contributor to Huber Needles Market Growth.
- Rising Geriatric Population and Hospital Admissions
An expanding geriatric population, increasing hospital admissions, and growing awareness of infection prevention and minimally invasive procedures are broadening the patient base requiring long-term intravenous therapies. In the United States, for instance, obesity-related conditions, HIV, and hepatitis add to the number of patients needing safe, durable vascular access, further supporting the huber needles market size.
Key Market Segmentation
By Product
Curved Huber Needles – Largest Segment: Curved Huber needles hold around 56.4% of the market in 2025, owing to their functionality, safety, and widespread use in oncology and long-term vascular access. They are designed to reduce coring and minimize tissue damage when accessing implanted ports, making them ideal for chemotherapy, parenteral nutrition, and pain management. Their ergonomic design eases insertion and removal, and providers value their ability to maintain secure access across varied clinical settings.
Straight Huber Needles: Straight Huber needles form the second product category in IMARC Group's analysis, serving port-access needs alongside curved variants across oncology, transfusion, and infusion care.
By Application
Transfusion of Blood – Largest Application: Blood transfusion holds the largest share, reflecting the high demand for safe and efficient vascular access in critical care, oncology, and chronic disease management. Huber needles are essential for accessing implanted ports in patients with leukemia, sickle cell anemia, and other hematological disorders, and their non-coring design limits tissue damage and infection risk during repeated use.
Application for Cancer: Chemotherapy and other cancer therapies depend on reliable port access, and the rising number of patients undergoing chemotherapy continues to strengthen this segment.
Parenteral Nutrition: Patients requiring long-term nutritional support through implanted ports rely on Huber needles for secure, repeatable access.
Others: Covers additional uses such as pain management and long-term drug administration through implanted ports.
By End User
Hospitals – Largest End-User Segment: Hospitals lead with around 60.0% of the market in 2025 due to the high volume of procedures requiring safe vascular access, including chemotherapy, blood transfusions, dialysis, and parenteral nutrition. Well-equipped infrastructure, skilled healthcare professionals, and adherence to strict safety protocols further drive adoption, alongside rising cancer prevalence, increasing admissions, and advances in port-based drug delivery.
Clinics: Cancer treatment centers and dialysis clinics are increasing their use of Huber needles to meet growing patient demand for outpatient infusion and transfusion care.
Ambulatory Surgical Centers: Ambulatory surgical centers represent a further care setting tracked in the report, supported by the shift toward minimally invasive procedures.
Others: Includes infusion centers and other care settings that administer long-term therapies via implanted ports.
Regional Huber Needles Market Analysis
| Region | Key Highlights |
| North America – Largest | United States & Canada; over 42.7% market share in 2025; high cancer and chronic disease burden, advanced healthcare infrastructure, favorable reimbursement, high healthcare spending, and the presence of key market players; the U.S. accounts for over 87.70% of the regional market |
| Europe | Germany, France, United Kingdom, Italy, Spain; 35.0% of EU residents reported a long-term (chronic) health issue in 2023, increasing the need for chemotherapy, dialysis, and parenteral nutrition devices; growing emphasis on minimizing catheter-associated complications |
| Asia Pacific | China, Japan, India, South Korea, Australia, Indonesia; rising investment in healthcare infrastructure, with USD 22.52 Billion of FDI equity inflow into India's drugs and pharmaceuticals sector between April 2000 and March 2024; growing private investment in specialty clinics and infusion centers |
| Latin America | Brazil, Mexico; around 1.5 Million new cancer cases and 750,000 cancer deaths in the region in 2022; rising demand for improved infusion therapies and supportive cancer care |
| Middle East & Africa | Expanding medical infrastructure and hospital investment; Dubai alone had 4,482 private medical facilities and 55,208 licensed professionals by 2022; growing focus on infection prevention and patient safety |
North America leads the global huber needles market, accounting for over 42.7% of the share in 2025. The region benefits from a high prevalence of cancer, chronic diseases, and blood disorders requiring frequent vascular access, widespread adoption of implantable ports, and stringent safety and infection control standards. Within the region, the United States represents over 87.70% of the market. According to industry reports, prostate, lung, and colorectal cancers made up about 48% of cancers identified in men in 2024, while breast, lung, and colorectal cancers accounted for around 51% of new cancer cases in women. CDC data also show that at least 35% of U.S. adults were living with obesity in 2022, expanding the patient base needing long-term intravenous therapies.
Europe and Asia Pacific are also contributing meaningfully to huber needles market trends. In Europe, the rising burden of chronic and age-related illnesses is fueling demand for long-term vascular access, while Asia Pacific is being lifted by healthcare modernization, hospital network expansion, and training programs that improve procedural efficiency.
Connect for Detailed Huber Needles Market Growth and Segmentation Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=12947&flag=C
Leading Players in the Global Huber Needles Industry
The Huber needles market is highly competitive, with key players focusing on product innovation, safety enhancements, and strategic partnerships. Leading companies such as Becton, Dickinson and Company (BD), Baxter International, Smiths Medical, Nipro Corporation, and AngioDynamics compete through extensive product portfolios and global distribution networks, while emerging players are intensifying competition with cost-effective and innovative solutions, particularly in North America and Europe. Key companies covered in the IMARC Group report include:
| Company | Recent Activity Highlighted | Competitive Focus |
| Becton, Dickinson and Company (BD) | Investing over USD 10 Million to expand U.S. manufacturing (Connecticut and Nebraska plants) for huber needles, syringes, and IV catheters (January 2025) | Domestic capacity expansion, broad portfolio, global distribution |
| Smiths Medical Inc. (ICU Medical Inc) | Acquired by ICU Medical from Smiths Group plc (January 2022), adding syringes, ambulatory infusion devices, needles, vascular access, and critical care supplies | Infusion therapy portfolio expansion through M&A |
| Vygon S.A. | Vygon India launched POLYPERF Safe, a safety Huber needle for chemotherapy port access (December 2021) | Safety-engineered vascular access |
| Nipro Corporation | Launched Huber needle sets built for precise punctures and needlestick-injury protection (January 2024) | Precision and needlestick safety |
| B. Braun Medical Inc., Exelint International Co., Medline Industries, Medsurg | Profiled in IMARC Group's competitive landscape analysis | Product quality, safety standards, and distribution reach |
Latest Huber Needles Market Industry Developments
January 2025 – BD (Becton, Dickinson and Company)
BD announced over USD 10 Million in investments to expand its U.S. manufacturing network and raise production of critical medical devices, including Huber needles, syringes, and IV catheters. New production lines have been installed at its Connecticut and Nebraska plants, with one already operational and more launching soon, to meet growing demand for essential health care supplies in the U.S.
October 2024 – MedSafety Solutions
MedSafety Solutions introduced the TwoFer™ Needle, a dual-purpose Huber-tipped needle that supports both vented and non-vented vial transfers. Offered in two color-coded lengths, it streamlines liquid drug movement without frequent needle changes, improving efficiency and safety in pharmaceutical applications.
October 2024 – FDA Approval of Zolbetuximab-clzb (Vyloy)
The FDA approved zolbetuximab-clzb (Vyloy) with chemotherapy as first-line treatment for CLDN18.2-positive, HER2-negative gastric or gastroesophageal junction adenocarcinoma, alongside the VENTANA CLDN18 (43-14A) RxDx Assay for patient identification. The therapy is administered by intravenous infusion using a Huber needle for safe and effective delivery.
February 2024 – FDA Approval of AstraZeneca's Tagrisso Combination
The FDA approved Tagrisso (osimertinib) with chemotherapy for advanced lung cancer with an EGFR mutation, based on the FLAURA2 trial, which showed a 38% lower risk of disease progression or death and an 8.8-month gain in median progression-free survival. Patients on such regimens may need a Huber needle to receive chemotherapy safely through implanted ports.
January 2024 – Nipro
Nipro launched Huber needle sets that support accurate punctures while protecting against needlestick injuries, strengthening safety without compromising reliability in use.
January 2022 – ICU Medical Inc.
ICU Medical completed its acquisition of Smiths Medical from Smiths Group plc, broadening its infusion therapy portfolio across syringes, ambulatory infusion devices, needles, vascular access, and critical care supplies. The combined company is projected to generate pro forma revenue of about USD 2.5 billion.
December 2021 – Vygon India
Vygon India launched POLYPERF Safe, a safety Huber needle for chemotherapy port vascular access, designed to improve treatment effectiveness while reducing risks for patients and clinicians.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104